


Recent upward revisions to earnings forecasts for Albany International (AIN) and a favorable Zacks Rank have put fresh attention on the stock ahead of its October 28 quarterly results.
Recent trading reflects that shift in sentiment. Albany International’s share price has climbed 7.24% over the past week and 9.56% over the past month, while a 12.97% decline over the past quarter contrasts with a 24.19% year to date share price return and a 15.66% total shareholder return over the last year. This points to positive momentum rebuilding ahead of earnings.
Look beyond Albany International and consider other industrials where analysts identify similar momentum inflections with our curated 33 high quality undervalued stocks.
The recent rebound in Albany International after a weak quarter presents investors with a choice. They can treat the pullback as a second chance to buy, or they can wait and risk the valuation moving higher first.
Most Popular Narrative: 100% Undervalued
On the numbers that matter, the most followed narrative puts Albany International’s fair value at $65.67 compared with a last close of $65. That tiny gap keeps attention on what really has to work inside the business for that figure to hold.
The main thing that has to go right is that Albany International turns the Salt Lake City composites facility into a consistently cash generative site by 2027 while maintaining resilient Machine Clothing margins despite softer demand and industry overcapacity.
The current numbers and external commentary together imply a share price that already reflects a fair valuation for Albany International with limited market credit assigned to the newer Engineered Composites growth platforms.
See why 2 investors see Albany International as 1% undervalued.
Result: Fair Value of $65.67 (UNDERVALUED)
Still, the narrative around Albany International can break if cash generation from Machine Clothing erodes or if recent composites investments fail to lift profitability as analysts expect.
Find out about the key risks to this Albany International narrative.
Another View: What Multiples Say About Albany International
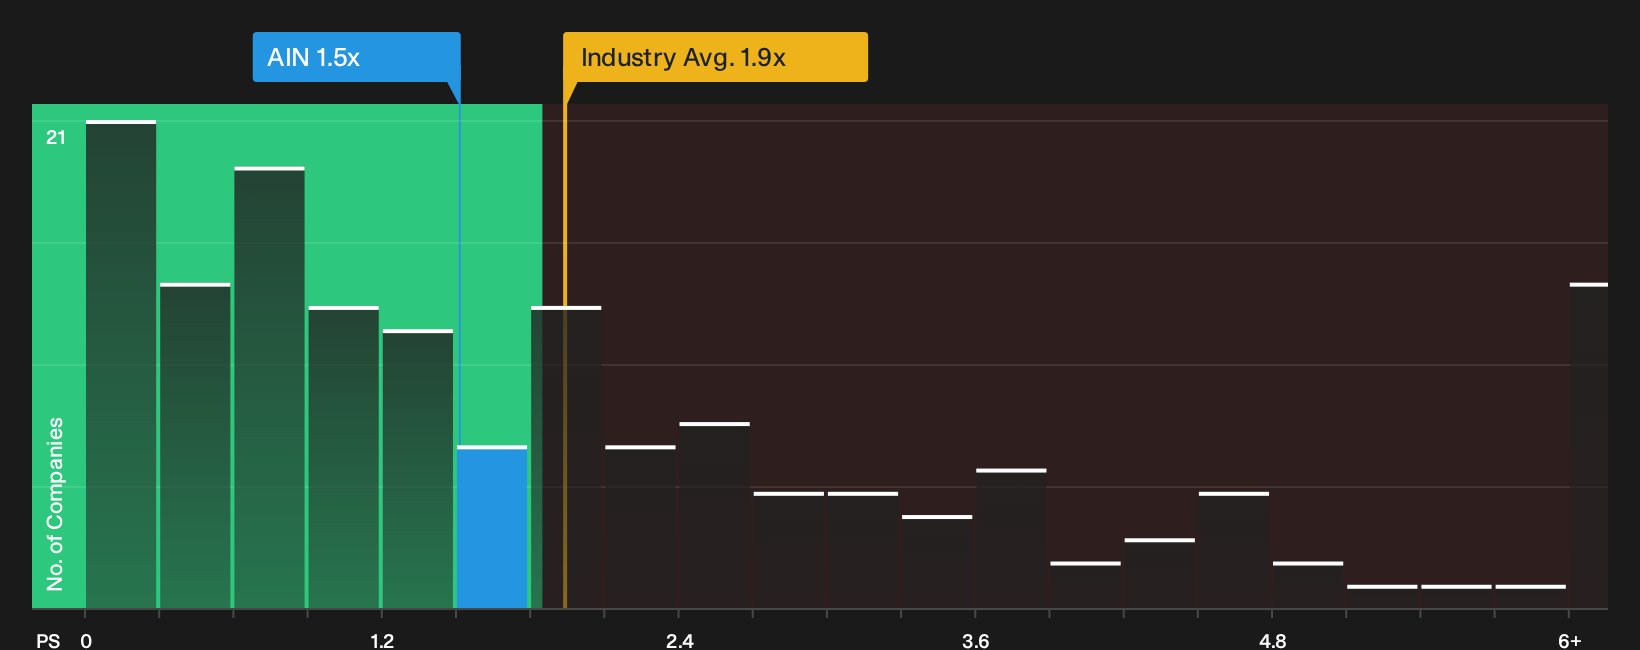
On a P/S basis, Albany International trades at 1.5x, while the estimated fair ratio is 1x. That gap suggests the share price already bakes in a fair amount of optimism, even though the current P/S is lower than both the US Machinery industry average of 1.9x and the peer group on 2.1x. Is that premium a cushion or a thin margin for error?
For a closer look at how this pricing compares with the underlying business metrics, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Albany International only matters if it pushes you to act while the data is still fresh. Weigh the upside against the downside, and then stress test your own thesis with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Albany International?
Do not stop your research with Albany International. Apply the same disciplined lens across a wider watchlist so you are prepared before the next setup appears.
- Explore potential upside in companies the market may be overlooking by scanning our curated 21 high quality undiscovered gems.
- Strengthen your downside protection by focusing on businesses with resilient finances through the list of solid balance sheet and fundamentals (25 results).
- Prioritize peace of mind and steadier performance across different environments by filtering for 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com