


The Zhitong Finance App noticed that hedge funds significantly increased their short stock positions this month, pushing bearish bets to a five-year high. Once the market rebounds, it will increase the risk of a sharp shorting.
According to data from Goldman Sachs Group's main brokerage department, the ratio of short selling transactions to buying long positions is about 5 to 1 in global stocks. The short leverage on its ledger is at the 99th percentile of the past five years. Despite an increase in overall leverage, the net leverage of fundamental long and short funds — a measure of how long exposure exceeds the margin of short positions — is close to a three-year low.
This retreat came after the AI deal closed sharply. The higher-than-expected US inflation data, combined with renewed market doubts about whether huge investment in AI computing power could bring returns, triggered a sell-off in semiconductor and infrastructure stocks, and continued the decline that began in Asian memory chip stocks. The Nasdaq 100 index fell 5.5% last week, the biggest weekly decline since April 2025, while futures for the benchmark index fell nearly 2% on Thursday.
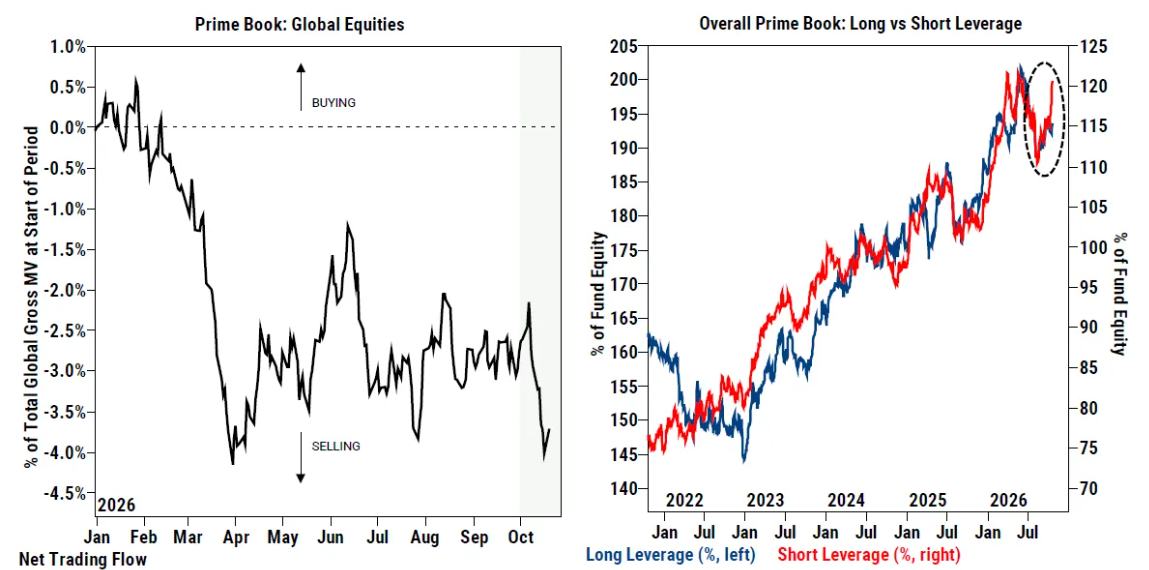
This round of closing positions seems expensive. Goldman Sachs's team, led by Vincent Lin, wrote in a report this week that as of Monday, global fundamental long and short funds had fallen 2.5% in October, narrowing the full-year increase to 10.1%. Funds focused on technology, media and telecommunications performed the worst, falling 7.4% so far this month.
The department threw out the phrase “empty risk alert” in the data summary and added a question mark after it to reflect uncertainty. Crowded short positions can create conditions for shortfall, but they don't necessarily provide a catalyst; these bears were set up in a round of tech stock sell-offs with identifiable fundamental drivers. Based on position data alone, it is difficult to see that the market background has changed.
In the two weeks ending October 16, global information technology stocks recorded the largest two-week net sale in the department's record in more than a decade. The net allocation of Goldman Sachs's basket of global AI stocks was at the 38th percentile over the past year, while the sector's long/short ratio was in the 6th percentile. Therefore, any catalyst to lift technology stocks from their current position will face short positions that need to be made up.
Europe is the only major region to record moderate net purchases so far this month, and net exposure to “Big Seven Tech” stocks has risen to a record high even as the broader tech sector is sold off.
The data shows that hedge funds are “hedging and hedging” rather than “clearing and leaving the market.” Short exposure is high and net exposure is low, and technology stocks are still the core of position layout.