


Following Jinfang Pharmaceutical-B (02595)'s Phase II efficacy data for the innovative product GFH375 published in the oral report at this year's WCLC conference on September 14 this year, the combination therapy of this drug combined with cetuximab was also included in the domestic breakthrough therapy certification list on September 18.
The Zhitong Finance App observed that under the heavy favorable catalyst mentioned above, the market changed its previous “safe-haven before the ban is lifted” sentiment, which led to the subsequent increase in Jinfang Pharmaceutical's stock price.
“V-shaped repair” brought about by data that exceeded expectations
In fact, from August 26 to September 11, Jingfang Pharmaceutical's stock price emerged from a round of unilateral decline, with a cumulative decline of nearly 20% over 13 trading days. The reason for this is, on the one hand, the recent overall correction in the Hong Kong stock pharmaceutical sector, and the Hang Seng Healthcare Index fell 6.59% during the same period; on the other hand, the company faced a wave of major shareholders' lifting of the ban on September 19.
According to the data, the lifting of the ban on Jingfang Pharmaceutical involved 235 million shares of the company's 47 shareholders, accounting for about 61.31% of the total share capital, and the corresponding market value of the lifting of the ban reached HK$6.111 billion. In addition, Jinfang Pharmaceutical also experienced a change in its inventory on September 3, with a total market value of HK$1,955 billion, accounting for 19.65%.
Because of this, the market was more inclined to price the company based on “uncertainty” at the time, until the disclosure of data exceeding expectations for the company's core products at the WCLC conference on September 14.
Zhitong Finance App learned that the oral report of the WCLC conference showed the excellent efficacy of GFH375 on NCSLC patients at the 600 mg QD dose level. Nearly 100% of the enrolled patients had distant metastases, and more than 40% had received two or more treatments: as of the data cutoff date, 71 patients had completed at least one post-treatment evaluation, with ORR of 59.2%, CorR of 52.1%, and DCR of 93%; in addition, patients who had not received yarrow drugs in the past had MPFs of 9.6 months, and all patients had an overall survival of 12 months The rate is 77%.
This data structure clearly exceeded previous market expectations. On September 17, BOC International stated in an updated research report, “Compared with the phase I results of the key competitor RMC-9805, GFH375 obtained similar mPFs in patients with a lower number of treatment lines and similar past medication history. The overall 12-month OS rate, ORR, and DCR were also better or more consistent than the latter. Safety was generally manageable at the 600mg QD dose and was consistent with previous reports, and no new safety signals were found.”
As a result, the bank raised GFH375's long-term global revenue forecast, allowing Jinfang to maintain Jinfang Pharmaceutical's purchase rating and target price of HK$51.
The appearance of the weather vane signal also quickly boosted market sentiment.
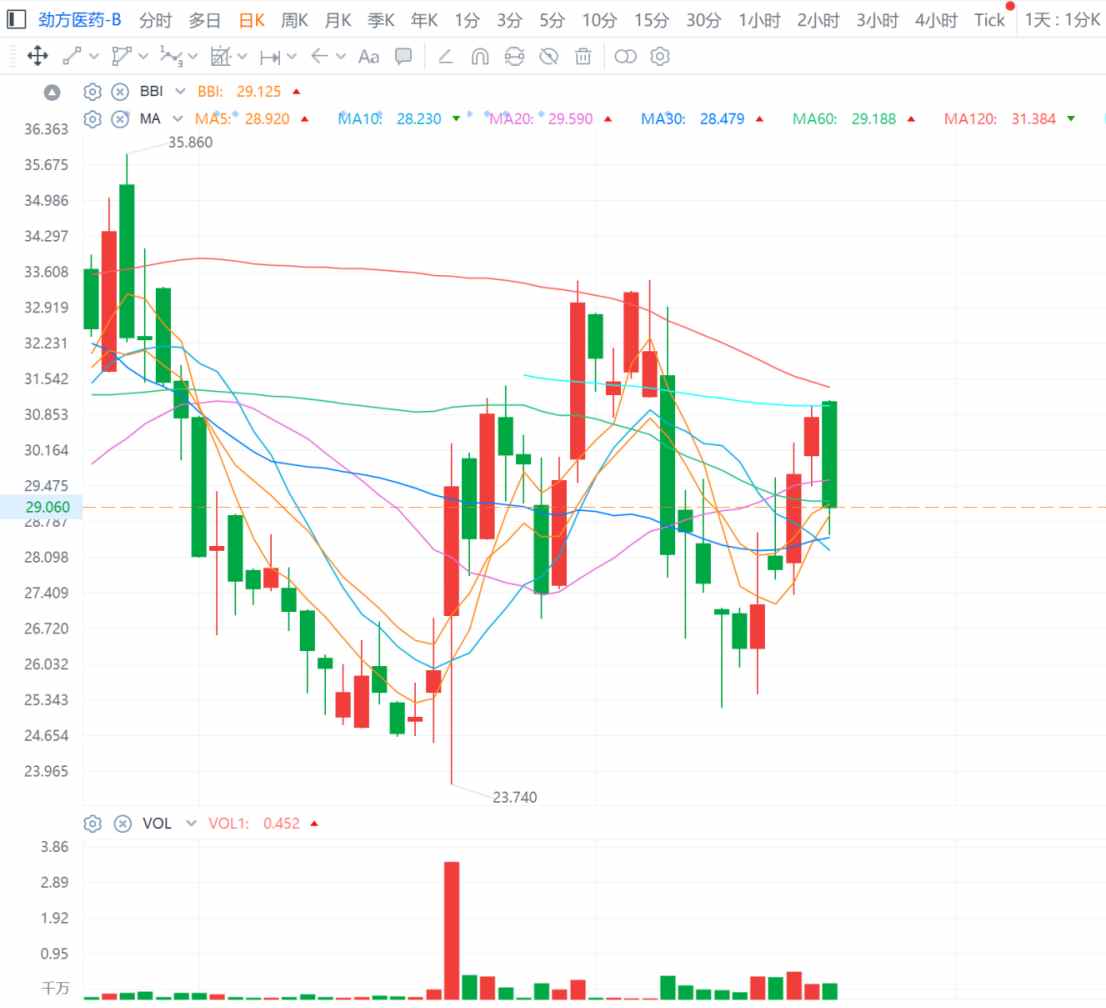
From September 17 to October 7, Jingfang Pharmaceutical's stock price showed a significant recovery period, with the biggest increase in the stock price range of 39.85%. In particular, on September 21, Jingfang Pharmaceutical experienced a round of “Tianliang Changyang” on the market: the company's stock price closed up 13.75%; the single-day stock turnover reached HK$993 million, and the corresponding turnover rate reached 10.66%. The company's daily trading volume and turnover reached 27 times and 28.7 times the average volume on September 15-18, respectively.
On the technical side, the sharp rise on September 21 also directly initiated the restoration and strengthening of the subsequent moving average and trend in Jinfang Pharmaceutical's stock price.
Driven by positive market sentiment, the stock price of Jingfang Pharmaceutical continued to rise. The 20-day, 30-day, and 60-day EMAs were quickly repaired within the next 20 days. The short-term trend of the monitor has changed from a weak recovery to a strong one. In terms of momentum indicators, the MACD gold fork recovery during the same period and the strengthening of the RSI/KDJ index also indicate that market funding is once again giving Jingfang Pharmaceutical a premium in terms of clinical catalysis.
The cooling trend in the sector is difficult to hide market sentiment
Looking at the long-term timeline, Jinfang Pharmaceutical's stock price trend from September 17 to now is not a one-sided increase; it has experienced a round of correction from October 8 to 14.
The reason for this was an industry incident: the overseas phase III clinical trial of vometinib did not reach the main end point, causing its overseas partner ArriVent's stock price to plummet by nearly 47% in a single day. Under the influence of this negative incident, the market directly lowered the valuation of domestic innovative drugs going overseas, the phase III clinical success rate, and the probability of achieving overseas milestones, and completed the logical transition from “pipeline imagination space” to “verifying real clinical implementation ability”. This seriously suppressed the mood of the AH innovative drug sector on the same day, and many unprofitable, highly valued biotechs that relied on future clinical data were the first to bear the brunt.
However, after a short-term correction, the stock price of Jingfang Pharmaceutical quickly rebounded after October 15, and what supported the changes in its stock price and the bullish sentiment of investors in the market were announcements issued one after another on September 23 and October 15.
According to the Zhitong Finance App, on September 23, Jingfang Pharmaceutical announced that the company's clinical project GFH375 combined with cetuximab combination therapy was proposed to be included in the Breakthrough Therapy (BTD) list by the Drug Evaluation Center of the State Drug Administration on September 18, 2026 to treat KRAS G12D mutant metastatic colorectal cancer that has previously failed chemotherapy based on oxaliplatin, fluorouracil, and irinotecan.
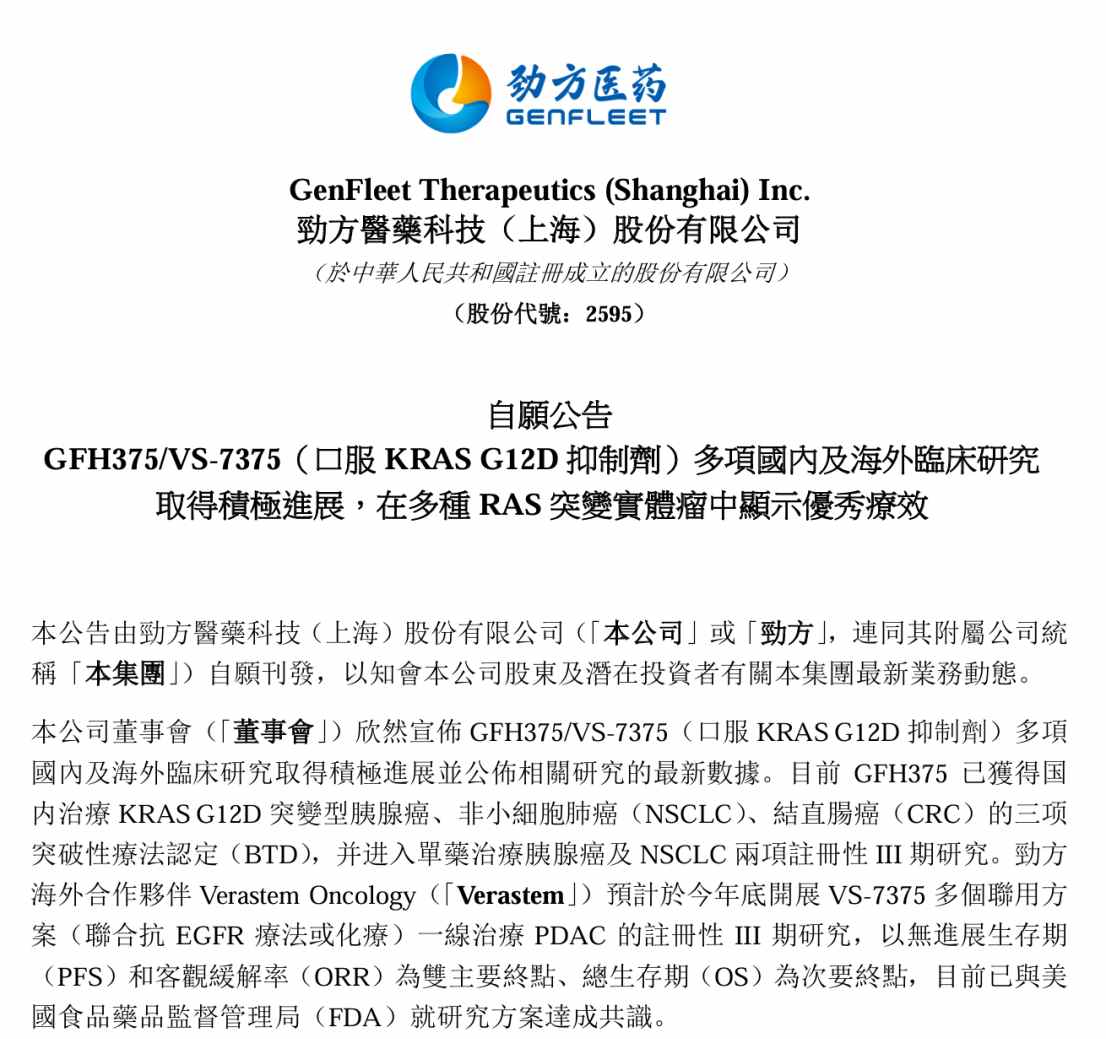
Afterwards, in a voluntary announcement on October 15, the company further disclosed that in combination with cetuximab, the ORR was 44%, the DCR was 89%, and the median PFS was 7.3 months; in 24 patients with newly treated pancreatic cancer, the ORR was 71% and the DCR was 100%.
At the same time, Jingfang Pharmaceutical also confirmed in the announcement that GFH375 has obtained three BTDs for pancreatic cancer, NSCLC, and colorectal cancer in China, and has entered the registered phase III phase III of pancreatic cancer and pancreatic cancer; overseas partner Verastem expects to launch VS-7375 first-line pancreatic cancer phase III by the end of the year, and has reached an agreement with the FDA on the plan.
The positive development of core innovative varieties also means that Jingfang's pricing anchor has expanded from a “single NSCLC backline drug” to a “global pipeline with multiple indications, single drug+joint, and domestic+overseas three-tier promotion”.
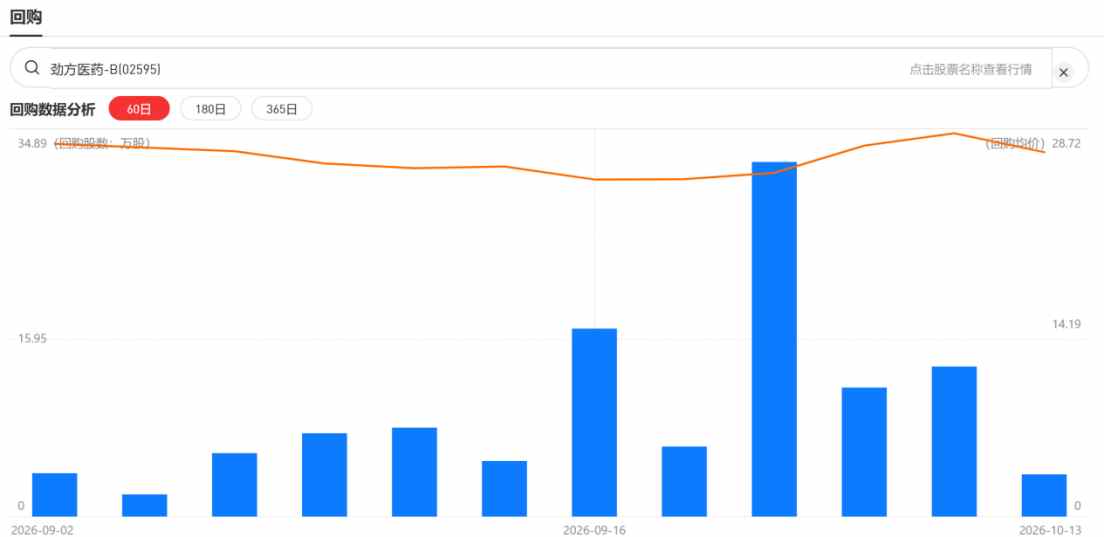
In addition to the above factors, Jingfang Pharmaceutical's continued share buybacks are also one of the important reasons supporting market confidence. According to data from the Zhitong Finance App, since September 8, Jinfang Pharmaceutical has carried out 12 stock repurchases. The number of shares repurchased was 1.161,000 shares, involving capital of HK$3.4056 million.
Although the total number of shares repurchased by the company in this round accounts for only 0.3% of the company's total share capital, and the signal significance is greater than the actual buying strength, the continuous repurchase still conveys the attitude that “the board of directors believes that the current stock price of the company is still lower than intrinsic value”, providing a foundation of confidence for the management of Jinfang Pharmaceutical in the future.
In an announcement issued on October 15, Jingfang Pharmaceutical mentioned preliminary clinical research data on its product GFH276 (Pan RAS inhibitor) for treating RAS mutant solid tumors as a single agent, which has been selected for the Breakthrough Research Summary (LBA) of the 2026 European Society of Medical Oncology (ESMO) Annual Meeting to be held in Madrid.
The Zhitong Finance App learned that as an oral pan-RAS inhibitor, GFH276 uses the CyPA-GFH276-Ras tri-complex mechanism to cover KRAS G12C, G12D, G12V, and activated RAS proteins such as NRAS and HRAS. Previous preclinical data showed that its potency, PK, and safety characteristics had differential advantages over RMC-6236, and only about 1/3 of the dose was required to achieve comparable anti-tumor effects.
Against the backdrop of further verification of Revolution Medicines' pan-ras drug RMC-6236 in August of this year, global pharmaceutical companies' attention to Pan-RAS has increased significantly. Therefore, some organizations believe that this may bring higher premium expectations to future overseas licensing negotiations for GFH276. In its research report, BOC International also clearly listed the GFH276 solid tumor data disclosed at ESMO's annual meeting as a key catalyst for the company's subsequent stock price performance.
Therefore, as another major platform-based asset of Jingfang Pharmaceutical, if the key data disclosed by GFH276 at this ESMO conference clearly exceeds expectations, it may usher in a new round of valuation revisions in the future.