


- Mitsubishi Corporation approved the final investment decision for the Copper World project in Arizona, backing construction of a major U.S. copper mine through a joint venture with Hudbay Minerals and committing total funding of about US$1.02b alongside project debt and stream financing.
- The Copper World commitment deepens Mitsubishi's exposure to long-life copper supply, tying capital allocation directly to future demand for energy transition metals and large-scale infrastructure.
- The next phase will center on how Mitsubishi's Copper World commitment reshapes the investment narrative around capital discipline, commodity exposure, and long-term earnings mix.
Mitsubishi Investment Narrative Recap
To own Mitsubishi, investors need to buy into a long game in which resource exposure, energy transition projects and consumer-facing cash flows all matter. The Copper World stake fits into that mix by tying more capital to copper volumes that relate to infrastructure and electrification themes. The near-term focus remains on how well management maintains earnings quality as cyclical commodities move around.
The biggest swing factor over the next couple of years is execution on capital allocation while keeping cash generation resilient across LNG, mineral resources and consumer businesses. Copper World is large but does not immediately change the main risk, which is prolonged commodity price weakness pressuring margins and funding flexibility.
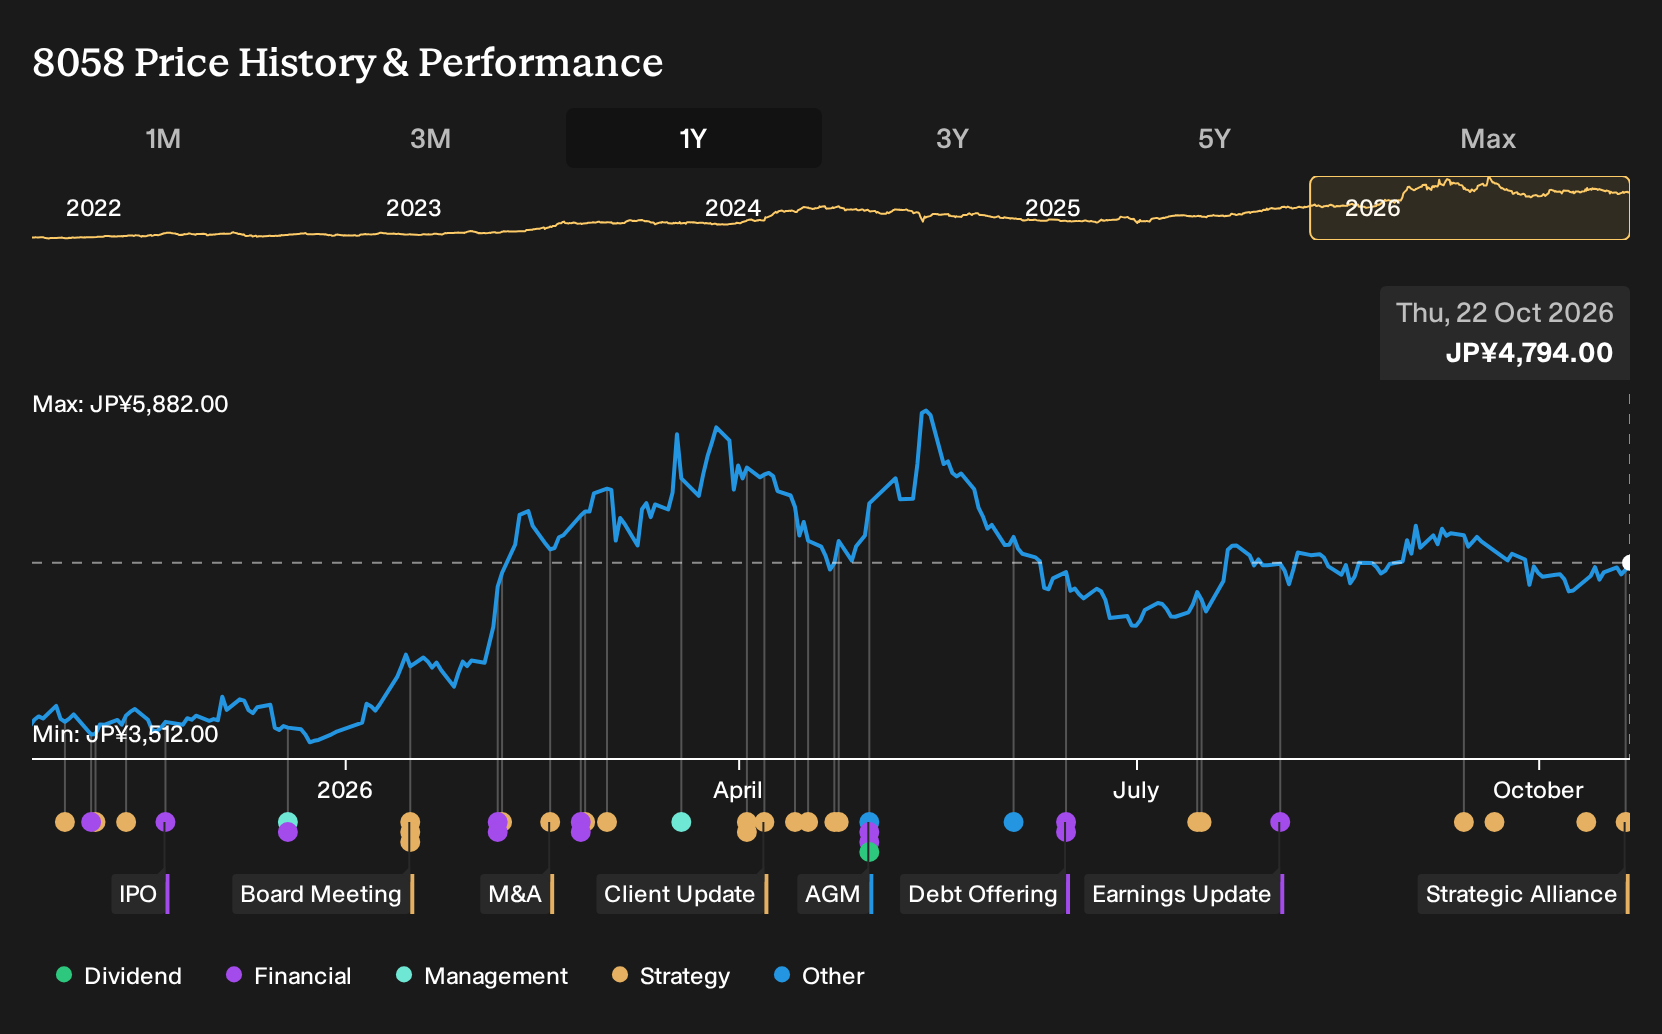
The Copper World final investment decision is the clearest recent signal of where Mitsubishi is directing growth capital. Around US$1.02 billion of total funding exposure across initial equity and future contributions, together with project-level debt and stream financing, links the group more closely to long-life copper output in the Americas. That makes project timing, cost control and permitting milestones operationally important.
For potential catalysts, progress updates on construction, project-level debt drawdown and any revisions to scope or capital intensity at Copper World now sit alongside existing LNG and food supply investments on investors’ watchlists. A key risk is that a capital-intensive copper asset enters a weaker pricing backdrop, which would test the payoff from this incremental exposure.
Mitsubishi's current earnings are ¥895.9 billion and analysts forecast earnings of ¥1,164.2 billion by 2029. This implies an earnings increase of about ¥268 billion on revenue that is expected to reach ¥22,926.6 billion in the same year, based on a projected 4.9% yearly revenue growth rate.
Uncover how Mitsubishi's fair value indicates a 10% potential upside to its current price before the gap between price and value narrows.
Exploring Other Perspectives
One alternate view focuses on fossil fuel exposure rather than Copper World. The most cautious Mitsubishi analysts were only penciling in revenue of ¥19,909.1 billion and earnings of ¥1,068.0 billion by 2029, with a P/E of 12.7x. That is far more pessimistic than consensus, and those forecasts all came before this Copper World decision.
Explore 3 other Mitsubishi fair value estimates, including one that suggests as much as 43% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mitsubishi research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mitsubishi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mitsubishi's overall financial health at a glance.
Looking for more Mitsubishi investment ideas?
If the Copper World decision has sharpened your view on Mitsubishi, it can help to line that thesis up against other opportunities with different risk profiles, payout habits and balance sheet strength. A broad watchlist gives you more ways to respond when pricing or sentiment moves.
- For investors who care most about valuation support and quality fundamentals, scan a focused set of 14 high quality undervalued stocks that combine robust financial profiles with pricing that may not fully reflect those traits.
- If income is a priority, compare Mitsubishi's payout with a hand picked group of 28 dividend fortresses that concentrate on higher yields and more established distribution histories.
- For a steadier ride through different market conditions, widen your research to a 21 resilient stocks with low risk scores that screens for resilient earnings, lower risk scores and stronger balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com