


Dividend increase puts West Pharmaceutical Services in focus
West Pharmaceutical Services (WST) has approved a fourth quarter dividend of $0.26 per share, an increase of 18% from $0.22. This marks the thirty-fourth consecutive annual raise and puts its income profile in sharper focus for investors.
Recent trading has been strong for West Pharmaceutical Services, with a 1-month share price return of 8.76% and a year to date share price gain of 42.36% at a last close of $393.48. The 1-year total shareholder return of 42.49% suggests momentum has been robust in the shorter term but more muted over three and five years.
Scan other dividend-focused opportunities that emphasize reliable cash generation through our hand-picked list of 7 dividend fortresses
The dividend streak and strong recent share price run put West Pharmaceutical Services on a higher ledge. Does the current valuation still leave enough upside to justify fresh risk for new buyers?
Most Popular Narrative: 3% Undervalued
On Simply Wall St's central narrative, West Pharmaceutical Services screens as modestly undervalued, with a fair value of $405.38 compared with the last close at $393.48. That small gap rests on a view that earnings and margins can steadily improve from here.
The strategic focus on expanding the contract manufacturing business into drug handling, including a Dublin program expected to reach more than US$60 million of revenue at full ramp by around 2028 and targeted gross margins above 30% compared with mid to high teens today for West Vantage overall, could lift segment profitability and support group net margin and earnings as additional programs are added over time.
See why 14 investors see West Pharmaceutical Services as 3% undervalued.
Result: Fair Value of $405.38 (UNDERVALUED)
Still, West Pharmaceutical Services carries clear pressure points, from premium P/E expectations to execution risk in West Vantage if GLP 1 and drug handling uptake disappoints.
Find out about the key risks to this West Pharmaceutical Services narrative.
Another View: What Multiples Say About West Pharmaceutical Services
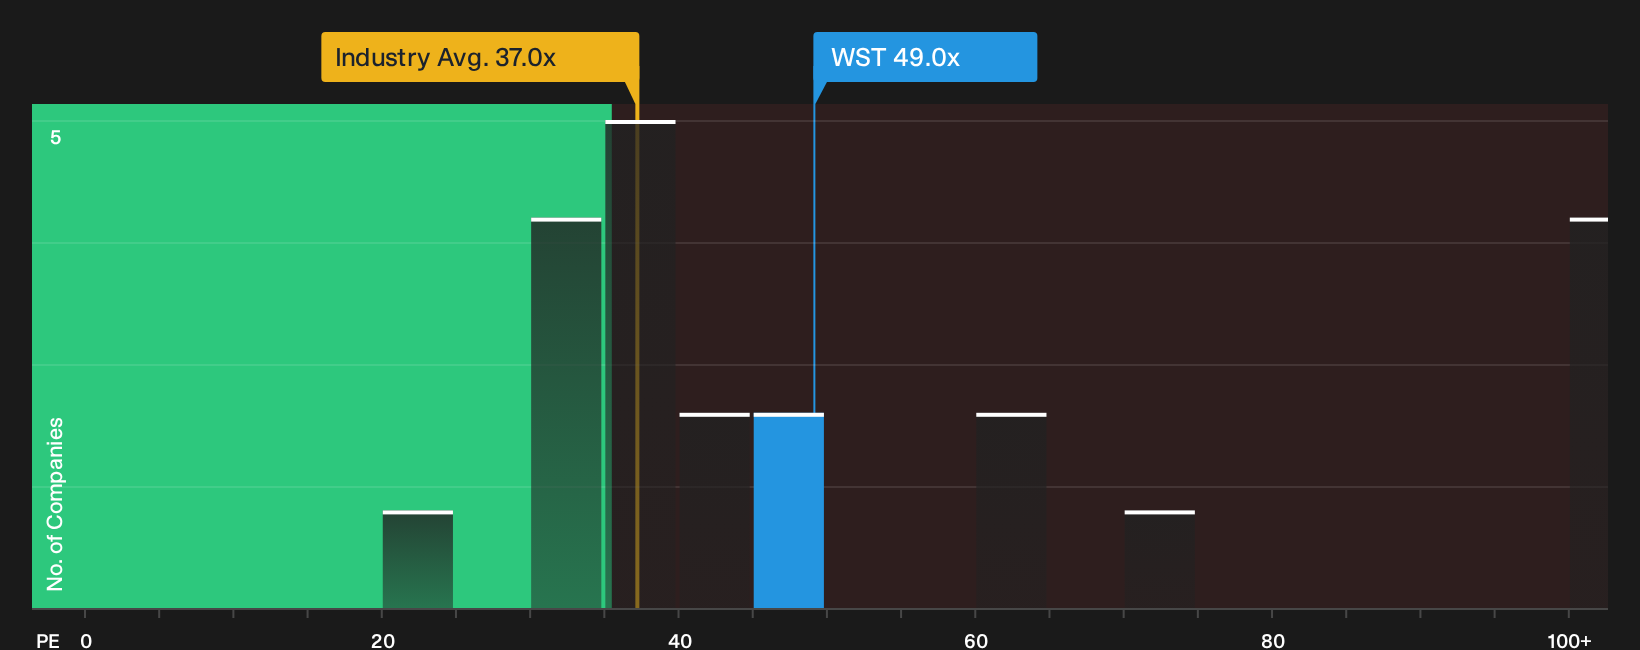
There is a catch. While Simply Wall St's central narrative tags West Pharmaceutical Services as around 3% undervalued, the current P/E of 49x is almost double the fair ratio of 24.7x and higher than both the Global Life Sciences average of 37.5x and a 48.9x peer average. That rich set of comparisons points to valuation risk rather than a clear bargain, so which signal do you trust more?
See what the numbers say about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown.
For an at a glance view of how the P/E stacks up against the wider market, take a look at the
Next Steps
If this mix of dividend strength and premium valuation has you on the fence, move quickly to check the underlying data yourself and shape your own view. Then size up the potential upside by reviewing the 2 key rewards.
Looking for more investment ideas beyond West Pharmaceutical Services?
Do not stop at one opportunity. Use targeted screeners to surface fresh ideas that match your risk tolerance and income goals before the next move passes you by.
- Spot potential mispricings early by reviewing a curated pool of quality candidates through the 33 high quality undervalued stocks.
- Reduce balance sheet surprises by focusing on businesses filtered for financial resilience via the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by scanning a focused pool of promising outliers with the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com