


With the development of fintech over the past 10 years, it has become possible to acquire customers, approve, and lend money online, and has gradually formed a huge chain of interests surrounding the credit business. However, under the recent downturn and compliance storm in the real estate industry, the industry is experiencing a turmoil in personnel and scale.
At a time when the industry is fluctuating, there are still companies that persevere in knocking on the door of the capital market. In mid-October 2026, Hong Kong mortgage brokerage service company FG Holdings Limited updated its IPO prospectus with the US Securities and Exchange Commission (SEC) to be listed on the NASDAQ under the stock code “FGO”.
According to information, FG Holdings Limited, as the listed entity, is a company registered in the BVI. It mainly conducts business in Hong Kong through operating subsidiaries Fundergo, RichestView, and FunderMall. Today, almost two years have passed since it first submitted its form to the SEC.
Credit intermediaries from Hong Kong
The Zhitong Finance App learned that Fundergo was founded in 2019 and is a financial service provider that mainly provides private credit mortgage brokerage services and bank mortgage loan brokerage services through fintech platforms in Hong Kong.
Benefiting from the rapid development of fintech in Hong Kong, many companies have moved their offline exhibitions online, and Fundergo is one of them. The company has successfully developed a flexible and efficient fintech platform connecting borrowers and lenders. Its online mortgage brokerage platform is designed to be secure and easy to use, has a bilingual user interface, enables quick execution through automated evaluation simulations, and provides an excellent user experience.
Based on this, the company uses expertise in the banking and financial industry, an extensive network of lenders, and advanced fintech platforms to provide borrowers with mortgage application simulations and various mortgage loan options from different lenders, match borrowers with the best loan options, and connect them with potentially suitable lenders, also known as “intermediary” services.
In addition to mortgage brokerage services, Fundergo also advises its clients through the Fundergo platform and assists corporate clients in determining restructuring plans and exploring potential financing options. According to the prospectus, from inception to September 30, 2026, the company has provided more than HK$11.531 billion in loans to 822 borrowers.
From a financial perspective, for the fiscal year ending June 30, 2026, the company's revenue was approximately HK$24.94 million, up 21.5% from HK$20.52 million the previous year; net profit increased from HK$6.432 million to approximately HK$7.6638 million, an increase of 20.7%, which is basically in line with the revenue growth rate.
In terms of revenue sources, the growth in the consulting services business is the backbone of the company's revenue growth. In fiscal year 2025, about HK$19.569 million increased to HK$23.23,300. As of the fiscal year 2025 and 2026, the Company provided loans to 49 and 56 advisory service borrowers, with a total loan amount of HK$1.94 billion and HK$1,043 million (approximately US$133 million), with average costs of 1.01% and 2.23% respectively.
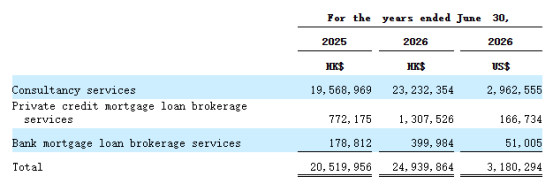
In terms of private credit mortgage brokerage services, the company refers businesses or individual borrowers seeking mortgage financing or refinancing to private credit institutions (including licensed lenders, family offices, and credit funds). Housing prices in the Hong Kong market have fluctuated greatly since 2024, but stabilized in 2026. However, private credit lenders remain cautious when issuing mortgages. As a result, Fundergo has adopted a flexible strategy to capture the market demand for private credit mortgage brokerage services and consulting services supported by pure real estate. Revenue from private credit mortgage brokerage services in Fundergo and Richest View increased 69.3% year over year.
On the profit side, in fiscal year 2026, the company's net interest rate fell slightly from 31.3% to 31.1%. Judging from the “paper” results alone, Fundergo's “small but beautiful” handed over a report card with decent growth quality: while revenue expanded, profit margins were not clearly eroded, and remained at a high level of more than 30%.
However, the profit side of the company diverged from cash flow: the cash flow from operating activities in fiscal year 2025 was a net inflow of HK$8.106 million, which basically matched the net profit of HK$6.432 million for the year, and was in a healthy state of “profit entry+cash support”. However, in fiscal year 2026, its operating cash flow suddenly turned into a net outflow of HK$2.125,100, while net profit for the same period was a high of about HK$7.7638 million. There is a large gap between net profit and operating cash flow, which means that profits earned on the company's books are not converted into real money cash inflows.
On closer inspection, this gap is mainly due to accounts receivable, which soared from HK$1.398,500 in FY2025 to HK$11.26 million in FY2026, achieving a huge increase in one year. For credit companies, accounts receivable are essentially unrecovered loan principal and interest, unsettled service fees, or advanced overdue bank payments, so the change in accounts receivable as a share of revenue is clearly worth paying attention to: accounts receivable in 2025 only accounted for 6.8% of that year's revenue, while in fiscal 2026, the ratio jumped to 45.15%.
Meanwhile, in the 2026 fiscal year, the company's sales expenses nearly doubled from about HK$3.96 million to about HK$7.503 million, and their share of revenue rose from 19.3% to 30.1%. Among them, agency fees surged by 2781.7% to HK$3.398,900 to be paid to third party agents. These agents recommended borrowers to participate in the company's private credit mortgage brokerage services and consulting services, but it may take time to test whether revenue growth can be sustainable by increasing sales investment in exchange.
The market is fiercely competitive, how to break through?
In recent years, as a bridgehead for the internationalization of China's financial industry, Hong Kong has always been a market where the financial industry is highly developed and continues to embrace technological innovation, which has spawned huge capital requirements and circulation markets. At the same time, as one of the most expensive and highly liquid real estate markets in the world, Hong Kong's mortgage business is secured by such fixed assets and has become one of the favorite loan products of investors and banks over the past ten years. However, in recent years, due to fluctuations in the economic environment and the decline in housing prices, the industry has also been hit to a certain extent.
In the midst of a volatile market, Fundergo's solution is to embrace a “technology” approach. In its prospectus, the company's unique feature is its ability to develop specialized technology, combine financial expertise, and embed these solutions into its own online platform. The company is one of the first pioneers in the mortgage brokerage industry to successfully establish a fintech platform that connects borrowers and banks quickly, flexibly, and simply.
With extensive data, artificial intelligence applications, and machine learning technology, Fundergo's online platform effectively provides online property valuations, instant risk and credit assessments, and accurate lender matching results. In August 2023, the company acquired iMort, and as part of the Fundermall acquisition, the project received the Hong Kong Fintech Promotion Awards 2022 Credit Digitalization - Mortgage Loans hosted by Metro Finance and KPMG.
However, on the other hand, Hong Kong already has a large number of existing mortgage brokerage services and consulting service participants, providing services similar to those of the company. Among them, there is no shortage of large competitors with better brand recognition and reputation in the market, a wider range of value-added services, stronger human and financial resources, a longer operating history, and more geographical regions. Furthermore, the industry threshold is low, and new players only need to hire qualified professionals and obtain the necessary regulatory licenses to enter the market. A competitive market creates an unfavorable pricing environment and may cause companies to lower service fees to compete with other market participants, which may put pressure on them to maintain their profitability.
Furthermore, it is easy to see that as of the 2025 and 2026 fiscal years, Fundergo's business was also mainly driven by a few key customers. In fiscal year 2025, the company's three major customers accounted for 26%, 12%, and 12% of total revenue, respectively. The company's three major customers accounted for 29%, 16%, and 8% of total revenue respectively in the 2026 fiscal year. This also means that over 50% of the company's revenue comes from limited customer sources, and the customer concentration is slightly higher.
In order to seek greater development, Fundergo plans to use this IPO financing to expand and diversify operations and product services; further consolidate its market position in the existing market and expand geographical coverage to overseas markets with the advantages of online platforms and overseas networks; and further invest in information technology to optimize online platforms.
However, the current concentration of the mortgage market in Hong Kong is not high, meaning that all participants can get a share of the pie. At a time when real estate is gradually stabilizing and demand for financing is gradually picking up, companies with first-mover advantages and customer resources may gain more market share.