


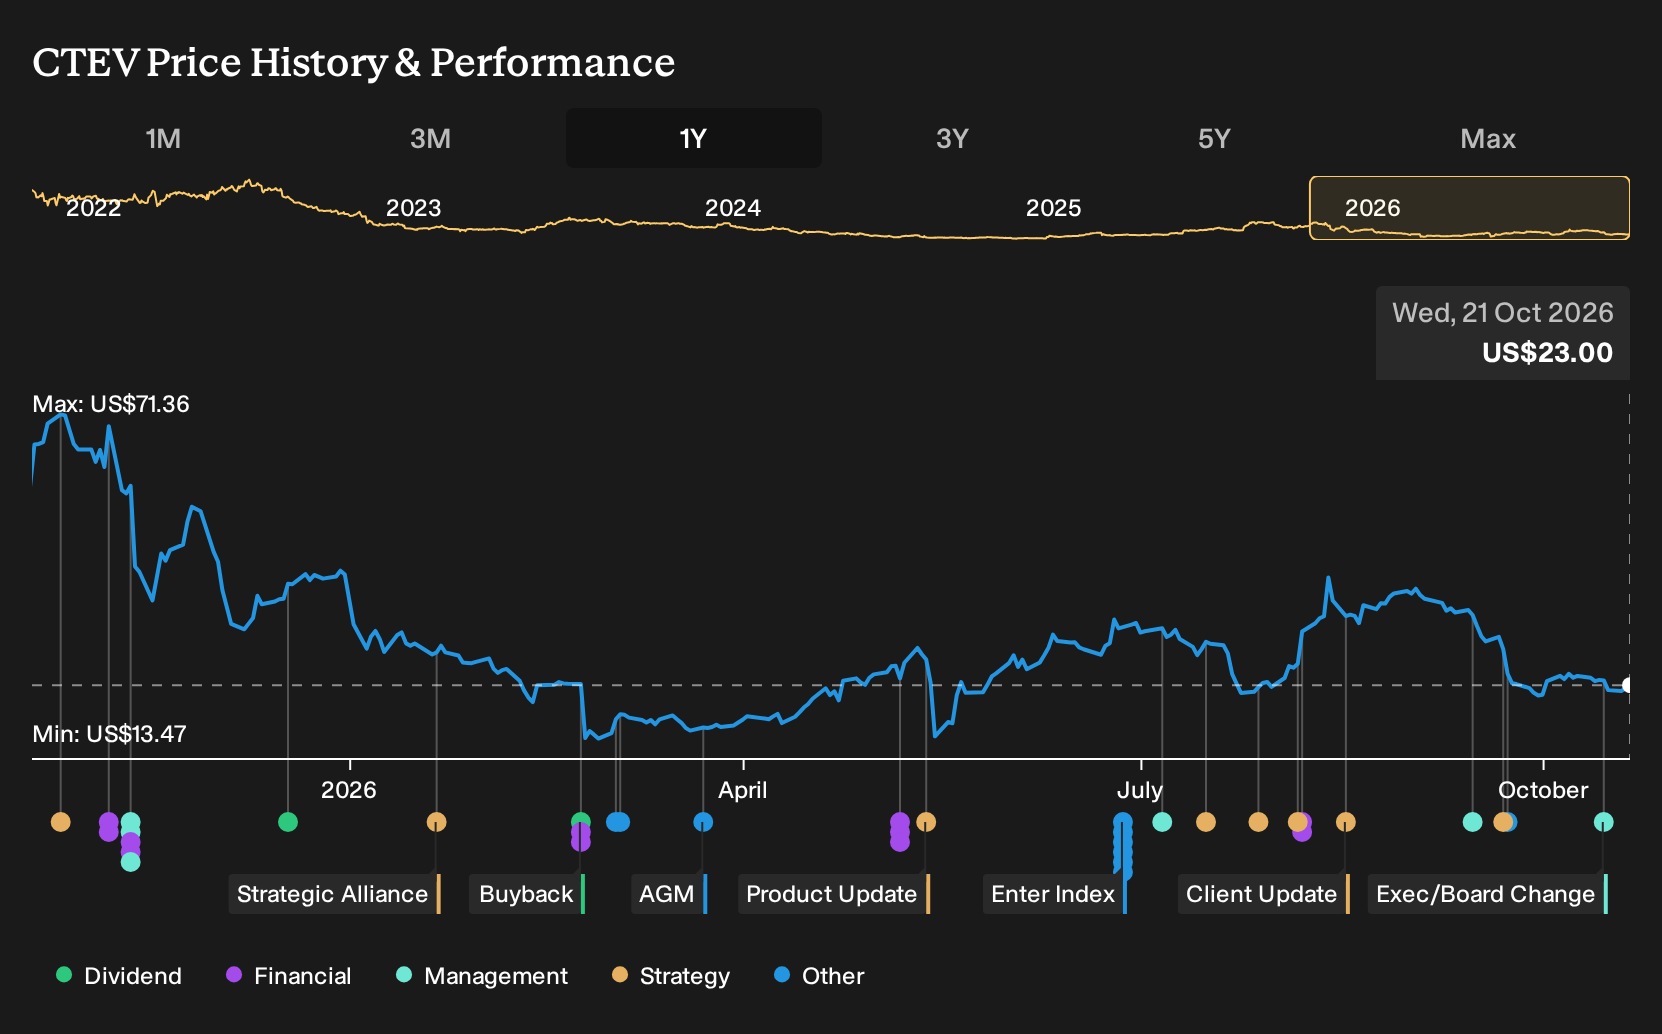
If you had looked at Claritev in October 2025 and decided it was too complicated to touch, skipping the stock might have felt overly cautious at the time. For Claritev shareholders, the loss over the past year was 65.2%, including dividends. With Q2 2026 showing higher revenue and a smaller loss on record, the real question is which assumptions in those 2025 bullish and bearish forecasts deserved more scrutiny before any decision.
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Claritev. Zero in on 33 high quality undervalued stocks for companies trading below our estimates.
The Two Claritev Stories Investors Had To Weigh
The shares cost US$66 at the start of the period, and Claritev investors had to choose between two sharply different but plausible stories about where the business might be heading.
The bullish narrative put Fair Value at US$70.5, based on the idea that AI adoption, new Oracle Cloud migration and international expansion could support 3.1% annual revenue growth and a shift toward an 8.8% profit margin over three years.
The bearish view set Fair Value at US$55, focused on rising regulatory and compliance costs and the risk that heavier data privacy rules might reduce Claritev's flexibility, while still assuming 3.4% yearly revenue growth and an 8.8% margin target.
What The Claritev Results Actually Tested
Claritev delivered Q2 2026 revenue of US$257.478m versus US$241.57m a year earlier and a smaller net loss of US$59.226m. The net margin remained negative, improving from 25.9% to 23.0%. That combination supported parts of the optimistic story on revenue and efficiency, while leaving the profitability target in both the bullish and cautious cases unproven.
The hinge assumption here was margin repair. When assessing another stock built on a “margin catch up” pitch, track whether revenue, absolute profit and the reported net margin all move in the same direction across several reports.
What Claritev’s Drop Is Asking You To Believe
Claritev now trades at US$23, after a 65.2% loss over the past year, while the selected Narrative’s Fair Value sits above the current price based on its own modelling rather than any settled fact.
The Narrative leans on multi-year contracts, pipeline growth and international expansion to support that stance. Anyone buying today would need to believe those commitments offset regulatory, cost and client concentration risks enough for the fall to look like mispricing rather than an early warning.
"Multi-year client renewals, pipeline growth, international expansion, tech investments, and regulatory changes are driving Claritev's improved revenue visibility, scalability, and long-term growth prospects."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking One Step Beyond Claritev
Claritev runs on software, data and long contracts. Your watchlist does not have to stop there.
Similar clients still need help managing health costs and complicated benefit rules. One large operator relies on care programs and data tools to support that work.
Instead of selling analytics alone, it runs clinics, care teams and pharmacy services. These operations use technology and value-based designs to keep treatment efficient.
If that model manages sicker patients more effectively over time, data-led care could evolve in ways beyond Claritev’s pure software approach.
One Narrative has already put a figure on it. → Uncover the company trading 13% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com