


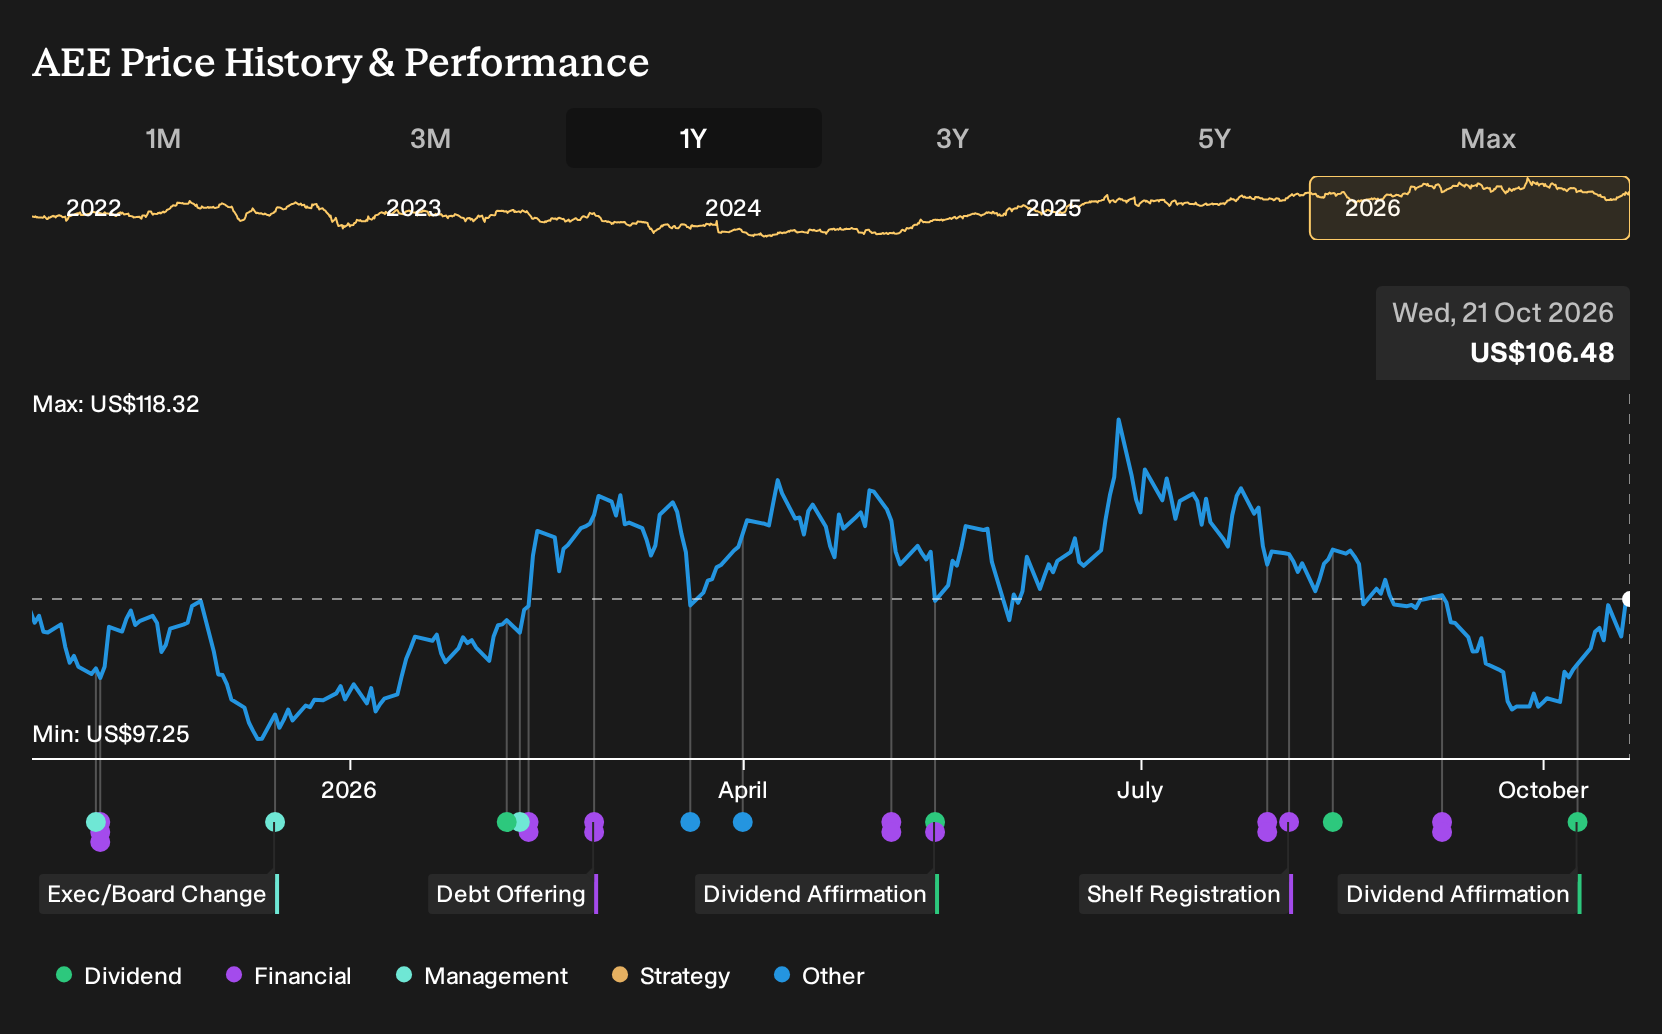
- Ameren's board declared a quarterly cash dividend of 75 cents per share on common stock, payable on December 31, 2026, to shareholders of record on December 8, 2026.
- Analysts see Ameren weighing a modest expected Q3 earnings shortfall against the potential expansion of its five-year capital plan by US$4 billion to US$6 billion, driven by projected data center related load growth.
- We will now explore how Ameren's potential US$4 billion to US$6 billion capital plan increase could reshape the investment narrative around its grid buildout.
Compare how Ameren's grid buildout theme aligns with other regulated utilities preparing for data center load by reviewing our curated 42 power grid technology and infrastructure stocks
Ameren Investment Narrative Recap
To own Ameren, you need to be comfortable with a regulated utility leaning into very large, long dated grid and generation projects tied to data center demand. The thesis rests on that load materializing broadly as planned, and on regulators continuing to support a bigger rate base. A modest Q3 earnings miss relative to expectations would not change that central equation much.
The more important near term swing factor is how Ameren updates its capital plan and long term guidance around data center driven demand on the upcoming Q3 call. The biggest risk stays the same. Hyperscale projects or key regulatory approvals could slip, creating a gap between a growing project pipeline and realized returns.
The dividend affirmation at 75 cents a share for December 2026 matters because it sits against a backdrop of heavy planned investment and flagged pressure on debt coverage and free cash flow. Management is signaling a willingness to keep returning cash to shareholders while it leans on external funding for the buildout.
For you as an investor, the key question is how that payout fits with a US$71b plus infrastructure program that already assumes sizeable equity issuance and higher borrowing. Any future shift in policy around the dividend, or in credit metrics, could quickly become a catalyst if data center timing, rate cases, or capital markets conditions do not cooperate.
How Ameren’s Forecasts Frame the Grid Buildout Bet
Ameren's narrative projects US$10.8b revenue and US$2.0b earnings by 2029, supported by analysts who assume 8.6% yearly revenue growth and an earnings increase of about US$400m from US$1.6b today.
Uncover why Ameren's fair value indicates a 10% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Fair value estimates for Ameren from 2 private investors in the Simply Wall St Community span roughly US$95 to US$117 per share, so you are looking at a wide personal skew on what the stock is worth. In addition, there is the risk that large data center projects or key approvals slip, so you have plenty of reason to compare several different viewpoints before deciding how much exposure feels sensible.
Explore another Ameren fair value estimate, including one that suggests potential upside of as much as 10% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Go with your instincts.
- A great starting point for your Ameren research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ameren. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ameren's overall financial health at a glance.
Looking For More Ideas Beyond Ameren?
If the Ameren story has you thinking about how to position your portfolio for different kinds of risk and income, it can help to scan a wider field of potential opportunities using the Simply Wall St Screener.
- Hunting for resilient balance sheets and steady fundamentals, especially in capital intensive sectors, starts with this curated list of solid balance sheet and fundamentals (25 results).
- If your priority is limiting downside rather than chasing maximum upside, use the focused 31 resilient stocks with low risk scores to see businesses with lower overall risk scores.
- For investors open to under-researched opportunities with strong underlying numbers, this targeted 21 high quality undiscovered gems can surface ideas you might not otherwise come across.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com