


Record high oil prices after renewed attacks on Middle Eastern energy infrastructure have pushed income back into the spotlight for many UK investors. Cash in the bank may feel safe, but inflation and higher rates mean the opportunity cost is rising fast. Growing British dividend payers with 2% to 5% yields offer a middle ground between low-yield defensives and high-risk high-yielders. This article profiles three of the strongest candidates.
The three stocks below are a small sample, and the full screen on Simply Wall St surfaced 8 more British dividend payers with similar income stories that are not covered here. To size up the full field of Type 2 dividend candidates and identify which payouts fit your portfolio goals, head straight into the Growing Dividend Payers with 2-5% yield screener
Grainger (LSE:GRI)
Grainger is a £1.33b landlord focused on designing, building and running rental homes across the UK. Its Private Rented Sector business, which produced about £164 million of revenue, is the main engine for recurring income, alongside £74 million from reversionary assets and smaller legacy activities.
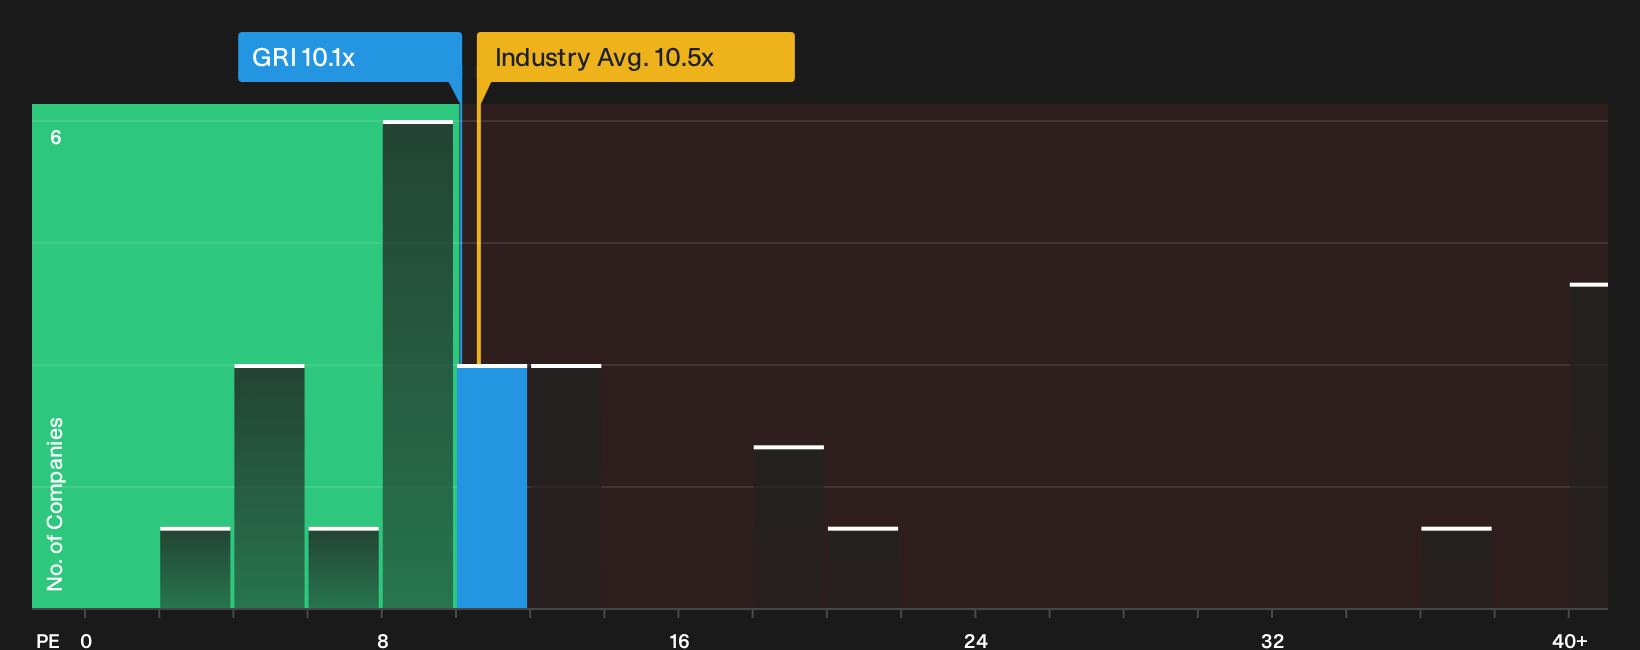
Grainger offers what many dividend investors look for in this screener: a roughly 4.7% yield, a UK build to rent portfolio generating recurring rent and a P/E of around 10x that sits close to its peer group. The key question is how that income profile holds up if one unseen pressure on its rental-driven cash flows shifts.
If that pressure point worries you, weigh it against the 5 key rewards and 2 important warning signs (1 is major!) that could reshape how you see Grainger’s income engine.
Cranswick (LSE:CWK)
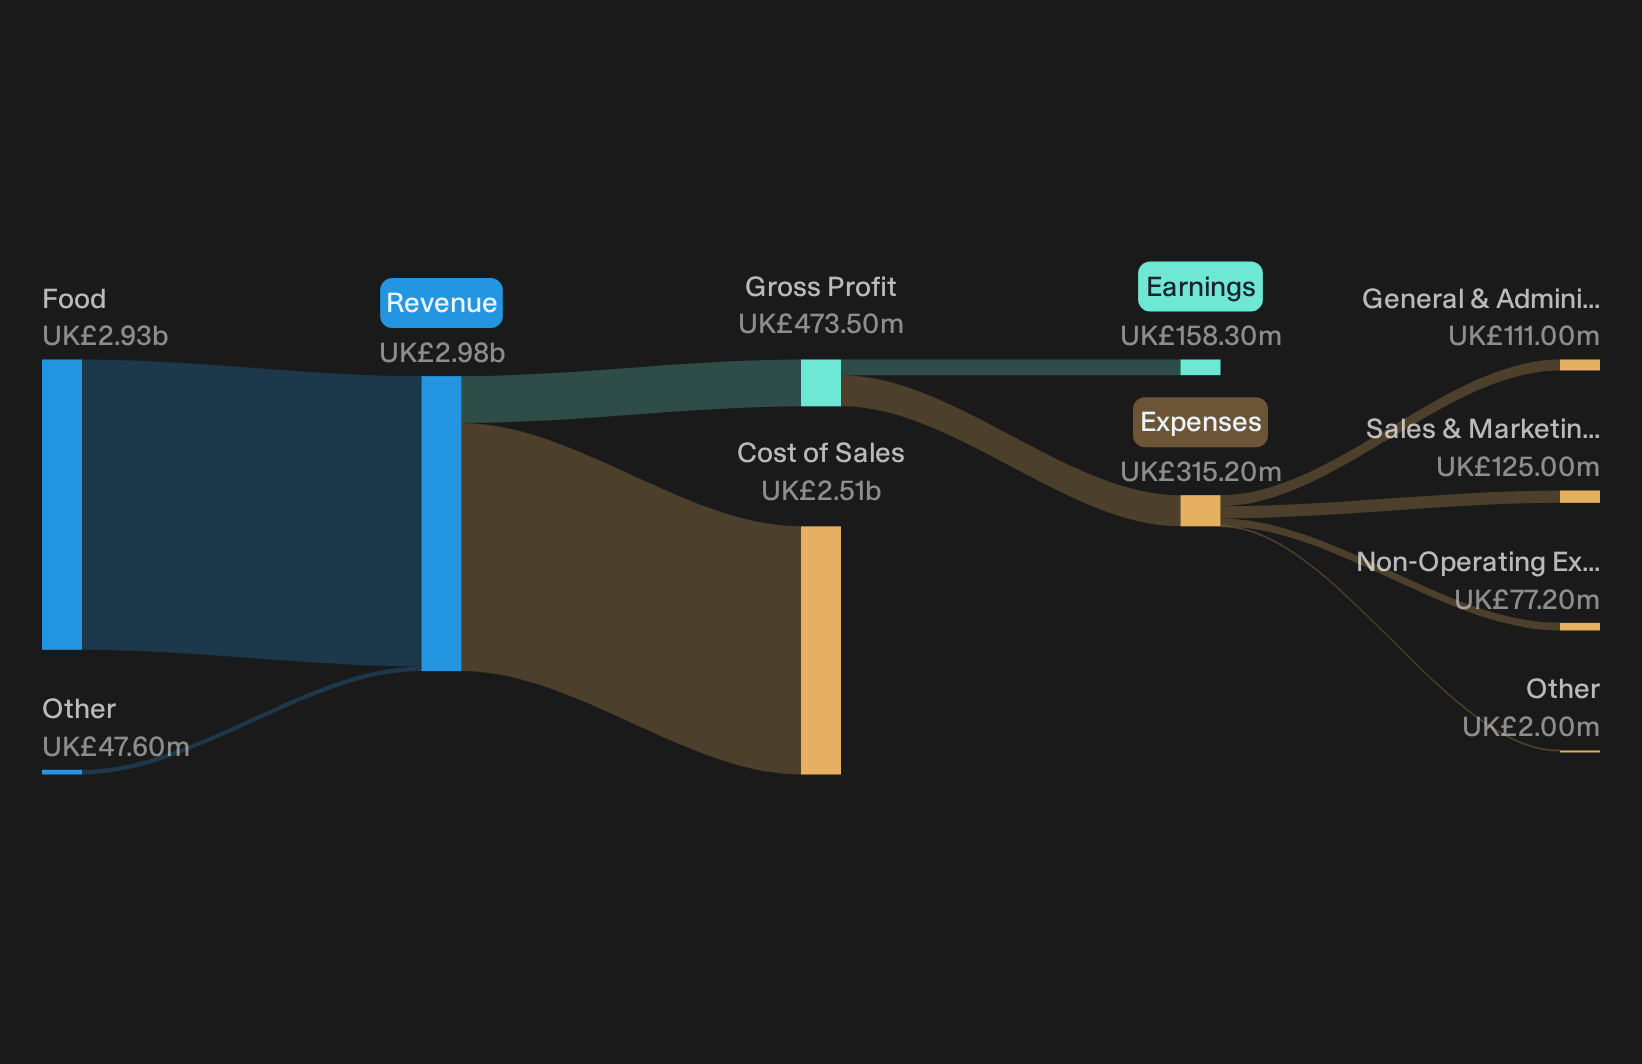
Cranswick is a £2.76b UK food producer best known for fresh pork, gourmet sausages and other processed meat supplied to supermarkets and foodservice customers, a cash-generative line that supports growing dividends. Its Food division produces about £2.93b of revenue, with smaller Other activities adding roughly £48 million.
For a Type 2 dividend profile, Cranswick offers a 2.18% yield backed by meat-focused manufacturing that has supported 18% recent earnings growth and a 9.6% annual pace over five years. That mix of steady income and mid-teens ROE looks appealing if one key pressure on input costs and pricing power stays contained.
If that cost pressure stays contained, the analysis report for Cranswick shows where Cranswick’s margins could still surprise income investors.
Games Workshop Group (LSE:GAW)
Games Workshop Group creates and sells Warhammer tabletop miniatures and games that generate steady cash flow, which helps support growing dividends within the 2% to 5% yield range. Its £626.8 million Core segment drives almost all income, with £32.9 million from Licensing, and the group is valued at about £5.6b.
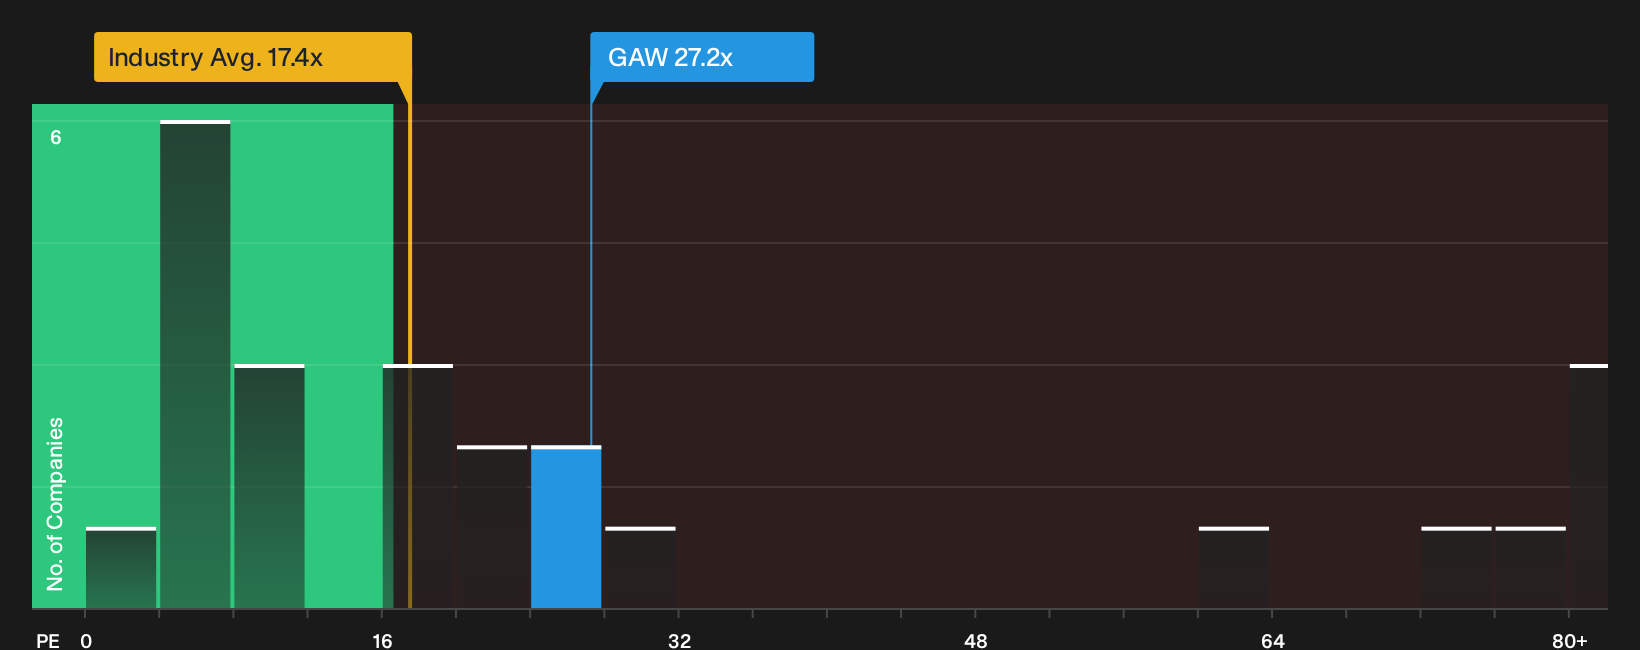
Games Workshop Group combines a 2.86% yield with a Warhammer franchise that has produced around 13.1% annual earnings growth over five years, a mix that fits the growing dividend payer theme. That income story depends on how one unseen pressure on its premium valuation resolves.
If you want to see how that valuation pressure could be resolving under the surface, go straight to the analyst forecasts for Games Workshop Group to read the full earnings story shaping expectations.
Seeking Alternatives Before Everyone Else?
Fresh ideas move first. Breakout stories pick up momentum, then get caught once the crowd arrives. Scan what is still under the radar for now and act now.
- Spot sturdier payouts while others chase headlines by running through a curated set of income stocks in the 4 dividend fortresses.
- Hunt for mispriced quality before it is flying on momentum by filtering through the 6 high quality undervalued stocks.
- Track real-world AI adoption instead of hype by scanning infrastructure enablers inside the 55 AI infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com