


Concentra Group Holdings Parent (CON) just added a new medical center near Reagan National Airport in Arlington, Virginia, widening its Washington, D.C. footprint and drawing investor attention to its occupational health footprint.
Recent trading has picked up. Concentra Group Holdings Parent has a 30-day share price return of 12.42% and a year-to-date share price return of 101.39%. The 1-year total shareholder return of 90.65% indicates momentum extending beyond the latest move.
Scan other healthcare operators showing similar expansion and pricing momentum using our hand picked list of solid balance sheet and fundamentals (25 results) to compare them with Concentra Group Holdings Parent.
Bulls see Concentra Group Holdings Parent turning that Arlington build out and recent 100% plus year to date run into proof of durable demand. Bears see overheating. Which story does the valuation currently lean toward?
Most Popular Narrative: 6% Undervalued
Concentra Group Holdings Parent closed at $39.09, while the most followed narrative pegs fair value at about $41.67. This implies a modest discount that is linked to steady clinic expansion and execution on efficiency plans.
Strategic acquisitions (Nova and Pivot) and de novo clinic expansion are actively increasing Concentra's national footprint and service capabilities, providing revenue growth through increased volumes and operational leverage. Full integration and synergy realization are expected to further improve EBITDA margins and overall earnings in coming quarters.
See why 3 investors see Concentra Group Holdings Parent as 6% undervalued.
Result: Fair Value of $41.67 (UNDERVALUED)
Still, the Concentra Group Holdings Parent story can break if high leverage keeps interest costs elevated, or if acquisition related expenses hold back margin improvement.
Find out about the key risks to this Concentra Group Holdings Parent narrative.
Another View: Concentra Group Holdings Parent Through A P/E Lens
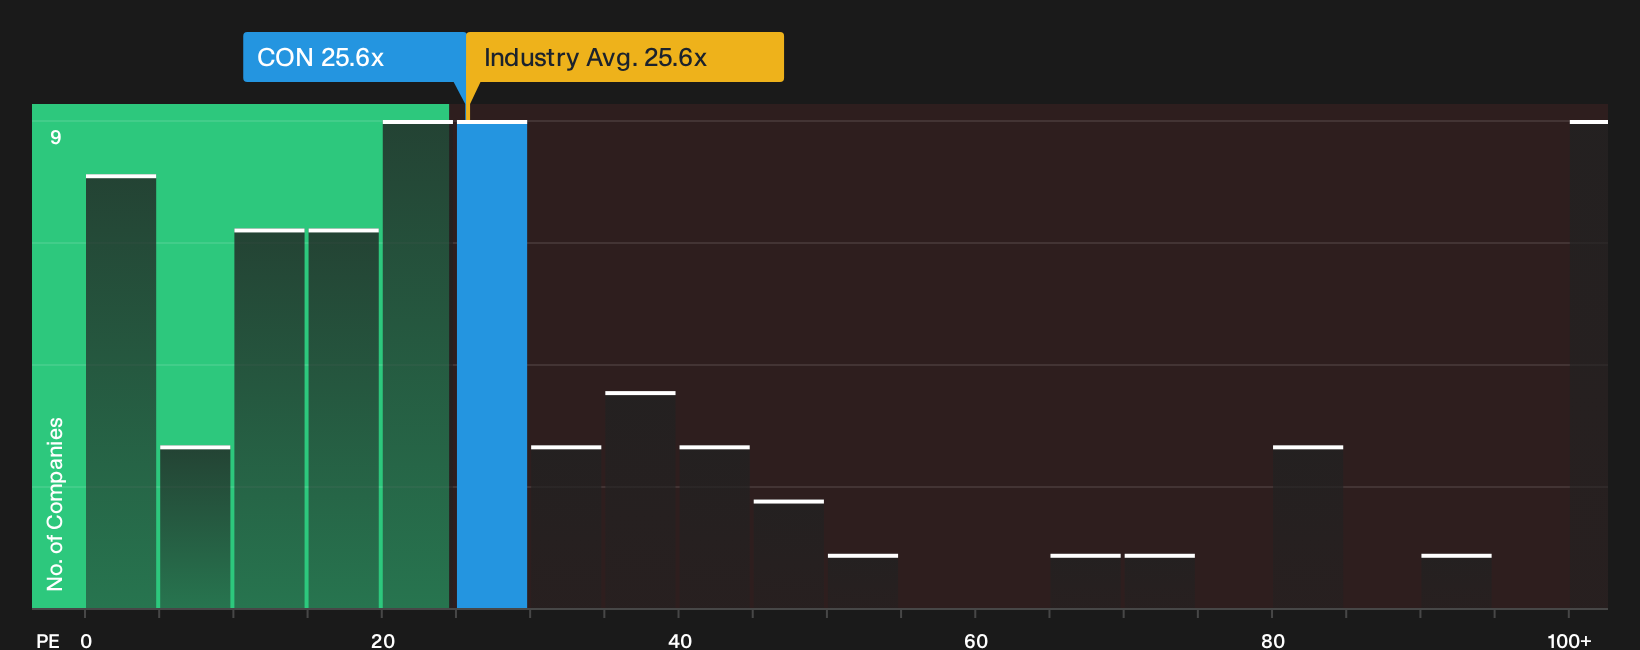
The first story casts Concentra Group Holdings Parent as about 6% undervalued. A simple P/E check tells something different. CON trades on 25.6x earnings, above its peer group at 21.8x and above its own fair ratio of 23.2x.
That gap points to investors already paying up for the recent 1-year share price run and earnings recovery, which reduces room for error if growth or margins soften. The question for you is whether this premium feels earned or fragile.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Momentum cuts both ways, and the mixed read on Concentra Group Holdings Parent means you should pressure test the story against your own risk and reward tolerance. To weigh the concern about at least one risk against the appeal of at least one potential upside, start with the 3 key rewards and 2 important warning signs.
Looking for more Concentra Group Holdings Parent investment ideas?
You do not need to stop your research with Concentra Group Holdings Parent. Broader opportunity sets often reveal better fits for your goals, risk appetite, and time horizon.
- Target income first and review companies built around reliable cash flows and robust payouts with the 7 dividend fortresses.
- Hunt for mispriced potential by scanning the 21 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Dial back portfolio stress and filter for resilience using the 31 resilient stocks with low risk scores before the next round of headlines hits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com