


- Halozyme Therapeutics has seen analyst consensus EPS estimates for the current year raised by 10.2% over the past three months, alongside a Zacks Rank #1 rating that reflects stronger expectations for its earnings power.
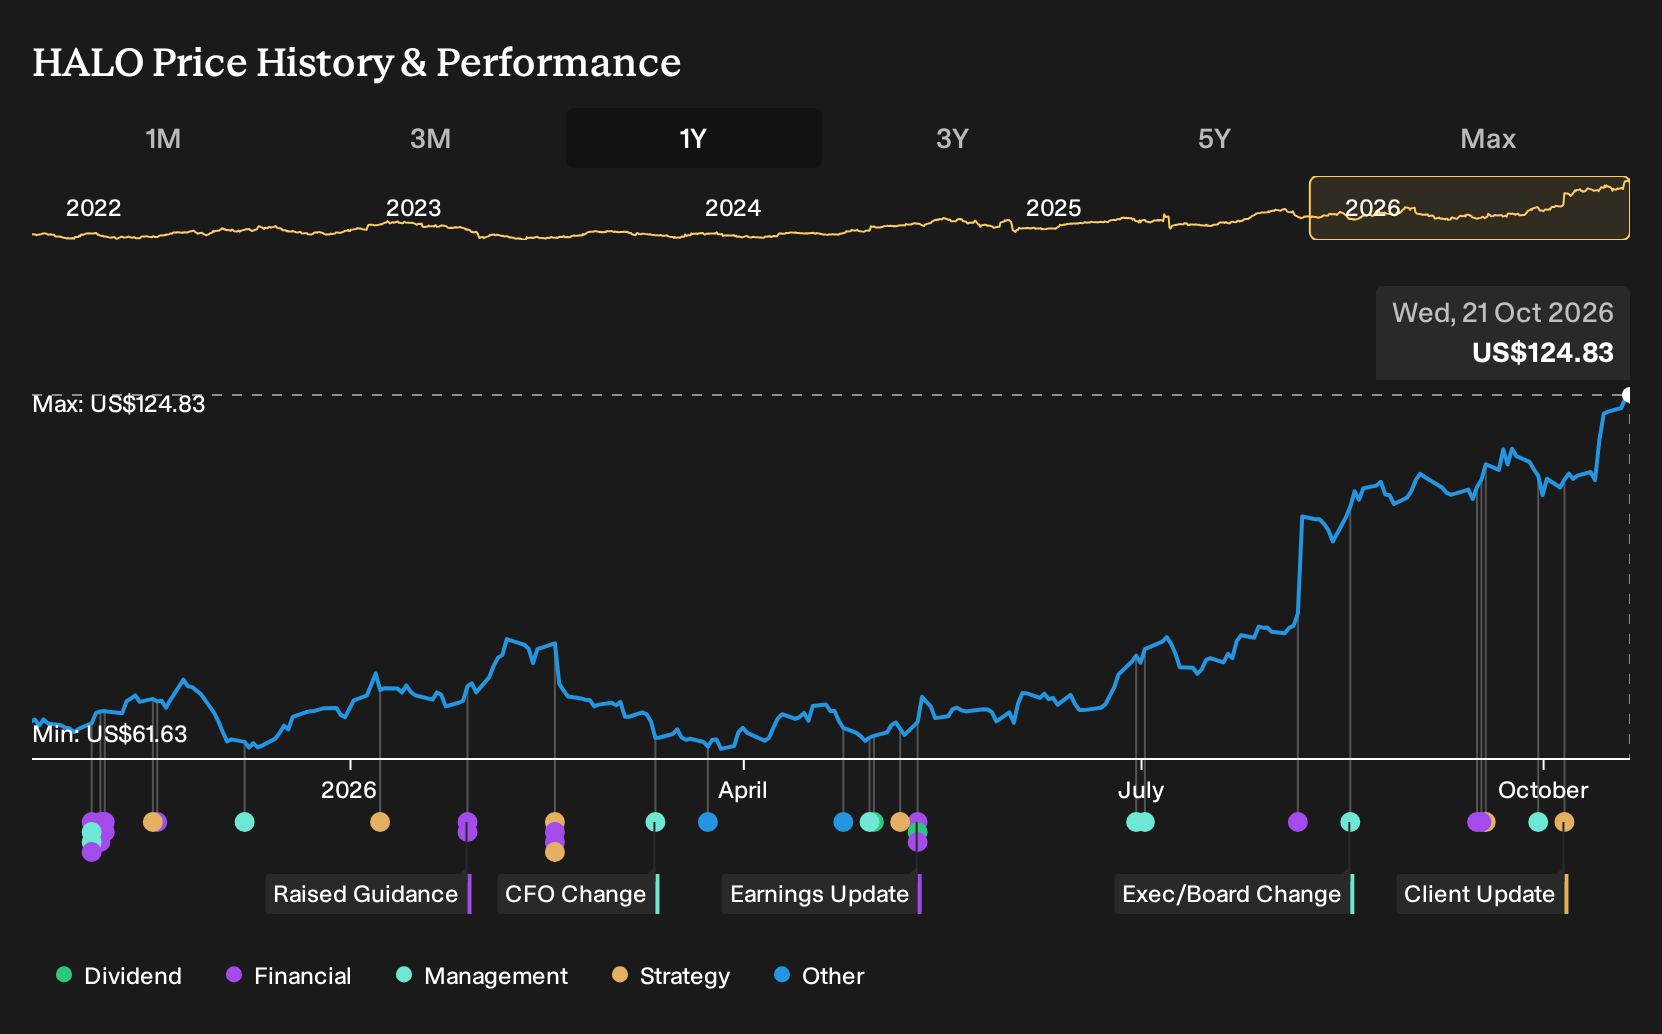
- The sharp 82% year to date return coincides with this upgrade to profit expectations, which highlights how investors are focusing on Halozyme Therapeutics' earnings model and cash generation potential rather than short term trading factors.
- We will now look at how Halozyme Therapeutics' investment narrative could be shaped by this upgrade in consensus earnings expectations.
Scan for other earnings driven opportunities that are moving in step with analyst upgrades by reviewing the hand picked 21 high quality undiscovered gems that share Halozyme Therapeutics' improving sentiment profile.
Halozyme Therapeutics Investment Narrative Recap
To own Halozyme Therapeutics, you need to be comfortable with a licensing model that leans heavily on partners adopting subcutaneous and at home biologic delivery. The big near term swing factor is how quickly ENHANZE based products and newer formulation platforms like Hypercon and Surf Bio translate into larger royalty streams. The sharp move in the share price and stronger earnings expectations do not change that core requirement.
The biggest operational risk is that pricing pressure, regulation or rival subcutaneous technologies slow new agreements or squeeze royalty economics. Recent margin compression, one off items and a meaningful debt load already show how earnings and cash generation can be sensitive if operating efficiency or deal flow stalls.
The recent upgrade to Halozyme Therapeutics earnings expectations ties back to the same driver that underpins the story. Partners are scaling products such as Ocrevus Zunovo and other ENHANZE launches that support demand for subcutaneous delivery and at home treatment. That operating backdrop is what investors are effectively underwriting when they look past short term volatility in reported margins.
Those adoption trends sit alongside a broader build out of royalty platforms, with ten approved ENHANZE products and multiple collaboration and license deals that include long royalty tails. For catalysts, investors will likely focus on how the company executes on Hypercon and Surf Bio programs, delivers partner label expansions like Darzalex and VYVGART, and manages regulatory and competitive risks that could slow the royalty machine.
Halozyme Therapeutics' current narrative rests on analysts expecting revenue to reach US$2.3b and earnings to be US$1.2b by 2029. That outlook assumes 10.6% yearly revenue growth and an earnings increase of about US$786.4m from the US$413.6m reported today.
Uncover why Halozyme Therapeutics' fair value indicates a 13% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate view on Halozyme Therapeutics emphasizes competitive risk from ALT B4. Those analysts were already penciling in about US$2.3b of revenue and US$1.3b of earnings by 2029, yet they paired that with a much lower US$78.0 target. That mix shows how sharply opinions can diverge, so explore several viewpoints as this new earnings news beds in.
Explore 4 other Halozyme Therapeutics fair value estimates, including one that suggests up to 13% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Halozyme Therapeutics research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Halozyme Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Halozyme Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Halozyme Therapeutics?
Once you have a view on Halozyme Therapeutics, it can help to cross check that conviction against other opportunities that fit different risk and income profiles. Use the Simply Wall St screener to cast a wider net and see how Halozyme compares with companies that share some of the traits you care about most.
- If you want steadier balance sheets and room to sleep at night, scan a list of solid balance sheet and fundamentals (25 results) and see how they stack up on debt and liquidity.
- For those hunting for potential value gaps, review a 33 high quality undervalued stocks that screens for quality fundamentals at prices analysts see as discounted.
- If income is a priority, weigh Halozyme against a 7 dividend fortresses that focus on companies with higher yields and robust payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com