


Church & Dwight (CHD) is back in focus after its recent share performance, with the stock closing at $105. Investors are weighing that move against the company’s measured revenue and net income trends.
That recent slip in Church & Dwight’s share price of 0.91% over the last session comes after a brisk 30-day share price return of 9.96% and a year-to-date gain of 27.06%, while the 1-year total shareholder return of 20.70% points to momentum that has been building rather than fading.
Scan how Church & Dwight’s recent momentum compares with other resilient consumer stocks by reviewing our hand picked 31 resilient stocks with low risk scores in one place.
After a run like this, Church & Dwight now sits close to analyst targets while still screening at a sizeable intrinsic discount. Has the recent rally already captured most of the upside, or does the valuation still leave room ahead?
Most Popular Narrative: 10% Undervalued
On the most followed narrative, Church & Dwight screens at a fair value of about $105, essentially in line with the latest $105 close once you factor in the 7.24% discount rate used to bring those future cash flows back to today.
The main thing that has to go right is that Church & Dwight continues to turn its power brands, new product launches and acquisitions like THERABREATH, HERO and Miss Mouth’s into higher household penetration, international reach and sustained category share gains, while keeping SG&A and input cost pressures under control.
See why 13 investors see Church & Dwight as 0% undervalued.
Result: Fair Value of $105 (UNDERVALUED)
Still, the Church & Dwight narrative can wobble if SG&A stays elevated or if the weak vitamins business continues to drag on margins and cash generation.
Find out about the key risks to this Church & Dwight narrative.
Another View On Church & Dwight’s Valuation
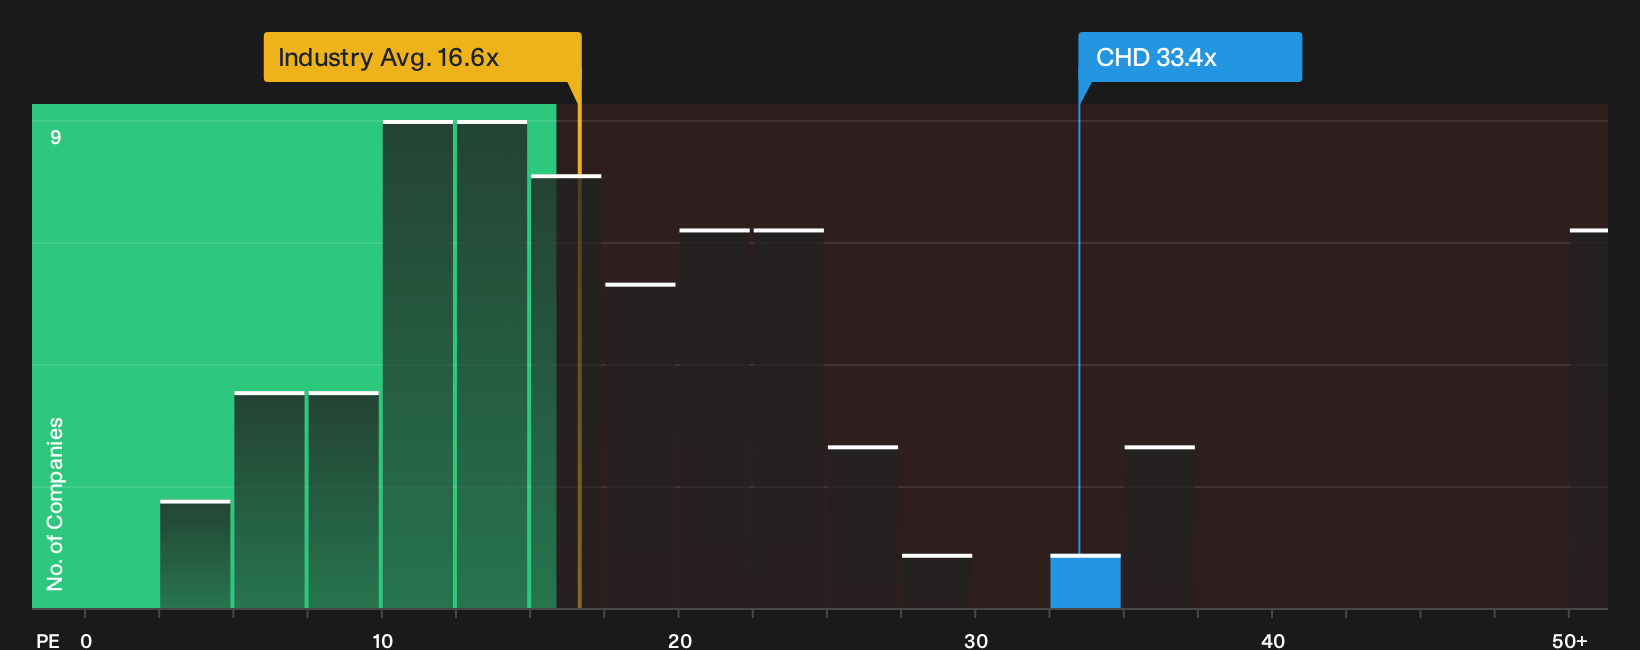
That 21% discount to fair value from the SWS DCF model points in one direction. The P/E tells a very different story. Church & Dwight trades at 33.4x earnings versus 22.2x for peers, 16.7x for the wider household products group, and a fair ratio of 19.6x that the market could move toward. If sentiment cools, how comfortable are you owning a stock where the cash flow model signals upside but the market multiple already prices in a premium?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Church & Dwight so far. Act while the data is fresh and compare the bullish and cautious angles side by side with 3 key rewards and 1 important warning sign
Looking for more Church & Dwight sized investment ideas?
If Church & Dwight has you thinking harder about pricing power and resilience, do not stop here. Broader opportunities are only a few smart filters away.
- Target steady compounders by scanning a 7 dividend fortresses built around higher yields paired with business models that aim to keep those payouts coming.
- Hunt for mispriced quality through a 33 high quality undervalued stocks that highlights businesses where fundamentals and current pricing do not fully line up.
- Zero in on financial strength using a list of solid balance sheet and fundamentals (25 results) that spotlights companies with cleaner balance sheets and sturdier core metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com