


Wyndham Hotels & Resorts (WH) just released third quarter results that mixed higher revenue with lower profit, while keeping full year revenue guidance unchanged, a combination that can sharpen investor focus on margins.
The mixed earnings update has arrived alongside a sharp rebound in Wyndham Hotels & Resorts’ market performance, with a 16.69% 1 month share price return and a 7.95% 7 day gain, suggesting improving momentum after a quieter year to date.
Scan how Wyndham Hotels & Resorts stacks up against other potential rebound stories by reviewing a curated set of 33 high quality undervalued stocks that also pair cash generation with balance sheet strength.
After a near 17% rebound in a month, Wyndham Hotels & Resorts still trades at a double digit discount to both analyst targets and intrinsic value estimates. Is that a genuine opportunity, or a signal the market remains wary of its margin story?
Most Popular Narrative: 20% Undervalued
Wyndham Hotels & Resorts closed at $78.36 against a narrative fair value of roughly $97.59, which puts the current rebound in a sharper light for anyone weighing upside against margin questions.
Record net room growth and a development pipeline of about 261,000 rooms with roughly a 30% FeePAR premium over the current system create ongoing mix uplift toward higher fee hotels, which can support faster growth in fee-related revenue and EBITDA for Wyndham Hotels & Resorts.
See why 2 investors see Wyndham Hotels & Resorts as 20% undervalued.
Result: Fair Value of $97.59 (UNDERVALUED)
Still, the bullish Wyndham Hotels & Resorts story can unravel if legal and reputational issues escalate, or if franchise partners underinvest in service and brand standards.
Find out about the key risks to this Wyndham Hotels & Resorts narrative.
Another View: Wyndham Hotels & Resorts Through The P/E Lens
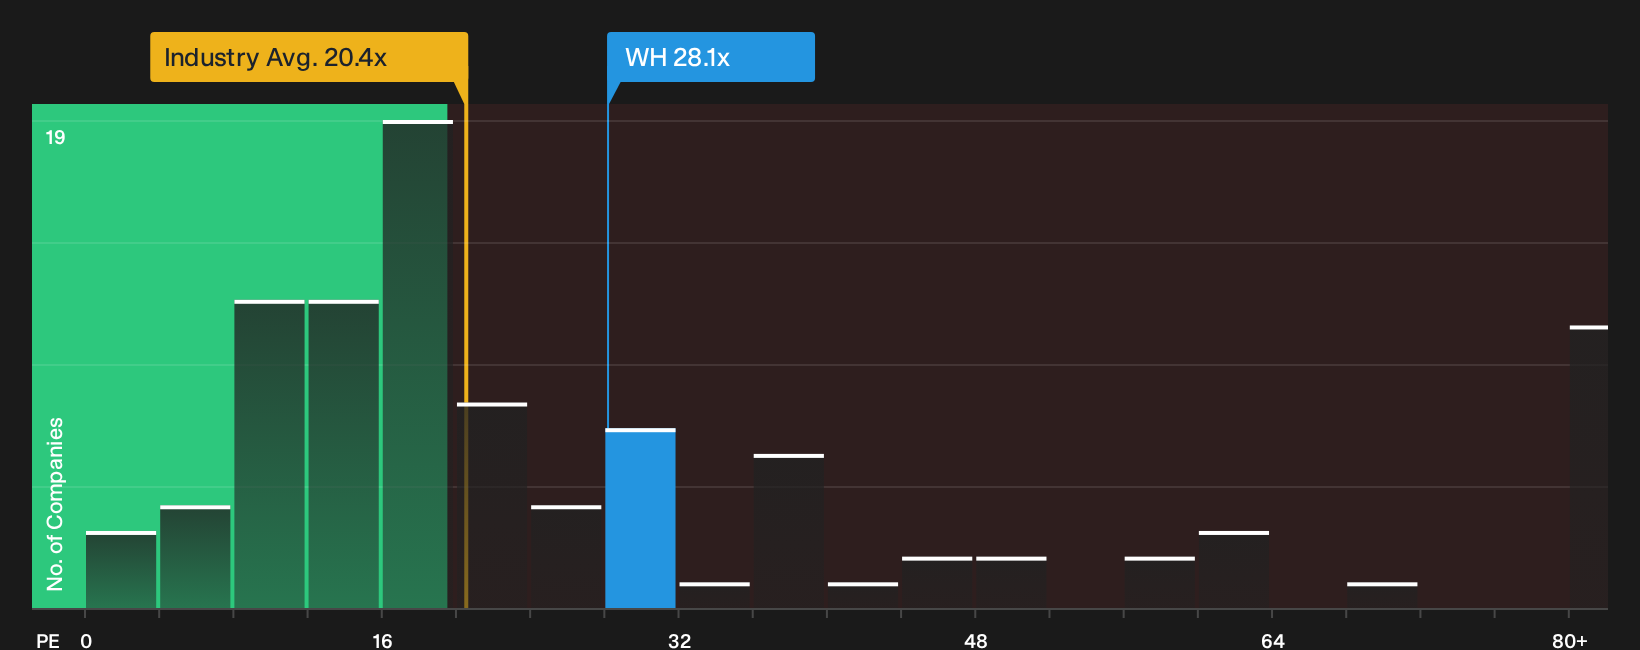
On a cash flow basis Wyndham Hotels & Resorts screens as undervalued, yet its 28.1x P/E is richer than both the US Hospitality industry at 20.7x and an estimated fair ratio of 21x. That premium narrows the margin of safety. Which signal do you treat as more important?
To stress test that earnings multiple against the underlying assumptions, take a closer look at how the valuation stacks up across peers and the fair ratio in our breakdown, then see what the numbers say about this price with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Wyndham Hotels & Resorts so far. Act while sentiment is split and review both sides of the story with 3 key rewards and 4 important warning signs
Looking For More Investment Ideas Beyond Wyndham Hotels & Resorts?
If you only stop at Wyndham Hotels & Resorts, you risk missing other opportunities where quality, income, or mispricing could tilt the odds in your favor.
- Target reliable income streams by reviewing 7 dividend fortresses that focus on higher yields backed by robust underlying fundamentals.
- Hunt for mispriced quality and compare Wyndham Hotels & Resorts with a curated pool of 33 high quality undervalued stocks that balance earnings power with disciplined capital use.
- Prioritize resilience first and scan 31 resilient stocks with low risk scores built around companies with steadier financial profiles and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com