


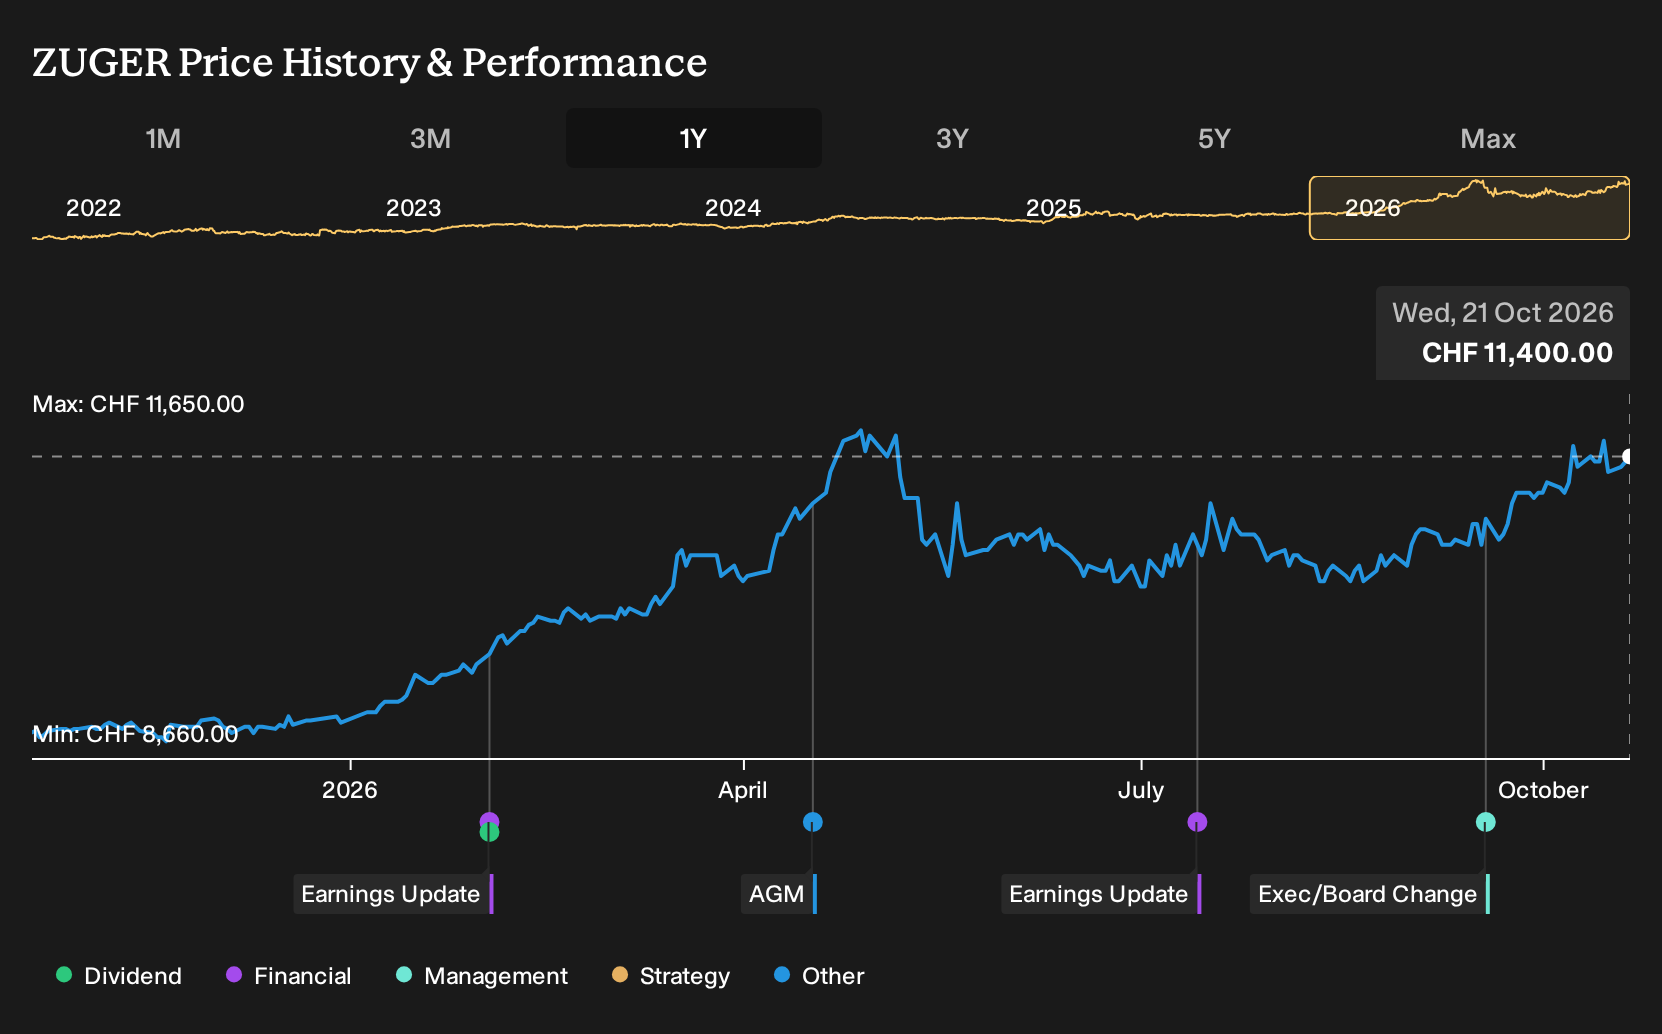
- Zuger Kantonalbank has almost doubled shareholder value over the past five years, which has prompted closer attention to how effectively its balance sheet and local franchise translate into lending and fee income.
- Investors are now examining whether the bank's returns on shareholder capital align with the current valuation, as excess returns modeling indicates a materially lower intrinsic value than the prevailing share price.
- We will now explore how Zuger Kantonalbank's investment narrative is being reframed by growing scrutiny of its returns on shareholder capital.
What Is Zuger Kantonalbank's Investment Narrative?
To stay on board with Zuger Kantonalbank at today’s valuation, you need to believe the regional franchise can keep turning a relatively simple balance sheet into solid fee and interest income without stretching risk. The recent focus on excess returns and an intrinsic value estimate below the CHF11,400 share price does not change near term operational drivers. Those still hinge on disciplined lending, stable deposit funding, and an efficient cost base in a fairly traditional Swiss banking model.
Short term, the key question is whether Zuger Kantonalbank can keep earning enough on shareholder capital to justify a P/E of 24.9x while Return on Equity sits at 8.1%. A reliable 2.02% dividend and high quality earnings support the case, although earnings declined 1.4% last year and bad loan coverage of 66% leaves less of a cushion if credit costs rise.
That said, there is a more awkward wrinkle once you look closely at how that low bad loan allowance interacts with ...
There's only one way to know the right time to buy, sell or hold Zuger Kantonalbank. Head to Simply Wall St's company report for the latest analysis of Zuger Kantonalbank's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Zuger Kantonalbank research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Zuger Kantonalbank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zuger Kantonalbank's overall financial health at a glance.
Looking For More Investment Ideas Beyond Zuger Kantonalbank?
If you want to stress test your view on Zuger Kantonalbank, compare it with other companies that have different balance sheet strength, dividend profiles, and valuation setups using the Simply Wall St Screener.
- Prioritise resilience first and see which companies clear a high bar on stability by screening a 227 resilient stocks with low risk scores.
- If reliable income matters most to you, scan for potential cash return candidates with a 222 dividend fortresses.
- For those hunting for less crowded stories with robust fundamentals, cast a wider net across a 618 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com