


AdMob integration puts JOYY’s BIGO Ads in focus
JOYY (NasdaqGS:JOYY) just pushed its advertising reach wider, as BIGO Ads made its SDK generally available through Google AdMob mediation, opening more formats and in-app bidding access for mobile publishers.
Investors have already been rewarding JOYY for execution in its broader social and advertising ecosystem, with the share price delivering a 90 day share price return of 16.5% and a year to date share price return of 30.6%. The 1 year total shareholder return of 55.8% and 3 year total shareholder return above 150% point to strong longer term momentum, and this AdMob integration now feeds into the story around growth potential and perceived risk.
Capitalize on JOYY's advertising momentum by scanning a curated group of 21 high quality undiscovered gems that could be building similar under-the-radar growth stories in adjacent digital media and engagement niches.JOYY now trades only a touch below the average analyst target, yet well above one estimate of intrinsic value that implies a steep discount. Which reference point deserves more weight after this AdMob driven re-rating?
Most Popular Narrative: 4% Undervalued
On the most followed view, JOYY screens modestly cheap, with a fair value estimate of $88.01 against the last close at $84.56, and that gap now has to be weighed against the fresh AdMob momentum and ongoing BIGO Ads traction.
The analysts have a consensus price target of $88.01 for JOYY based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $2.9 billion, earnings will come to $252.5 million, and it would be trading on a PE ratio of 19.3x, assuming you use a discount rate of 8.5%.
See why 5 investors see JOYY as 4% undervalued.
Result: Fair Value of $88.01 (UNDERVALUED)
Still, JOYY’s story can change quickly if compliance costs rise in key regions or if heavyweight rivals squeeze its pricing power in entertainment and ad tech.
Find out about the key risks to this JOYY narrative.
Another View: JOYY and the cash flow gap
The SWS DCF model paints a very different picture for JOYY. On that framework, the stock at $84.56 sits above an estimated future cash flow value of $62.66, which screens as overvalued rather than modestly cheap. Which yardstick do you treat as your anchor?
Look into how the SWS DCF model arrives at its fair value.
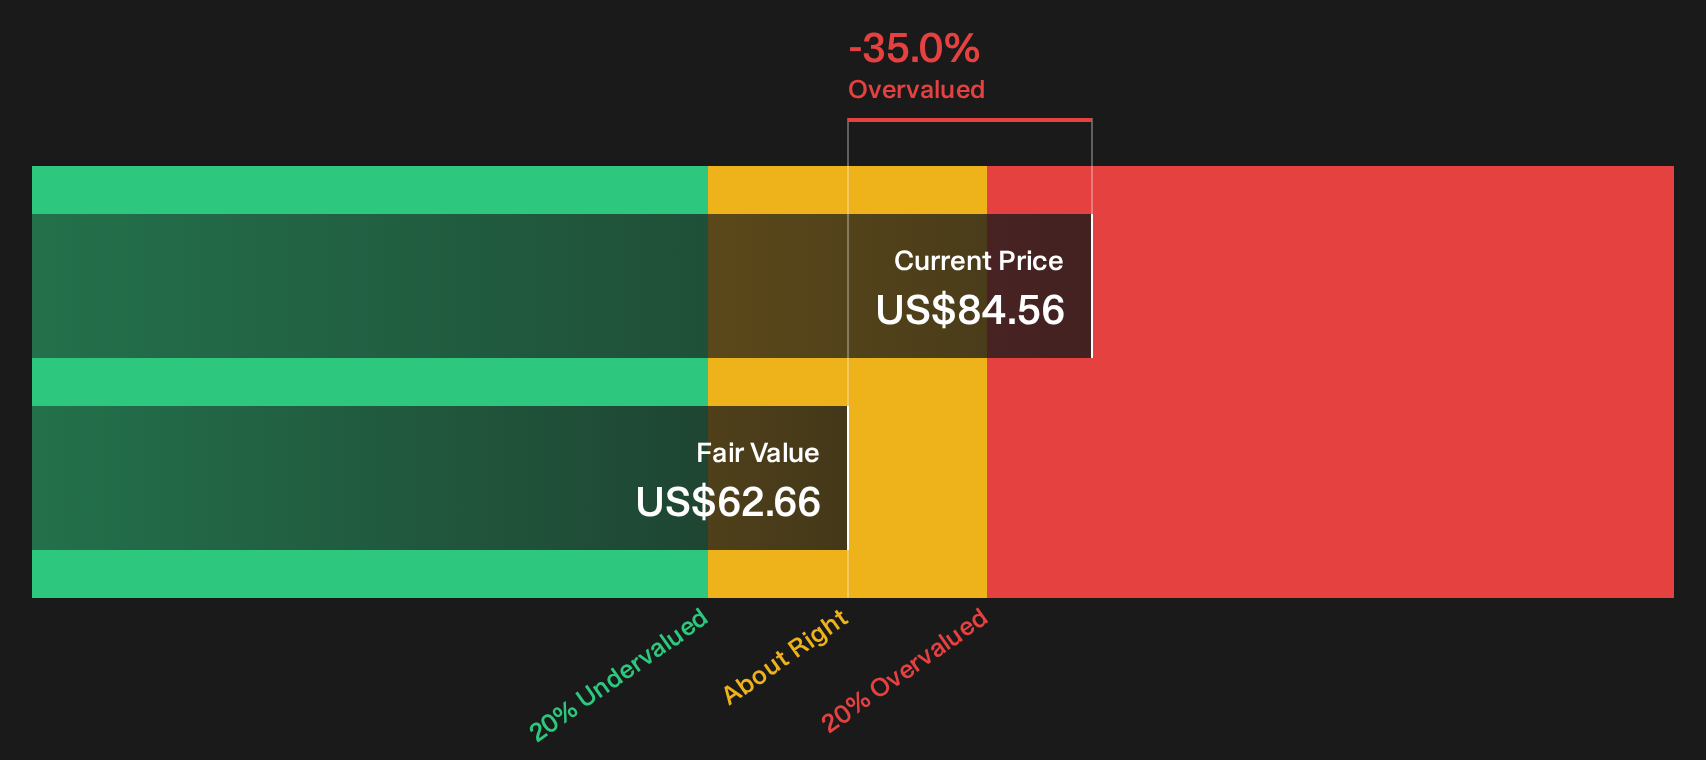
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out JOYY for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around JOYY’s value and risk profile are exactly why you should move quickly, review the underlying assumptions yourself, and weigh both the upside and the weak spots highlighted in the 1 key reward and 1 important warning sign.
Looking for more JOYY sized ideas?
If JOYY has your attention, do not stop here. Broaden your watchlist with other clear setups that could sharpen your overall portfolio mix.
- Target potential mispricing by scanning a focused group of 33 high quality undervalued stocks that pair solid fundamentals with compressed expectations.
- Strengthen your income stream by reviewing 7 dividend fortresses built around companies offering high yields with a focus on durability.
- Cut portfolio stress by concentrating on 31 resilient stocks with low risk scores selected for resilient balance sheets and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com