


- Lloyds Banking Group reported third quarter 2026 net interest income of £3,828m and net income of £1,666m, with basic earnings per share of £0.026 from continuing operations.
- The update also showed nine month 2026 net interest income of £11,106m and net income of £4,789m, giving earnings per share of £0.074, which helps investors weigh the scale of Lloyds Banking Group's lending and profitability profile.
- The next consideration is how Lloyds Banking Group's latest earnings run rate, especially net income, interacts with the existing long term investment narrative.
Scan how Lloyds Banking Group's latest board moves and earnings stack up against a curated set of peers by reviewing 4 resilient stocks with low risk scores, which is built to highlight resilience and disciplined risk profiles.
Lloyds Banking Group Investment Narrative Recap
To stay invested in Lloyds Banking Group, you need to back the idea that its UK focused banking, insurance and pensions franchise can keep turning solid net interest income and fee streams into stable earnings, even with tight mortgage and deposit competition. The near term swing factor is how credit quality holds up if UK growth or employment soften, which could pressure that earnings base.
The fresh non executive appointments are unlikely to change the short term earnings catalyst on their own. They matter more for how confidently Lloyds Banking Group can deliver the Accelerate 2030 cost and digital plans while managing risks around AI execution, bad loan coverage at 47% allowance and an already competitive P/E.
The most relevant update here is the appointment of Nigel Hinshelwood and Chris Rhodes to the Lloyds Banking Group board and key risk, audit and remuneration committees from 1 November 2026. Both bring long UK banking and risk oversight experience, which feeds directly into how the group manages tight mortgage spreads, deposit pricing pressure and capital decisions.
For you, this ties into the main catalysts and risks. The Accelerate 2030 programme relies heavily on AI, digital spend above £13b from 2027 and targeted £2b gross cost savings. Board members with deep operational and risk backgrounds can help scrutinise those projects, oversee credit standards in a modest growth UK economy and balance dividend, buyback and investment choices without changing the immediate earnings story.
Lloyds Banking Group's narrative uses analyst estimates that point to revenues of £25.6b and earnings of £7.5b by 2029, based on forecast revenue growth of 9.1% per year and a move in earnings from £4.8b today to £7.5b, which is an increase of about £2.7b from current earnings.
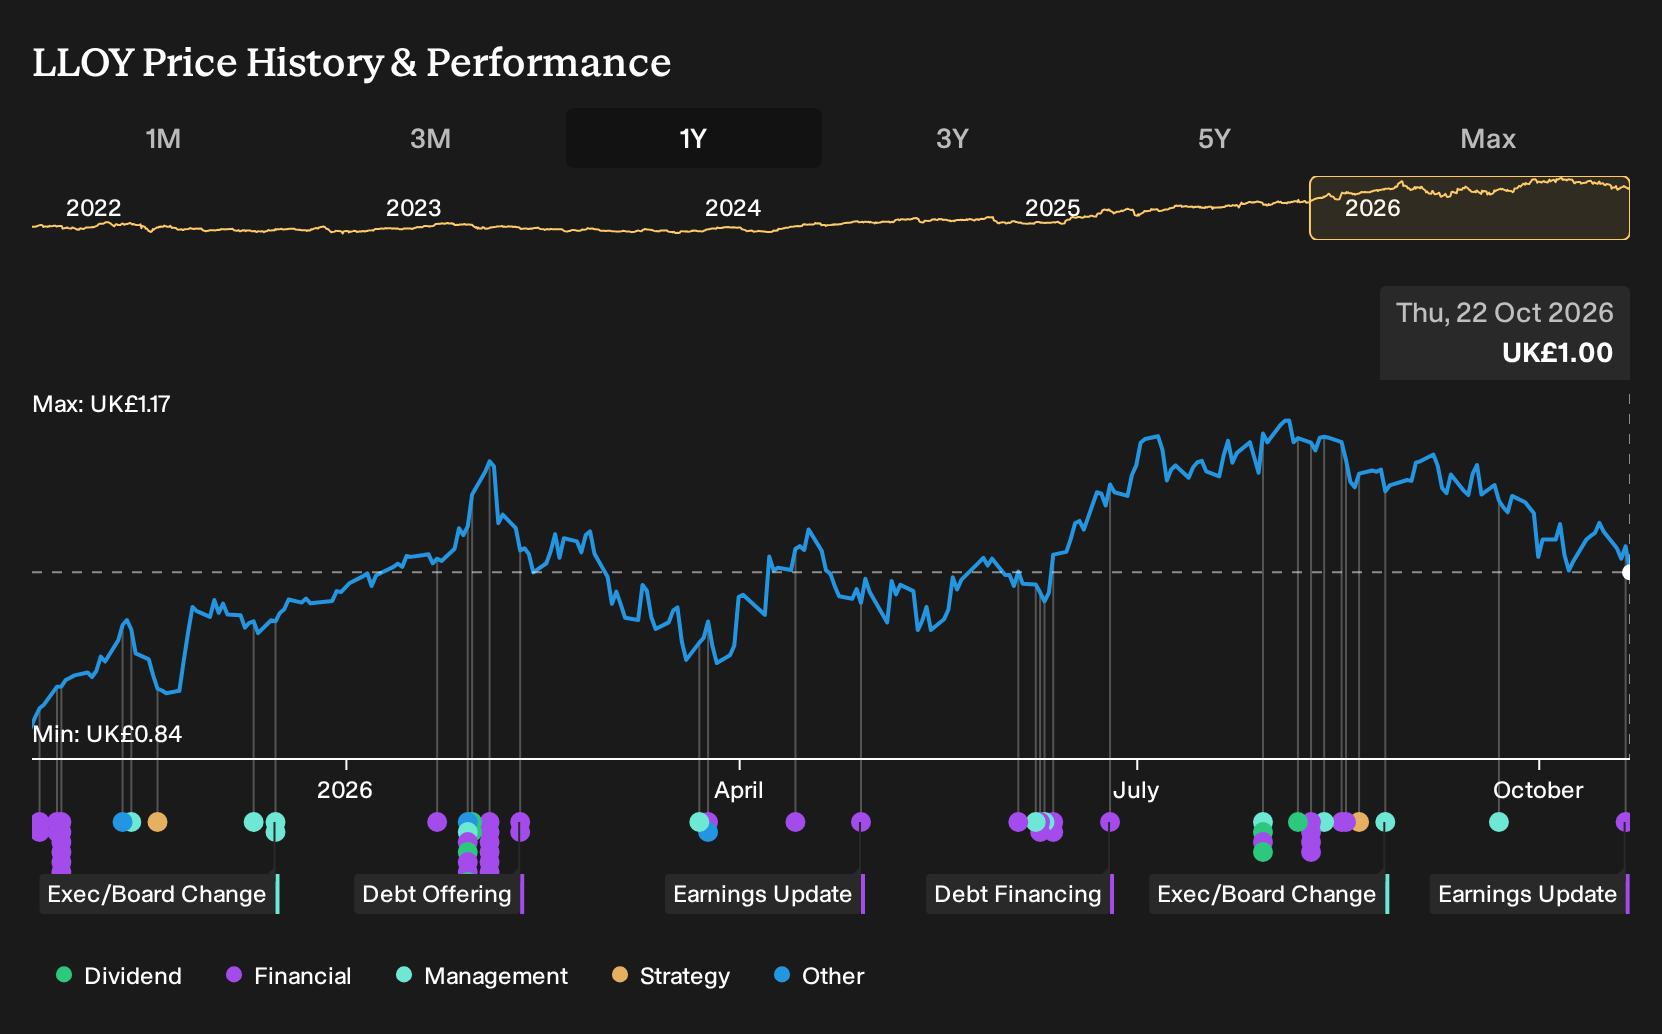
Uncover why Lloyds Banking Group's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The bearish cohort focuses on a different risk for Lloyds Banking Group. They worry that heavy AI and tech investment simply pushes costs higher rather than protecting profits, even with forecast 9.6% revenue growth and about £7.4b earnings by 2029. These pre news estimates sketch a much harsher story, so treat them as one of several viewpoints to test as you watch how the new board appointments and earnings results influence the narrative.
Explore 7 other Lloyds Banking Group fair value estimates, including one that suggests it could be worth just £1.07.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Lloyds Banking Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Lloyds Banking Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lloyds Banking Group's overall financial health at a glance.
Looking for more ideas beyond Lloyds Banking Group?
If you want to pressure test your view on Lloyds Banking Group against other opportunities, a quick pass through the Simply Wall St Screener can help you line up alternatives with different risk, income and valuation profiles in minutes.
- If capital protection is your first filter, start with a curated set of resilient businesses through the 4 resilient stocks with low risk scores to see which stocks combine steadier fundamentals with lower risk scores.
- If future cash flows matter more than the story, run your eye over the 6 high quality undervalued stocks and compare companies where quality and pricing look more aligned to your return targets.
- If reliable income is the priority, scan the 4 dividend fortresses and focus on stocks that pair 5%+ yields with an emphasis on durability rather than a reach for yield alone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com