


- Garmin recently launched three high end cycling devices: the Edge 1060, the Edge Explore 3 and 3 Plus computers, and the Tacx Nera indoor smart trainer, adding voice control, richer navigation and tighter links to Garmin’s broader ecosystem.
- The push into voice enabled riding, hazard reporting and Zwift ready indoor training highlights Garmin’s focus on deeper engagement rather than just one off device sales.
- This move into voice controlled cycling devices and immersive indoor training could influence how investors view Garmin’s overall strategy.
Scan beyond Garmin and see how other hardware driven fitness and cycling plays are setting up right now by reviewing the curated 21 high quality undiscovered gems that share similar connected-device tailwinds.
Garmin Investment Narrative Recap
For Garmin, the big picture you need to buy into is that high end fitness, outdoor and aviation gear, plus growing services, can offset pressure in weaker categories like consumer auto, parts of Outdoor and a draggy Auto OEM segment. The fresh cycling hardware fits that story by leaning into engaged endurance athletes who already live in Garmin Connect and its newer paid tiers.
The key near term swing factor is how Fitness and related subscriptions track against rising component costs and expected Auto OEM margin pressure. This week’s cycling launches look helpful around engagement but do not change the central risk that higher memory pricing or prolonged Outdoor softness could cap earnings progress.
Among the recent updates, the Edge 1060 release is the closest match to what matters for Garmin stock right now. It takes a familiar product line and layers in voice, richer routing and closer links to Garmin’s training stack. This ties directly into the company’s push toward higher margin software and coaching services.
For you as a shareholder, the important question is execution. If Garmin can pull more cyclists into Garmin Connect, Garmin Coach and its TrainingPeaks or Tacx ecosystem using devices like the Edge 1060, it has more room to lean on recurring revenue when Outdoor softness or Auto OEM losses bite into hardware profitability.
Garmin's analyst narrative points to US$10.0b in revenue and US$2.3b in earnings by 2029, based on an assumed 9.1% yearly revenue growth rate and an earnings increase of about US$0.4b from US$1.9b today.
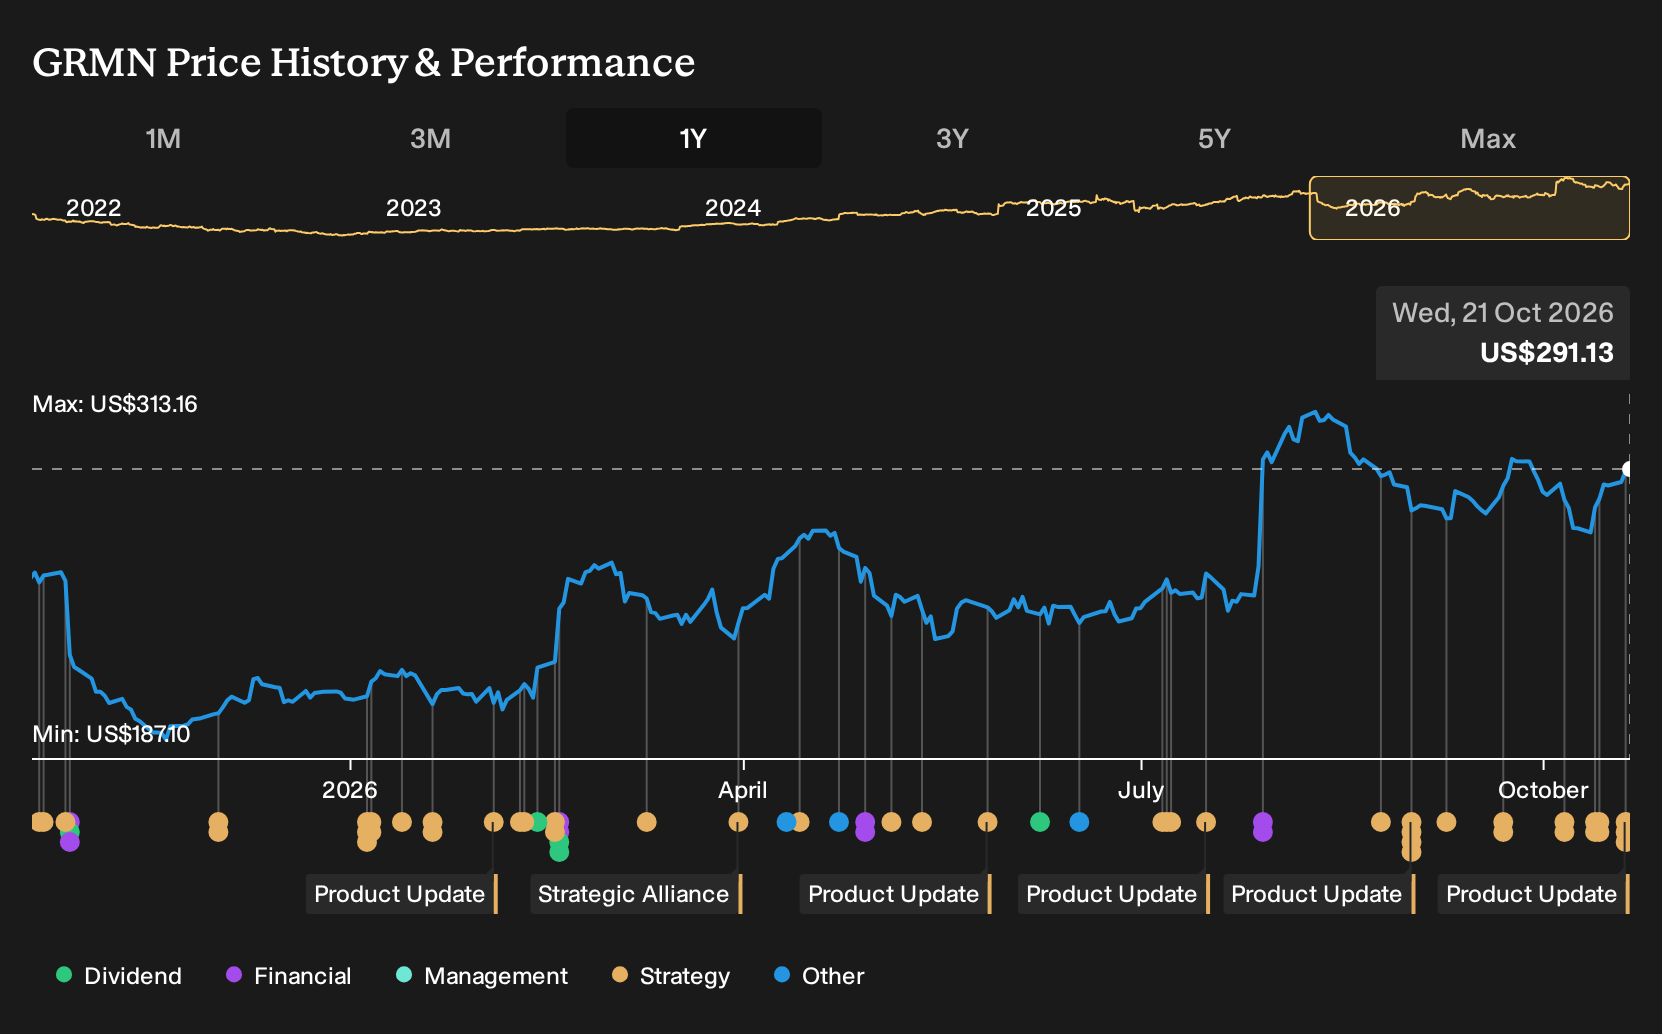
Uncover why Garmin's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view you should weigh is margin risk. The most cautious analysts were working off roughly US$9.9b of 2029 revenue and US$2.2b of earnings before this Garmin cycling launch, and see less room for pricing power. That group already bakes in pressure, so fresh voice led devices could eventually shift their story, or reinforce it.
Explore 4 other Garmin fair value estimates, including one that suggests as much as 21% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Garmin research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Garmin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Garmin's overall financial health at a glance.
Looking for more Garmin sized investment ideas?
Once you are clear on where Garmin fits in your portfolio, it can help to line it up against other opportunities that share similar traits, whether you care most about value, resilience, or income.
- For investors hunting for value with quality backing it up, scan through 33 high quality undervalued stocks that pair stronger balance sheets and cash flow with more modest expectations baked into the share price.
- If capital preservation matters just as much as upside, compare Garmin with a 31 resilient stocks with low risk scores that screen for sturdier fundamentals and lower overall risk scores.
- Income focused holders who want yield alongside durability can weigh Garmin against a 7 dividend fortresses that target higher payouts supported by more robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com