


Lam Research has turned a long run in the semiconductor equipment cycle into a powerful share-price story, yet the recent pullback raises a sharper question for you as an investor. With fresh headlines on supply constraints, AI spending and chip sector swings, the issue is whether the current Lam Research stock price lines up with what its earnings can reasonably support.
- Over the past 5 years the share price has gained 395.6%, which puts a lot of weight on whether the underlying earnings justify that kind of compounding.
- Recent record revenue, strong operating profitability and comments about supply chain bottlenecks all feed directly into how durable Lam Research's earnings power may be and how soon that shows up in cash flows.
- There is a second opinion on Lam Research worth weighing. See what analysts think Lam Research's shares could be worth.
The stock's next move may depend on whether its current earnings, and what they signal about future profitability, are enough to support where Lam Research trades today.
If you want to test the same earnings question driving Lam Research across a wider set of AI infrastructure suppliers, scan the 55 AI infrastructure stocks.
Does Lam Research Look Fairly Valued on Earnings?
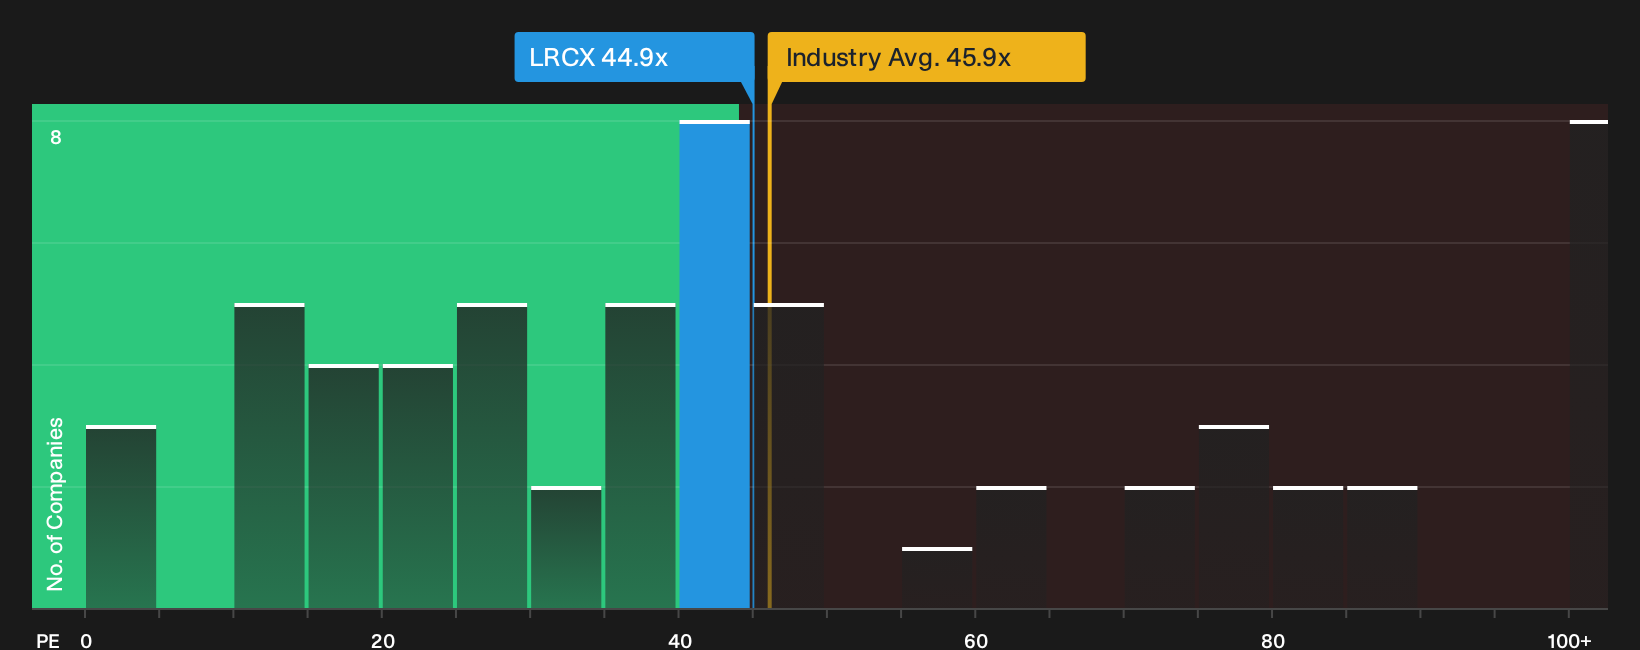
The P/E ratio is a useful yardstick here because Lam Research already generates earnings and sits in a sector where investors routinely compare stocks on this metric. Lam Research trades on a P/E of 44.9x, a touch above its peer group average of 42.3x and only slightly below the broader semiconductor industry level of 45.9x. That leaves the stock priced broadly in line with what investors are paying for similar chip equipment businesses.
The tailored fair multiple implied by its fundamentals model is close to where the market currently values Lam Research, so the shares do not screen as clearly cheap or stretched on earnings alone. Despite recent headlines about record quarterly results on one side and supply chain constraints on the other, the current P/E still prices Lam Research roughly in step with sector expectations for profitable AI focused equipment suppliers. Explore the numbers behind Lam Research's P/E valuation.
The Lam Research Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Lam Research valuation puzzle leaves off. They spell out which growth paths, profitability levels and earnings profiles would need to play out for the stock to be worth materially more or less than it is today. Each one ties its number to a clear view on how Lam Research's growth, margins and risk profile might evolve, which you can revisit as fresh information comes through.
One of the top community narratives on Lam Research: 38% undervalued
"Lam makes money on the shortage and makes money on the response to it, because the capacity that eventually relieves the shortage has to be bought from somewhere…"
Discover why this Narrative puts Lam Research at 38% undervalued.
One more Lam Research check that sits alongside the P/E story
Price ratios tell you what the market believes today, while the grid of multi year analyst projections gives you a different lens on where Lam Research could be heading a few reporting cycles from now. Explore where analysts expect Lam Research to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com