


Oil prices have jumped to a five month high as attacks on Saudi infrastructure raise fresh concerns about global crude supply. Higher fossil fuel costs can make long term clean power contracts look more attractive, especially for Canadian renewable energy projects that do not rely on imported oil. This article walks through three stocks from the renewable power universe that could help you position your portfolio for that shift.
The three renewable energy stocks below are just a sample set. The wider screen surfaced 7 more operators and developers with similarly detailed investment stories that are not covered here.
If you want to identify potential high-conviction opportunities in this space, head straight to the Renewable (solar, wind, hydro or tidal) Energy screener to filter and analyze renewable energy stocks by the factors that matter to you.
Alaska Hydro (TSXV:AKH.H)
Overview: Alaska Hydro focuses on developing hydroelectric projects in northwest British Columbia, with the More Creek hydropower project as its key renewable asset.
Market Cap: CA$0.77 million
Alaska Hydro gives you pure-play exposure to early stage hydropower development, centered on the More Creek project in northwest British Columbia. The business currently has minimal revenue and ongoing losses, so the focus is on how a capital intensive hydro build might affect its economics if a single pressure around funding is resolved in its favor.
If that funding question is key for you, review the Alaska Hydro financial health report to see how Alaska Hydro’s balance sheet could handle a full project build.
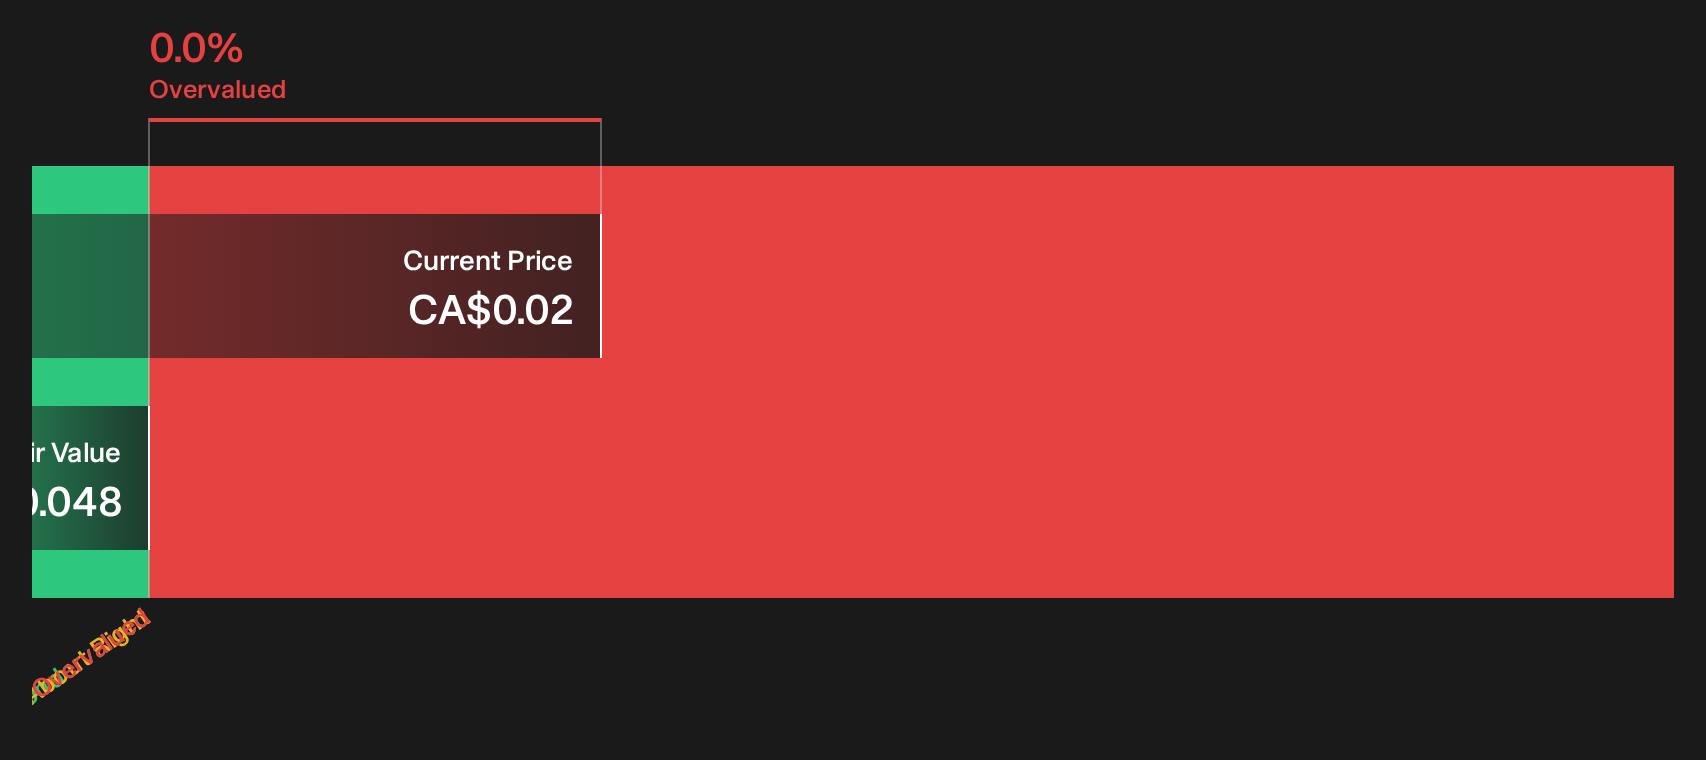
Gencan Capital (CNSX:GCA.X)
Overview: Gencan Capital is a Toronto based holding company with a historical focus on operating solar power generation projects, but currently reports no significant activity.
Market Cap: CA$1.52 million
Gencan Capital sits on the fringes of the renewable theme, with a solar generation past, minimal current activity and continued net losses reported into 2026. For investors who track early stage or dormant renewable stories, the tiny scale and fragile finances mean any shift in operational direction or funding access could significantly affect how the business develops.
Those potential pivots make it worth reviewing the analysis report for Gencan Capital before sentiment shifts and any new capital or project move resets expectations.

Northland Power (TSX:NPI)
Overview: Northland Power generates electricity from offshore and onshore wind, solar, natural gas and battery storage across several countries under long-term contracts.
Operations: Most revenue comes from International Offshore Wind at about CA$1.25b, with meaningful contributions from Canadian and Colombian utilities and American natural gas.
Market Cap: CA$5.73b
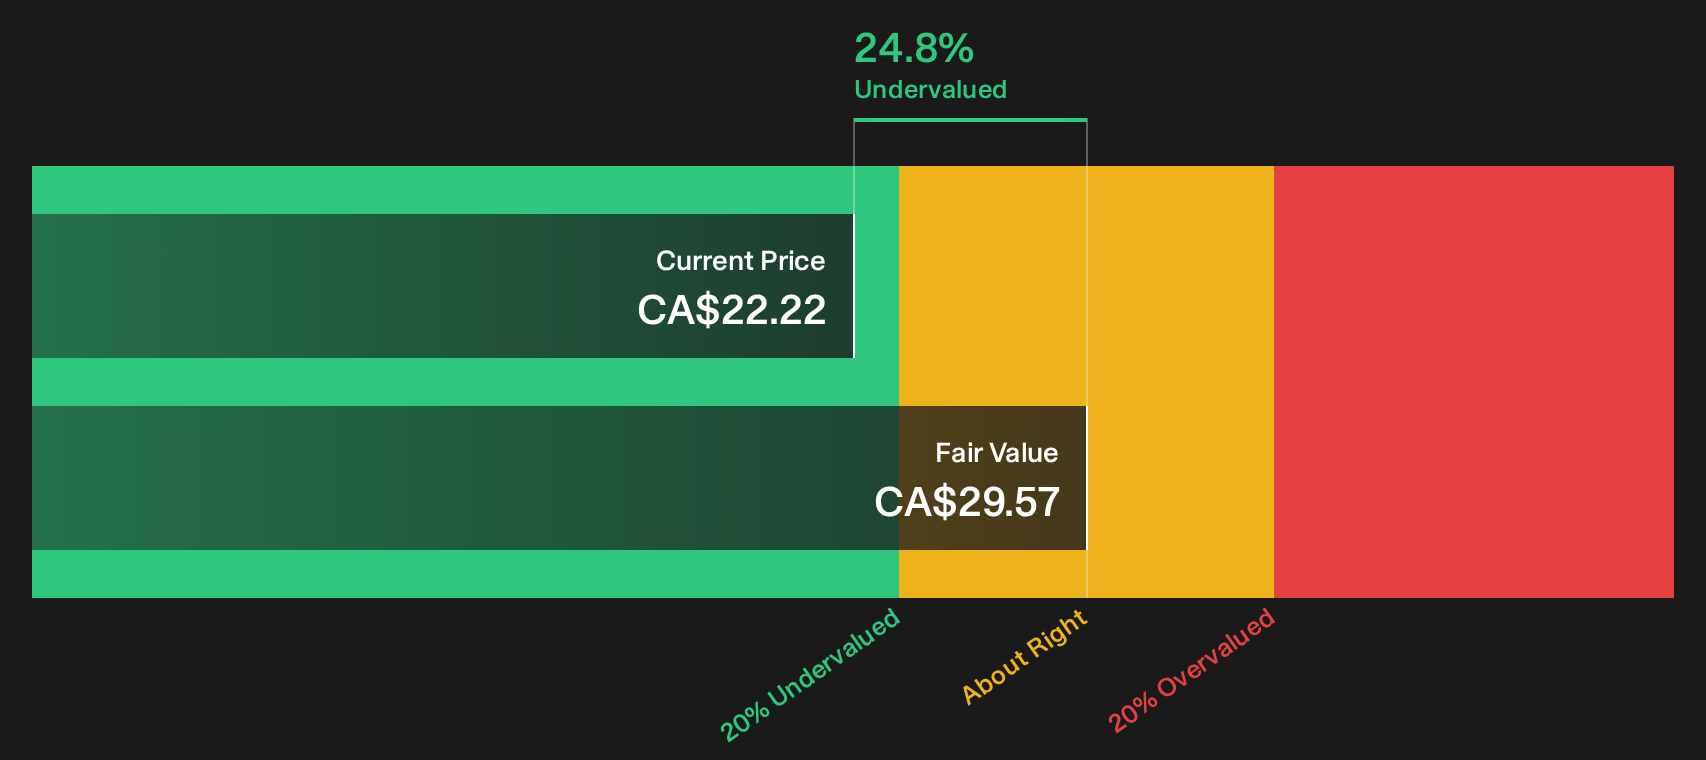
Northland Power matters in this renewable energy screen because its offshore wind fleet and grid-scale storage projects directly tie earnings to contracted clean power.
"The build out of Hai Long and Baltic Power, which are close to full turbine installation and supported by long duration contracts, is set to add large scale offshore wind capacity that can support higher revenue and adjusted EBITDA once fully in service."
What happens to margins and dividend comfort will largely depend on how one funding pressure around this contracted build-out ultimately resolves.
That funding question is exactly what the full narrative for Northland Power unpacks, highlighting where risks might be easing and where contracted cash flows could be accelerating.
Seeking Fresh Alternatives Beyond Renewables?
Fresh opportunities often move first, then get caught by momentum traders once the story is out. Scan new angles before the crowd while it matters and act now.
- Spot cash generative businesses before they start flying by running the list of solid balance sheet and fundamentals (7 results) and focus on companies with room to compound over time.
- Target income ideas that aim to keep paying even when markets feel choppy by scanning the 3 dividend fortresses for potential high-yield fortress candidates.
- Hunt for overlooked quality that has not yet been fully priced in and filter through the 10 high quality undiscovered gems while these stories are still under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com