


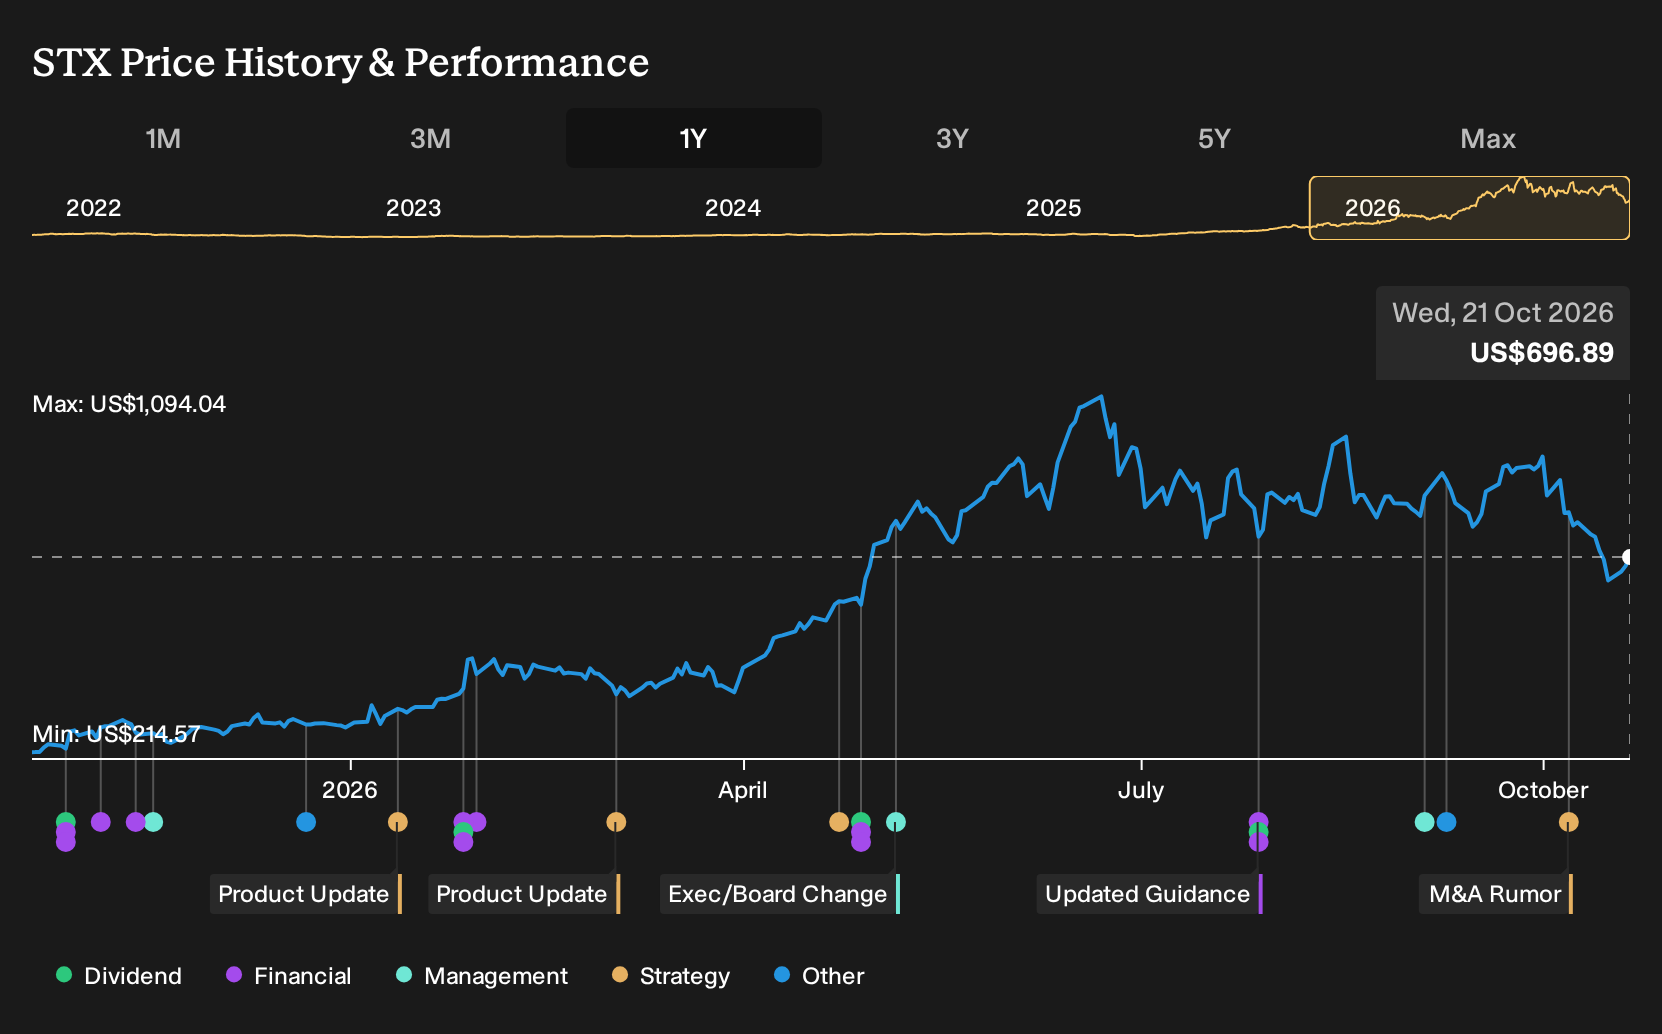
- Recent reports on Seagate Technology Holdings highlight strong demand for high capacity hard disk drives tied to data center, cloud, and AI workloads, with tight industry supply giving the business pricing power in enterprise storage products.
- An unusual feature of the recent commentary is how often analysts point to industry wide capacity shortfalls and Seagate's HAMR rollout as key supports for margins, rather than focusing mainly on short term trading or rating changes.
- The next area of attention will be how Seagate Technology Holdings' investment narrative aligns with rising AI driven storage demand and updated earnings expectations.
Seagate Technology Holdings Investment Narrative Recap
To own Seagate Technology Holdings, you need to be comfortable with a story built around AI driven data center storage, HAMR based Mozaic drives, and long term build to order contracts that tie up nearline capacity through 2028 and beyond. The key short term catalyst is execution on this HAMR roadmap and getting paid for tight industry supply through price per exabyte.
The biggest risk right now is that expectations around AI storage demand and margins are high, while trading in AI linked hardware has been volatile. The latest pullback in AI exposed stocks appears sentiment driven rather than the result of a clear change in Seagate’s operating backdrop, so the impact on the core thesis looks limited for now.
The most relevant recent development is the run of positive earnings estimate revisions tied to Seagate Technology Holdings and its move onto the Zacks Rank #1 list. That shift follows commentary around tight hard drive supply, strong AI centric demand, and the importance of Mozaic nearline shipments to revenue mix and gross profit.
For you, the link back to catalysts is straightforward. If HAMR adoption, build to order contracts, and industry supply discipline keep supporting price per exabyte, then the upgraded earnings outlook becomes a live test of execution rather than just sentiment. The risk is that any slowdown in AI data center orders or a macro shock would challenge those estimates quickly.
Seagate Technology Holdings: What The Numbers Assume
On the current analyst framework, Seagate Technology Holdings is being valued against a 2029 world where both revenue scale and profitability look very different from today. The consensus profile leans heavily on compounding AI storage demand, wider margins and a much lower P/E multiple than the stock carries right now. As a result, the gap between today’s financials and those targets is doing most of the work in the story.
Seagate Technology Holdings' narrative projects US$31.1b revenue and US$16.1b earnings by 2029. This rests on analysts baking in 36.6% yearly revenue growth and an earnings increase of about US$12.9b from US$3.2b today.
The core assumptions are clear. Analysts are calling for revenue to expand at 36.6% a year for the next three years, while net margin moves from 26.1% today to 51.6% by roughly 2029. That margin step up does as much heavy lifting as top line growth, because it effectively assumes Seagate can convert a much larger share of every exabyte sold into bottom line profit as Mozaic penetration rises and pricing on nearline drives holds.
On earnings, the consensus figure clusters around US$16.1b by about September 2029 with some estimates reaching as high as US$18.6b. That implies current earnings of US$3.2b would need to scale by roughly US$12.9b over the period, driven by both higher volumes and richer profit per unit, while share count itself is projected to climb 6.13% a year for the next three years.
Valuation work in the report then ties those operating targets to a future P/E. To get to the current analyst price targets, Seagate would need to trade on about 24.1x those 2029 earnings, compared with a reported 61.3x today and a current US tech sector level of 25.2x. That means the story combines rapid earnings expansion with a lower earnings multiple, a mix that leaves little room for disappointment if either revenue growth or margin ambition slips.
Putting the pieces together, the consensus framework effectively says the stock makes sense at the latest targets if three things all line up. Revenue tracks towards roughly US$31.1b, net income reaches around US$16.1b, and investors are still willing to pay a mid 20s P/E for a high margin AI storage specialist. Any break in that chain, whether from softer data center orders, weaker pricing or a reset in what the market will pay for earnings, would challenge the current narrative quickly.
Uncover how Seagate Technology Holdings' fair value indicates a 61% potential upside to its current price before competing buyers close that discount.
Exploring Other Perspectives
One alternate angle to watch is competition from Toshiba’s planned HDD capacity build out. The most cautious analysts already penciled in lower 2029 outcomes for Seagate Technology Holdings, with about US$29.5b revenue and US$15.0b earnings before this latest news. That group effectively prices in tougher pricing power, so use today’s headlines to compare these very different viewpoints.
Explore 5 other Seagate Technology Holdings fair value estimates, including one that suggests it could be worth just $705.49.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Seagate Technology Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Seagate Technology Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Seagate Technology Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Seagate Technology Holdings?
If the Seagate Technology Holdings setup has you thinking about how to position your portfolio for different types of opportunity, the Simply Wall St Screener can help you line up other stocks that fit your risk, income, and quality preferences in a more systematic way.
- If you want income to do more of the heavy lifting, start with companies that offer robust payouts through 7 dividend fortresses and see which ones match your return goals and risk tolerance.
- If capital preservation and resilience come first for you, filter for businesses that score well on stability by checking out 31 resilient stocks with low risk scores that seek to balance quality with more measured volatility.
- If you are hunting for mispriced opportunities with stronger fundamentals than their valuations suggest, focus your search on 21 high quality undiscovered gems that the market may not be fully paying attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com