


Canadian Pacific Kansas City (TSX:CP) is back in the spotlight as its Holiday Train prepares for a 182 stop tour, while investors weigh expectations ahead of the late October earnings release.
Recent trading has been steady rather than explosive, with a 1 month share price return of 1.34% and the 1 day move of 0.76% keeping Canadian Pacific Kansas City near CA$123.65. At the same time, a 90 day share price decline of 4.93% indicates some momentum has cooled, even as the 1 year total shareholder return of 16.55% and 5 year total shareholder return of 37.53% point to a longer record of value creation.
Scan beyond Canadian Pacific Kansas City and size up other rail and infrastructure linked opportunities using our curated list of 42 power grid technology and infrastructure stocks.
Canadian Pacific Kansas City now trades at a discount to analyst targets, even as earnings expectations have softened. Is the market being sensibly cautious or overly wary on valuation?
Most Popular Narrative: 11% Undervalued
Canadian Pacific Kansas City closed at CA$123.65, while the most followed narrative estimates fair value at about CA$139.53 using a 7.77% discount rate. That gap anchors a view that the current price leaves room relative to the long term cash generation outlined by analysts.
Expansion of the north south three country network into underpenetrated Mexico and U.S. South corridors for grain, potash, LPGs and refined fuels positions CPKC to capture share from trucking and short sea. This is described as supporting durable volume growth and higher revenue over many years.
Development of the Meridian Speedway and the CSX connection through Myrtlewood and Montgomery, which enables truck competitive transit times between Dallas, Atlanta and the Southeast industrial corridor, is expected to unlock new industrial and intermodal flows that enhance length of haul, mix and earnings power from 2026 onward.
See why 10 investors see Canadian Pacific Kansas City as 11% undervalued.
Result: Fair Value of CA$139.53 (UNDERVALUED)
Still, prolonged economic softness in freight heavy sectors, or setbacks on key projects like the Meridian Speedway, could quickly challenge the current Canadian Pacific Kansas City narrative.
Find out about the key risks to this Canadian Pacific Kansas City narrative.
Another View: Canadian Pacific Kansas City On Earnings Multiples
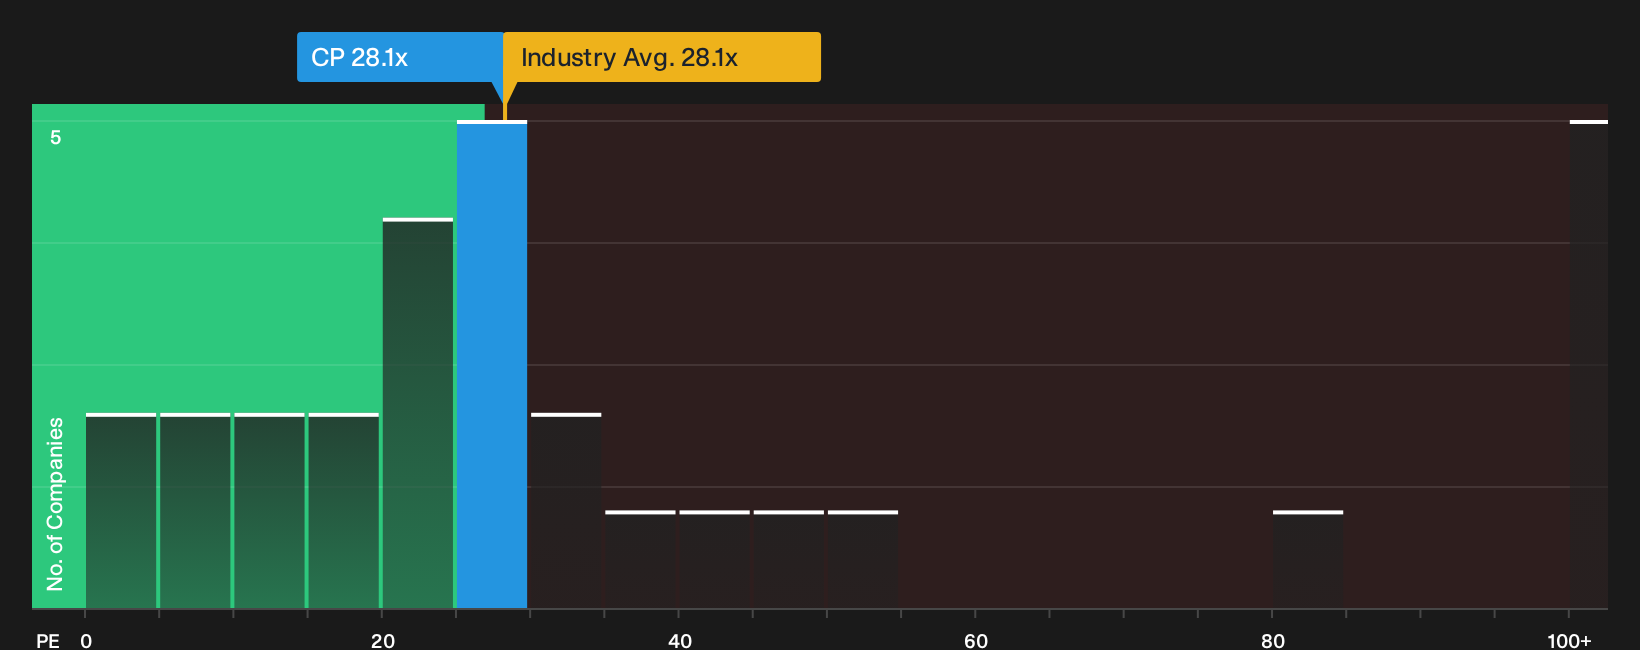
The cash flow narrative points to an 11% gap to fair value, yet the earnings multiple tells a more cautious story. Canadian Pacific Kansas City trades on a P/E of 28.1x, which is higher than the North American transportation average at 27.9x, the peer average at 26.3x, and even above a fair ratio estimate of 27.7x. That premium suggests investors already pay up for the story, so the key question is how much upside is really left if sentiment cools.
For a closer look at how this pricing stacks up against earnings power, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Canadian Pacific Kansas City so far. If you want to move quickly and reach your own view, start with the headline trade off between upside potential and risk profile outlined in the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Canadian Pacific Kansas City?
Canadian Pacific Kansas City might be your starting point, but your portfolio deserves a wider bench of opportunities tailored to different risk levels and income goals.
- Target resilient cash generators by scanning a 4 high quality undervalued stocks that combines quality fundamentals with prices that sit below many investors’ radars.
- Strengthen your income stream by reviewing a 3 dividend fortresses focused on higher yielding businesses with the potential to support regular payouts.
- Dial down portfolio stress by filtering for a 8 resilient stocks with low risk scores that highlights companies with steadier profiles and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com