


McCormick has had a tough few years on the market, and the gap between the share price and the story investors once told themselves about its earnings is getting harder to ignore. After a long slide, the key issue is whether what you pay for the spice maker today still lines up with what its profits can realistically support.
- Over the past 5 years the stock has fallen 35.1%, which puts the current valuation debate squarely on what the underlying earnings are worth now rather than what they were in the past.
- The planned US$45b merger with Unilever's food business could reshape McCormick's earnings profile, since a much larger portfolio and wider geographic reach may support different expectations for profit scale and volatility over time.
- There is a second opinion on McCormick worth weighing. See what analysts think McCormick's shares could be worth.
For investors, the debate is whether today's McCormick share price is appropriately aligned with the earnings the combined business can generate.
If you want more ideas on where to put earnings at the center of your research, start with a focused list of 33 high quality undervalued stocks.
Is McCormick Fairly Priced on Earnings?
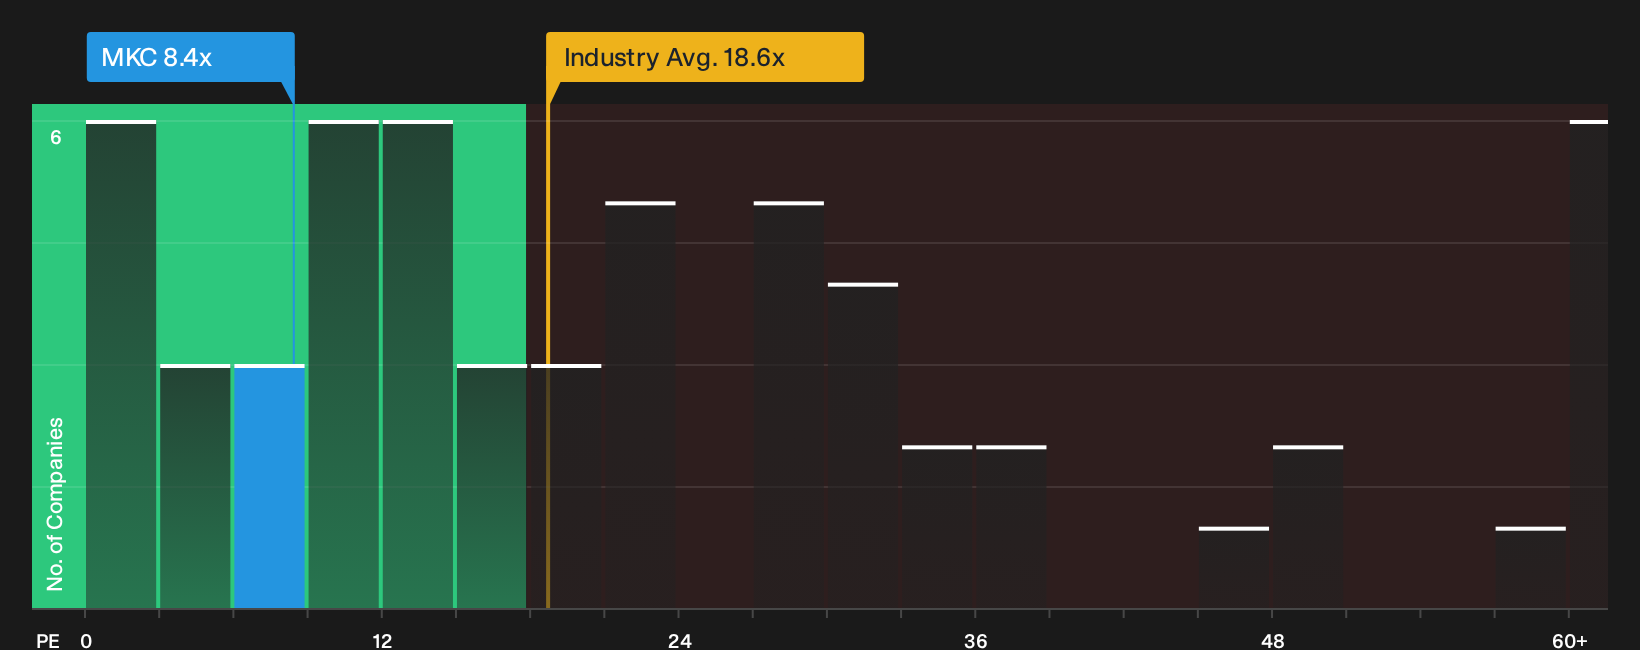
The P/E ratio fits McCormick because earnings remain the clearest anchor for a branded food business, even with a major merger on the table. On this measure, the stock trades on roughly 8.4x earnings, which is far lower than the Food sector average of about 18.6x and the peer group around 34.6x. Against the tailored fair multiple that blends McCormick's own growth profile, profitability and risk, the current P/E looks about right rather than screamingly cheap or stretched.
Because the planned US$45b merger with Unilever's food business has sharpened attention on the future earnings base, the low headline P/E needs context. The combined group could carry different margin and volatility characteristics, so this multiple will likely be reassessed as integration, competitive pressure from private labels and any deal related costs show up in reported profit. For now, the current earnings multiple suggests the market is pricing McCormick at a level that roughly matches what the fair value model implies, which still leaves room for readers to weigh how durable those profits feel over the next cycle. Explore the numbers behind McCormick's P/E valuation.
The McCormick Narrative: What Would Justify Today's Price?
Narratives pick up where this McCormick valuation puzzle leaves off and spell out which paths for growth, margins and earnings would need to play out for the stock to trade meaningfully higher or lower than it does today on Simply Wall St's Community page. Rather than anchoring on a single multiple or model result, each narrative presents the earnings assumptions behind its fair value view so you can compare those inputs with actual results as they arrive in McCormick's reports.
One of the top community narratives on McCormick: 29% undervalued
"Bullish analysts still highlight McCormick's ability to deliver gross margin driven EPS beats, even as price targets move lower, which supports the view..."
Discover why this Narrative puts McCormick at 29% undervalued.
McCormick’s valuation still leaves one crucial piece of the puzzle
Price tags and earnings multiples only tell part of the story. The people steering McCormick and the way their pay is structured can heavily shape how future decisions play out. See who runs McCormick and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com