


EchoStar has delivered a very large 3 year return, and with fresh takeover chatter and analyst upgrades in the mix, the real question now is how that price stacks up against the company’s sales. For anyone looking at the stock today, the issue is less about headlines and more about what the current valuation asks you to pay for each dollar of revenue.
- EchoStar’s share price has risen very sharply over the past 3 years, which puts extra focus on whether the business performance behind it, especially sales, can support that kind of move.
- Recent discussion around a possible SpaceX bid and upgraded analyst views that reference asset values and capital allocation may support different expectations for future revenue and cash flow than the market had a year ago.
- There is a second opinion on EchoStar worth weighing. See what analysts think EchoStar's shares could be worth.
The issue now is whether EchoStar’s current share price is justified by its sales when compared against the Fair Ratio benchmark.
If you want to stress test the same sales focused question you are asking about EchoStar against a wider field, line it up beside companies in the 33 high quality undervalued stocks
.Does EchoStar Look Pricey on Sales?
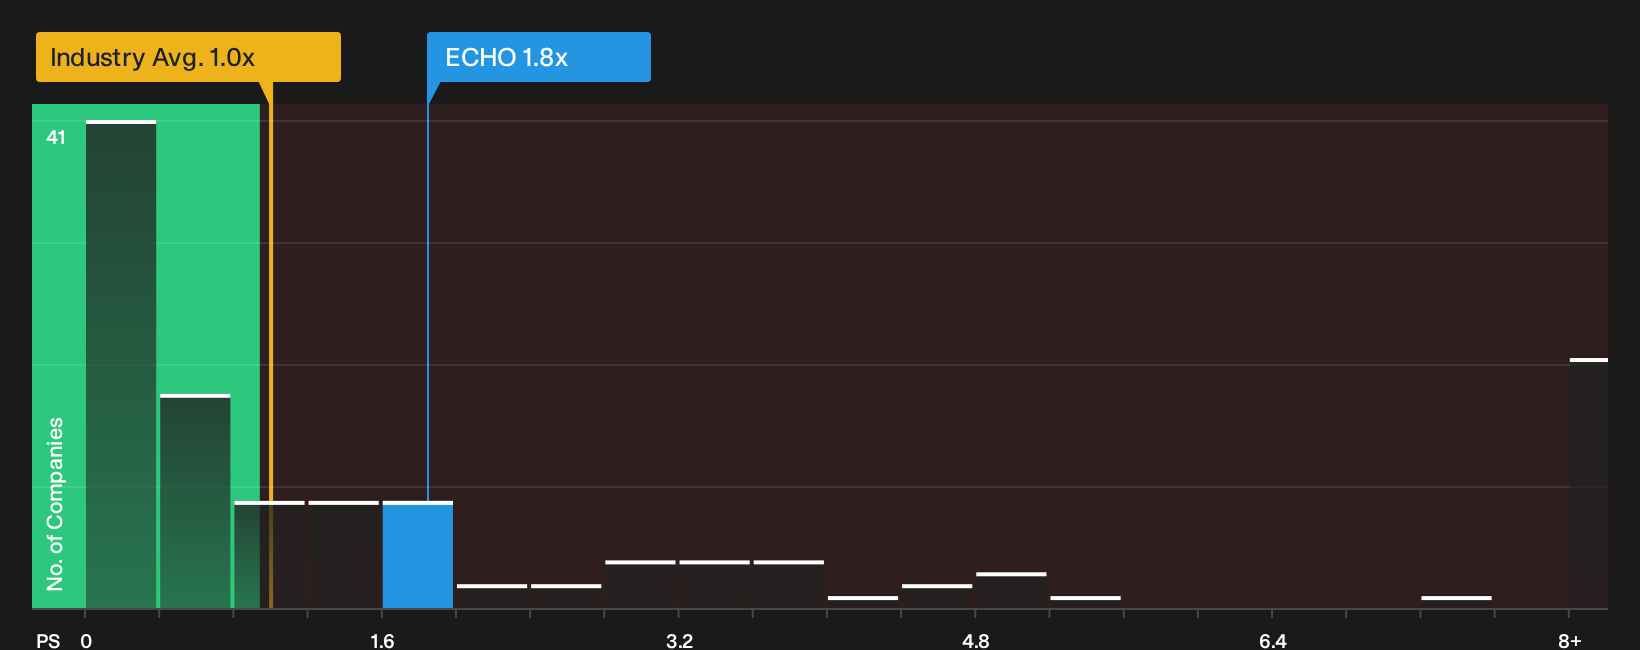
The P/S ratio suits EchoStar because the story investors are watching is top line scale rather than current profits. On this metric, the stock trades at about 1.8x sales, which is above both the media industry average of roughly 1.0x and the peer group near 0.9x. That already tells you the market is paying more for each dollar of EchoStar’s revenue than for many comparable businesses.
The Fair Ratio model, which adjusts for EchoStar’s growth profile, margins, size and risk, also points to a lower P/S than the market is currently applying, so the shares screen as overvalued on this yardstick. Despite the recent takeover talk around a potential SpaceX bid and bullish analyst targets lifting sentiment, the valuation still embeds a richer sales multiple than the benchmark would suggest. For anyone considering EchoStar today, the key question is whether its future revenue quality and cash generation can live up to the premium implied by this gap. Explore the numbers behind EchoStar's P/S valuation.
The EchoStar Narrative: What Would Justify Today's Price?
EchoStar’s valuation puzzle becomes more concrete once you reach Simply Wall St Narratives. These spell out what future growth, margins and earnings would need to look like for the stock to be worth materially more or less than today’s price, and these storylines live on the company’s Community page. Each one treats EchoStar’s fair value as a thesis you can track over time so you can see how the underlying idea holds up as new information comes through.
EchoStar brings out sharply opposed views, with bulls leaning on asset exposure and bears focused on how much future execution is already priced in.
Bull case: 28% undervalued
"Success in monetizing EchoStar's substantial spectrum assets, either through launching lucrative new services, entering wholesale partnerships with global carriers, or potential spectrum sales/leases, could unlock significant one-time gains or ongoing income..."
Discover why this Narrative puts EchoStar at 28% undervalued.
Bear case: 111% overvalued
"The problem for us retail investors is that SpaceX is private, you can’t just buy it on Robinhood, and that is exactly why EchoStar is so interesting..."
Explore why this Narrative puts EchoStar at 111% overvalued.
EchoStar’s valuation still leaves one crucial angle unresolved
There is another clue investors can use to pressure test today’s pricing. It sits in how professional forecasters currently see EchoStar a few years from now. Explore where analysts expect EchoStar to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com