


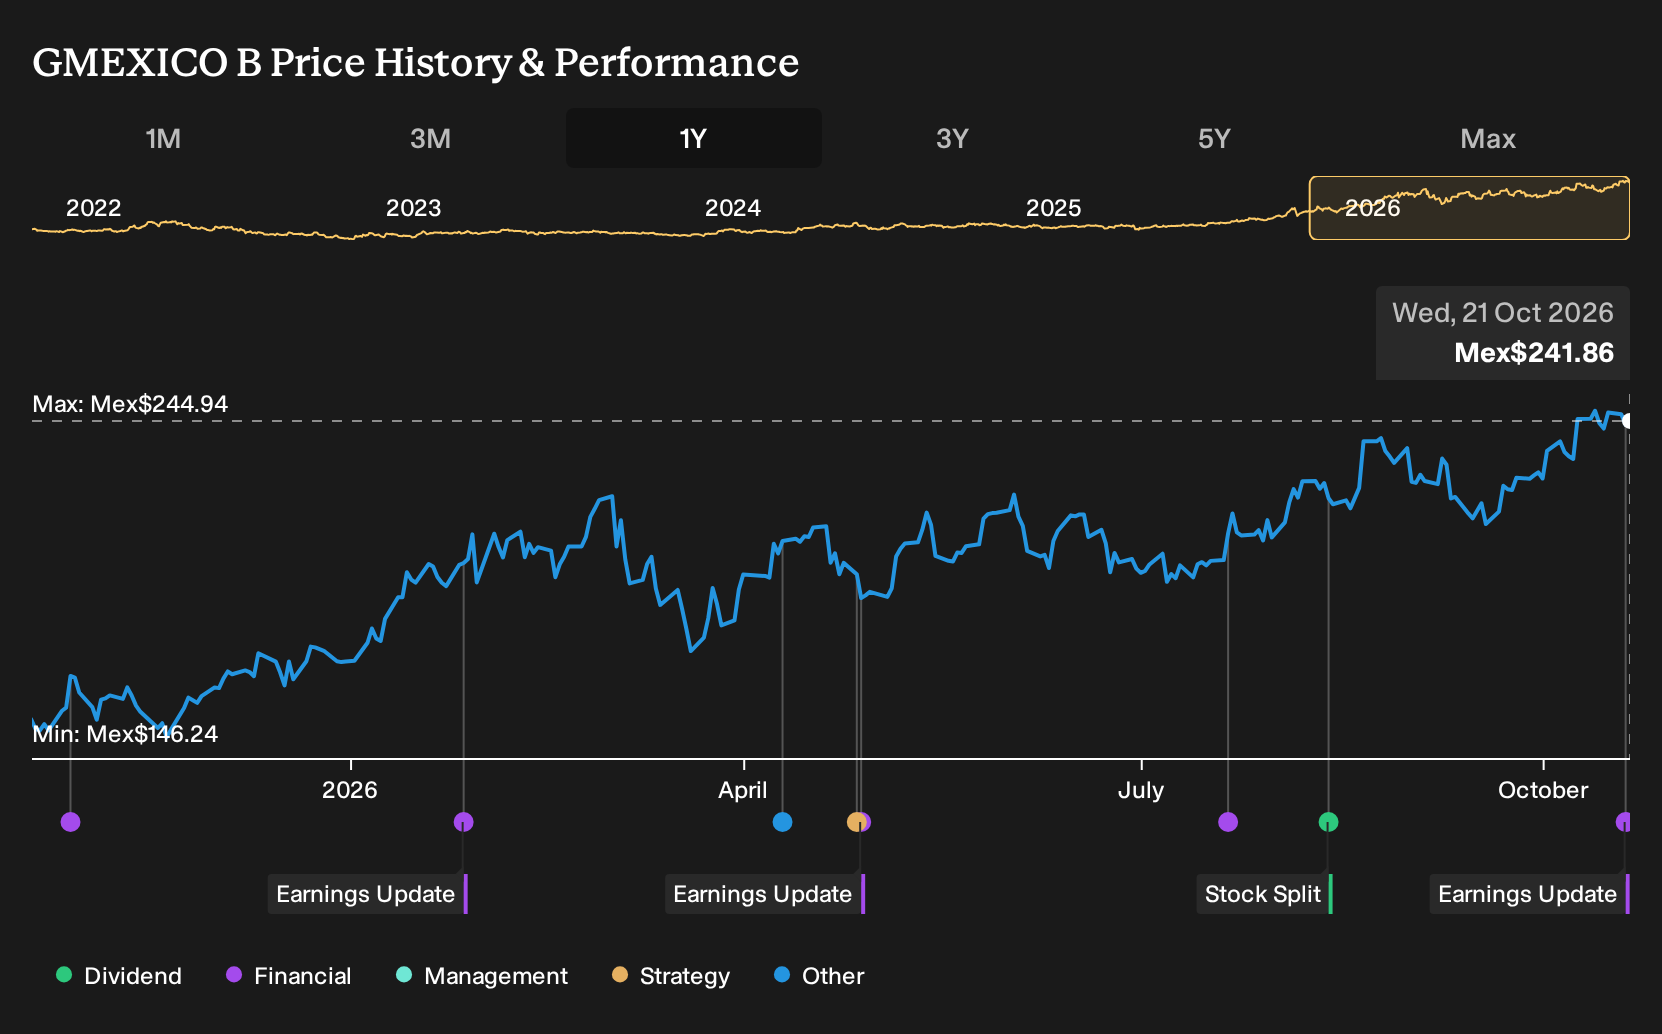
The latest report from Grupo México. de showed Q3 2026 revenue of US$6,333.016m and net income of US$1,984.469m, with net margin at 31.3%. Investors who held Grupo México. de over the past year are up 65.5%, including dividends. If you were deciding back on 21 October 2025 whether to buy, what did you need to believe about those Peru projects and copper exposure before any of this was on the screen?
Grupo México. de has already moved. See which of 196 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing Up On Grupo México
The shares cost MX$149 at the start of the period, so any investor looking at Grupo México then had to decide whether that level already captured the copper story or still left room for upside.
The bullish narrative put Fair Value at MX$168, a price implied by assumptions of global electrification lifting copper demand alongside margin expansion from Peru projects and lower net cash costs.
The bearish view pointed to a Fair Value of MX$131, built on expectations of 4.1% revenue growth but with heavier weight on risks such as project delays, client concentration in infrastructure and regulatory shocks.
What The Results Changed For Grupo México
The clearest data point was Q3 2026 numbers. Grupo México reported revenue of US$6,333.016m and net income of US$1,984.469m, ahead of Q3 2025 on both counts, with net margin rising from 28.0% to 31.3%. That pattern leaned toward the optimistic case on margin expansion, while leaving the debate on Peru execution and copper reliance open.
The takeaway for other stocks is simple. When a thesis hangs on profitability, track reported net margin and absolute earnings against the original narrative rather than letting share price moves answer the question for you.
What Today's MX$242 Price Already Expects From Grupo México
Grupo México now trades at MX$242 after a 65.5% gain over the past year, while this Narrative’s Fair Value sits below that level based on its own assumptions.
The Narrative focuses on regulatory, environmental and copper concentration risks. For today’s price to hold, a buyer has to assume political, social and ESG pressure do not meaningfully undercut long term project stability and profitability.
"Exposure to mounting regulatory and political risk in Mexico and Peru threatens long-term revenue stability, as heightened resource nationalism, unpredictable tax regimes, and increased likelihood of asset expropriation could disrupt major projects and production timelines."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 30% below our estimate - sells AI enabled peripherals and video gear for upgraded office collaboration needs.
- Company 2 - 43% below our estimate - expands core underwear expertise into versatile sports-focused apparel for daily training.
- Company 3 - 20% below our estimate - wins optical transport contracts from Tier 2 operators serving surging AI bandwidth requirements.
Those are three of them. See every one of the 203 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com