


- Quaker Chemical recently outlined expectations for meaningful revenue and adjusted EBITDA growth in fiscal 2026, supported by new business wins, disciplined cost management, and a resilient global network. Demand is projected to remain flat to slightly positive for the rest of the year.
- The company is leaning on continued share gains to support volume growth even as macroeconomic and geopolitical conditions remain uncertain. This puts execution on its cost and transformation efforts under sharper focus for investors tracking Quaker Chemical's operating performance.
- We will now look at how Quaker Chemical's guidance for meaningful revenue and EBITDA growth could reshape its broader investment narrative.
Scan for other specialty chemical players aiming for similar margin progress by jumping into our curated list of 33 high quality undervalued stocks that may be lining up for their next move higher.
Quaker Chemical Investment Narrative Recap
To own Quaker Chemical, you need to believe the business can turn flat to slightly positive end market demand into healthier earnings through share gains, higher value fluids and its cost program. The latest outlook for meaningful revenue and adjusted EBITDA growth in 2026 aligns with that view but raises the execution bar.
The key near term swing factor is delivery on the US$20m to US$30m structural savings and progress on margin repair in the Americas, where earnings have already fallen year over year despite higher sales. The biggest risk remains sticky input and logistics costs that limit gross margin improvement even if volumes hold.
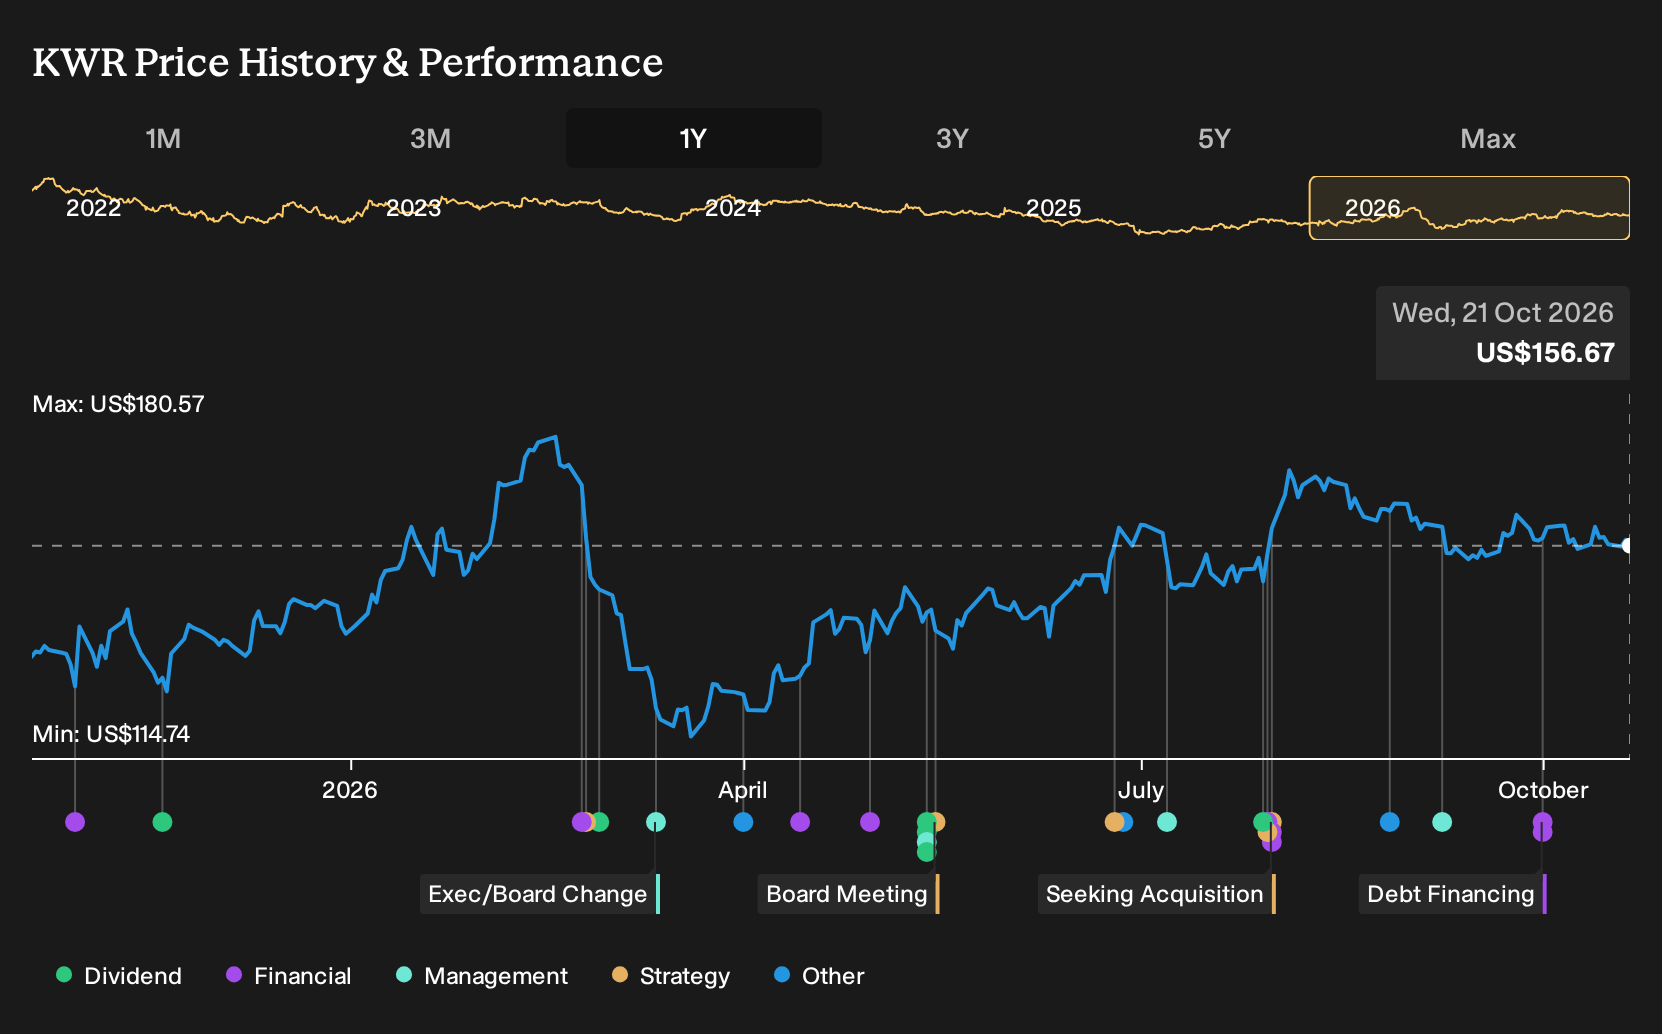
The Zhangjiagang manufacturing facility in China, which started up in June 2026, looks most relevant to this guidance. It gives Quaker Chemical local capacity across its full product set, which can support the Asia Pacific share gains management is leaning on as global demand stays flat to slightly positive.
Local production can also cut imports and improve supply flexibility, which matters if crude linked raw materials or container costs stay elevated. For investors tracking catalysts, execution at Zhangjiagang, combined with the transformation savings, sits alongside the 2026 EBITDA ambition as a tangible proof point to watch.
Quaker Chemical's current analyst narrative points to revenues of US$2.3b and earnings of US$215.8m by 2029, implying 4.6% yearly revenue growth and an earnings increase of about 2.2x from US$97.5m today.
Uncover why Quaker Chemical's fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Quaker Chemical’s acquisition firepower as a potential swing factor. Before this guidance, the bullish camp was modeling roughly 5.4% annual revenue growth and about US$216.2m in earnings by 2029, and saw scope for a higher 19.5x P/E. You can compare that outlook with today’s update and decide whether those pre news assumptions still feel realistic or need a reset.
Explore 2 other Quaker Chemical fair value estimates, including one that suggests as much as 28% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Quaker Chemical research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Quaker Chemical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quaker Chemical's overall financial health at a glance.
Looking For More Investment Ideas Beyond Quaker Chemical?
If the Quaker Chemical story has sharpened your thinking but you want to widen your watchlist, the Simply Wall St Screener can help you scan for other opportunities that fit your style and risk tolerance.
- For investors who care most about capital strength and fewer financial surprises, start with our 31 resilient stocks with low risk scores that have historically paired resilience with measured risk profiles.
- If dependable income is your priority, focus on companies in our 7 dividend fortresses that combine higher yields with more durable payout histories.
- When you want to get ahead of the crowd, search through our 21 high quality undiscovered gems that show solid fundamentals yet receive relatively limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com