


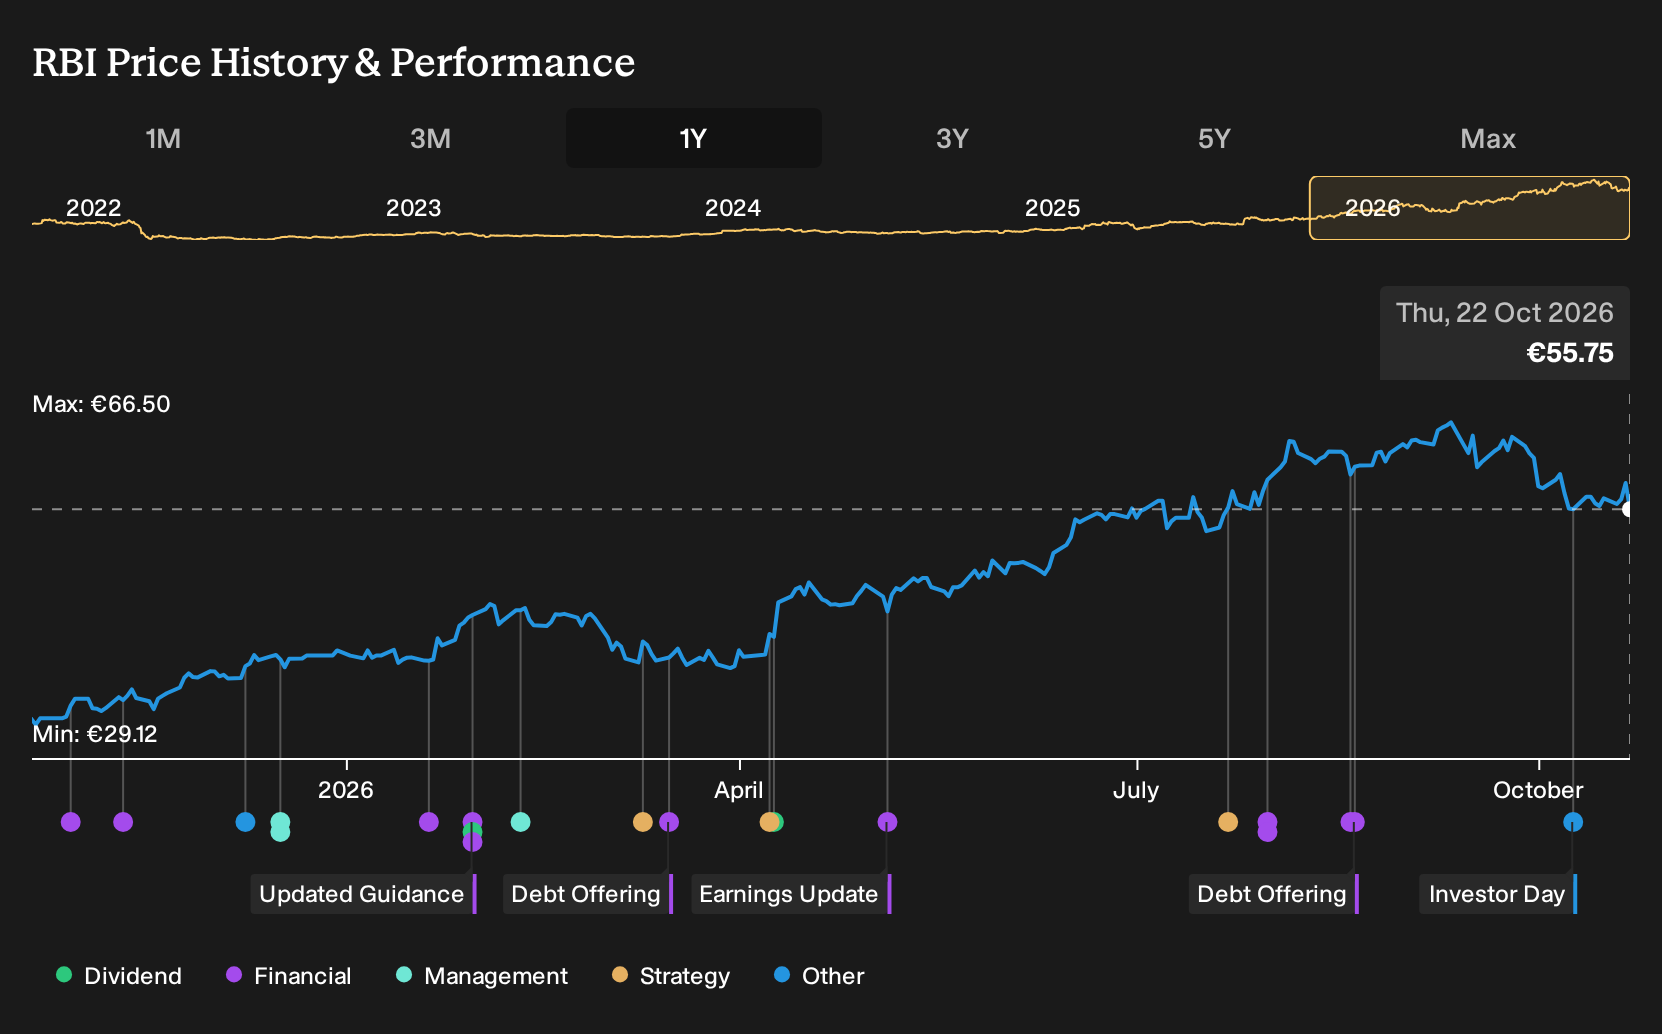
If you only glanced at the headlines on Raiffeisen Bank International this year, the mix of sanctions accusations, courtroom battles and Balkan acquisitions hardly suggested a smooth ride. For Raiffeisen Bank International shareholders, the return over the past year was 93.3%, including dividends. If you had been weighing those bullish and bearish analyst cases back in October 2025, how would you have judged that payoff against the very real Russia and regulatory risks on record then?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Raiffeisen Bank International. Zero in on 196 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Raiffeisen Bank International
The shares cost €29.12 at the start of the period, and Raiffeisen Bank International sat between two cleanly defined stories that both looked plausible on the numbers.
On the bullish side, the June 2025 Narrative put Fair Value at €30.71, anchored to the idea that Central and Eastern European prosperity and digital banking could support higher margins, with profit margins assumed to climb from 7.1% to 30.8% even while revenue was expected to decline 2.5% a year.
The October 2025 bear case set Fair Value at €26.88 and stressed that Russia exposure, litigation and regional volatility could bite, with revenue assumed to fall 4.4% annually and profit margins only reaching 22.4% while the shares might trade on a 6.3x P/E in three years.
What The Results Changed For Raiffeisen Bank International
Raiffeisen Bank International moved the argument from theory to hard numbers when Q2 2026 net income reached €754 million, compared with a loss of €586 million in Q2 2025, and net margin shifted from a loss of 26.0% to a positive 32.8%. That profitability swing leaned toward the bullish case on margins, although Russia sanctions allegations and exit obstacles kept the cautious narrative alive. Overall, the evidence cut both ways.
The key assumption here was that higher profitability would come from stronger margins, not just higher revenue. When you assess another bank, track whether net income and net margin actually move toward the scenario analysts set out, then weigh any legal or regulatory setbacks that might pull those numbers back.
What Raiffeisen Bank International's Price Now Asks You To Believe
Raiffeisen Bank International now trades at €55.75, and the selected Narrative puts its Fair Value below that level based on concerns around capital strain from litigation, sanctions scrutiny and integration costs on recent deals.
A buyer today effectively backs core returns improving beyond current guidance. The key question is how those legal and regulatory risks might affect that path.
"Although Raiffeisen Bank International is using its high CET1 ratio to buy Garanti Romania and Addiko, the need to fund ongoing Polish FX mortgage provisions of about €220 million in 2026 and only gradual reductions in 2027 and 2028 could absorb more capital than expected and mute the earnings uplift that investors are counting on from these deals, pressuring ROE and group net income."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking Beyond Raiffeisen Bank International
Raiffeisen Bank International shows how capital, risk and regulation collide in banking. Nearby, another institution faces a different set of trade offs.
Your attention may be on sanctions and contested margins. Large global lenders also wrestle with heavy spending on technology, compliance and marketing.
One giant in the sector leans into those higher costs. It backs expanded payments, securities processing and balance sheet growth to support that choice.
It is also channeling money into AI infrastructure, security and critical supply chains. That effort could reshape where future fee and interest income cluster.
If Raiffeisen Bank International sits at the sharp end of regulatory friction, this other bank leans into scale. The puzzle is how long that cost and revenue balance holds.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 25% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com