


- MillerKnoll confirmed Jeff Stutz as permanent CEO and added him to the Board after his interim tenure, formalizing leadership that spans prior COO and CFO roles across operations, finance, and international brands.
- Investors now have a long serving insider running MillerKnoll who has already been steering cost control, production discipline, and margin focused decisions during a tougher macro backdrop.
- This article examines how MillerKnoll's investment narrative around cost discipline and retail execution may evolve under Jeff Stutz's confirmed leadership.
MillerKnoll Investment Narrative Recap
To own MillerKnoll, you need to believe the cost focused playbook can keep supporting profit quality while the portfolio leans on Global Retail, International Contract and a still pressured North America Contract arm. Jeff Stutz now owns that script as confirmed CEO and director. As a result, the near term story hinges on operating discipline rather than a leadership reset.
The most important short term swing factor remains order health in North American Contract, especially across healthcare and U.S. public sector projects, with tariffs and input costs still biting at margins. Leadership continuity does not materially change that risk. However, it may help execution around pricing actions, footprint use and inventory control.
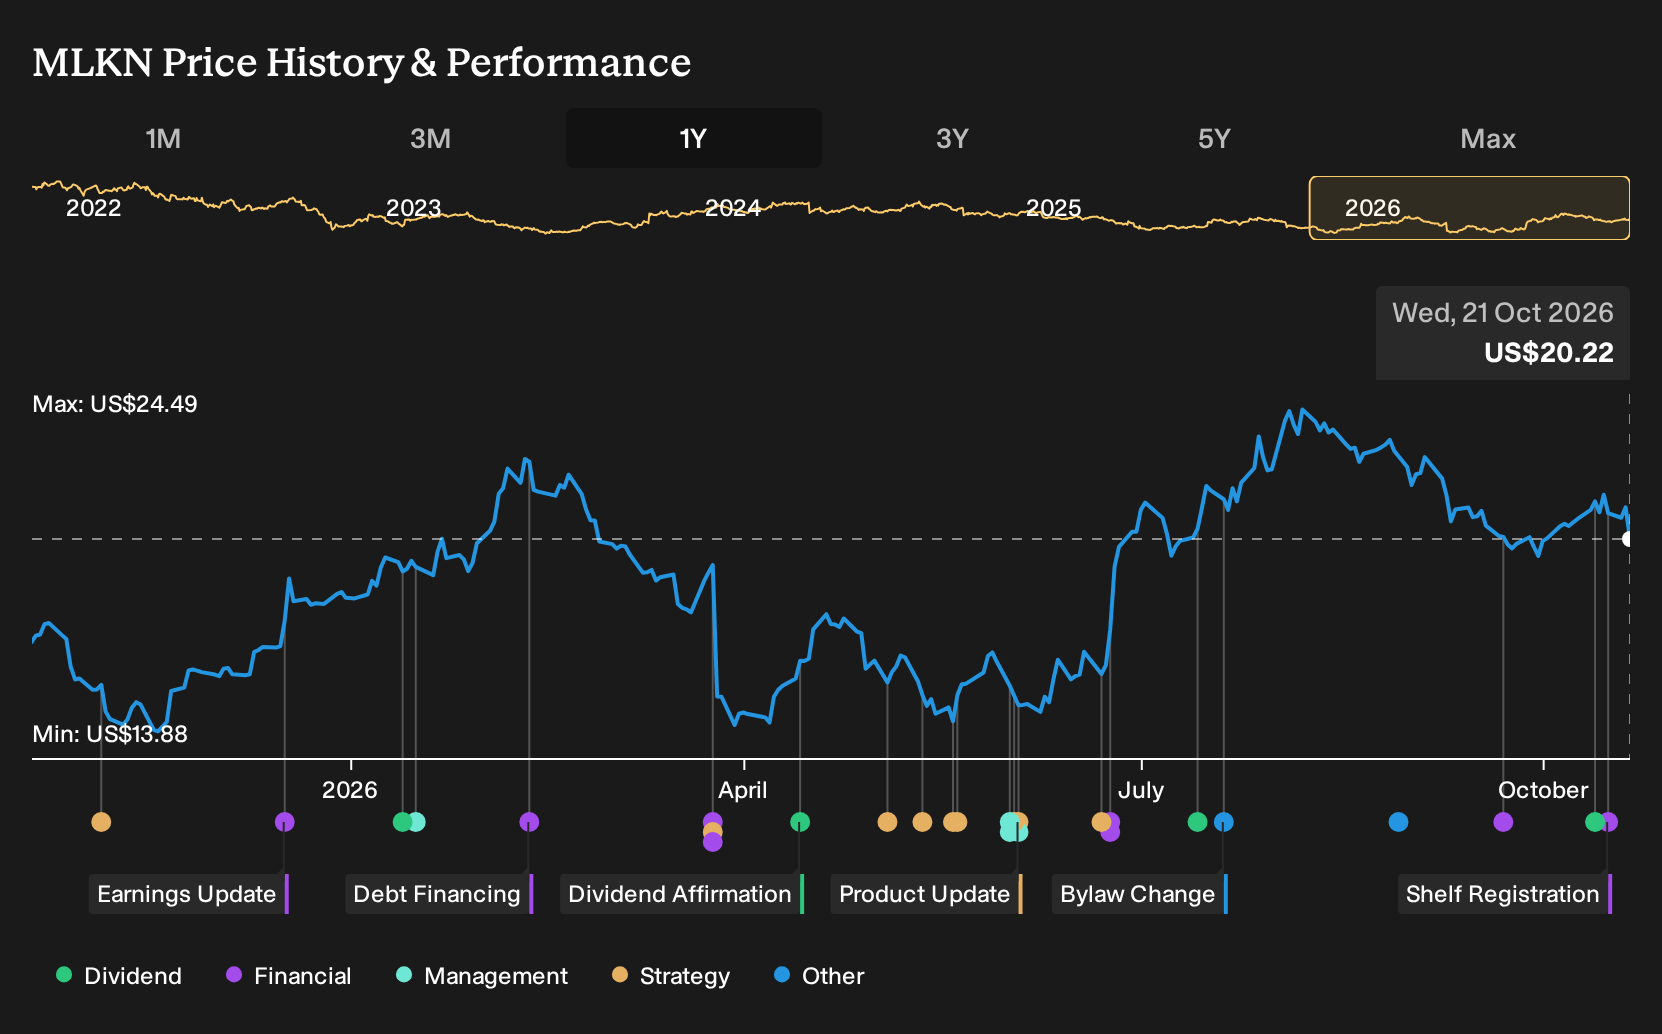
The dividend affirmation at US$0.1875 per share for January 2027 is the announcement that ties closest to this leadership decision. It signals MillerKnoll is keeping a regular cash return in place while the new CEO focuses on expenses, production levels and margin protection, rather than resetting capital allocation around the appointment.
For you, that payout sits beside the firm’s debt coverage and unstable dividend history, so it cuts both ways. On one side it adds a tangible cash component to the investment case as management talks about profitability and shareholder value. On the other, it keeps pressure on cash generation at a time when tariffs, softer orders and higher risk funding still hang over the story.
MillerKnoll's narrative projects US$4.3b revenue and US$180.7 million earnings by 2029. This assumes 4.1% yearly revenue growth and an earnings increase of about US$82.8 million from the current US$97.9 million level.
Uncover why MillerKnoll's fair value indicates a 63% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community only has two fair value views on MillerKnoll, yet they already span from about US$27.71 to US$33 per share. That narrow sample still shows how sharply opinions can diverge. When you consider tariff risk, softer North American Contract orders, and international expansion efforts, you get a far broader performance debate.
Explore another MillerKnoll fair value estimate, including one that suggests as much as 63% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MillerKnoll research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MillerKnoll. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MillerKnoll's overall financial health at a glance.
Looking for more investment ideas beyond MillerKnoll?
If the MillerKnoll story has sharpened your thinking, use that momentum to broaden your watchlist. The Simply Wall St Screener lets you filter for different qualities across the market so you can line up a few contrasting options and stress test your thesis before committing fresh capital.
- If you want potential value with quality behind it, start with companies that combine strong cash flows and balance sheets using our curated 33 high quality undervalued stocks.
- If resilience matters more than excitement right now, filter for businesses with sturdier risk profiles through the focused 31 resilient stocks with low risk scores.
- If you prefer to get in early on less followed ideas, cast a wider net over financially solid yet quieter opportunities with the targeted 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com