


Why Alliant Energy’s latest grid program matters for shareholders
Alliant Energy (LNT) just expanded its Smart Hours program in Wisconsin, letting customers with FranklinWH battery systems earn incentives by sending stored power back to the grid during peak demand.
Recent price action has been steadier than the headlines. Alliant Energy’s share price return is up 5.26% over the past 30 days and 4.27% year to date, while its 3 year total shareholder return of 52.70% points to longer term momentum that short term dips, such as the 8.10% decline over 90 days, have not erased.
Scan a curated field of regulated utilities and infrastructure peers by checking the 42 power grid technology and infrastructure stocks that could benefit from similar grid reliability and battery programs to Alliant Energy.
After a 5.26% move in 30 days and a 3 year total return of 52.70%, Alliant Energy now sits near US$68.39. Investors considering the shares at this price may want to weigh the potential benefits of waiting for a pullback against the advantages of starting to build a position at this level and sizing it carefully.
Most Popular Narrative: 10% Undervalued
Against a last close of $68.39, the most followed narrative pegs Alliant Energy’s fair value at about $76.29. This frames the current Smart Hours expansion inside a wider long term capital and earnings story built around large new power users.
The accelerating construction and onboarding of large-scale data centers under five executed electric service agreements totaling about 3.4 GW of contracted demand, plus a further 2 to 4 GW pipeline of large-load opportunities, points to a multi year step up in Alliant Energy’s electricity sales and regulated revenue base as these projects ramp through 2031.
See why 5 investors see Alliant Energy as 10% undervalued.
Result: Fair Value of $76.29 (UNDERVALUED)
Still, the Alliant Energy story leans heavily on a concentrated data center pipeline, and higher project and maintenance costs could erode the earnings path that analysts are modeling.
Find out about the key risks to this Alliant Energy narrative.
Another view on Alliant Energy’s valuation
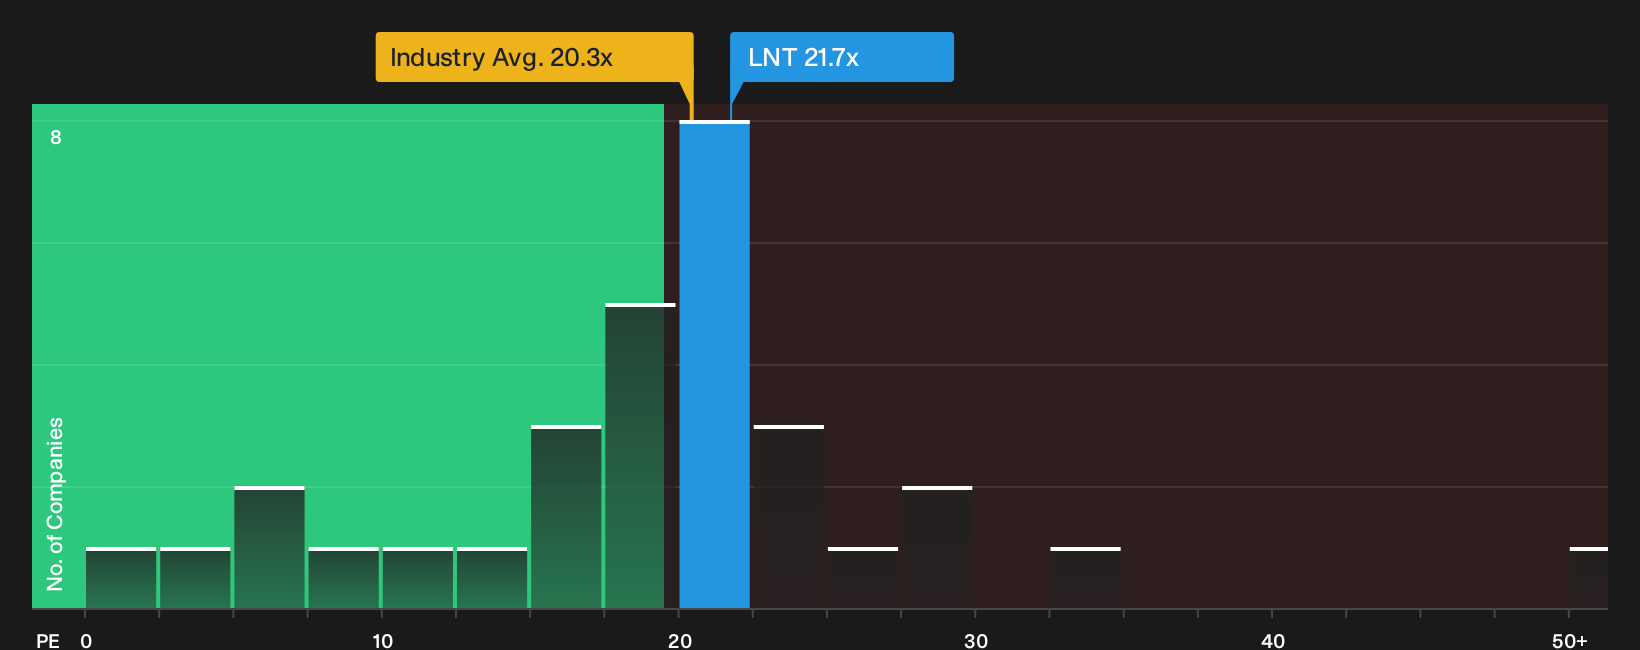
The first narrative leans on analyst fair value of $76.29, yet the market is already paying up on simple P/E math. Alliant Energy trades at about 21.7x earnings, compared with 20.4x for both the US electric utilities sector and its own fair ratio. This points to some valuation stretch that could matter if sentiment cools.
See what the numbers say about this price in more detail by reading the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and concern around Alliant Energy feels finely balanced, act while sentiment is split and test the data yourself. To frame that view against both upside and downside signals, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Alliant Energy?
Do not stop with one utility. Put a small amount of time into scanning fresh opportunities now so you do not regret missed ideas later.
- Target resilience first and review a 31 resilient stocks with low risk scores that highlights companies with steadier risk profiles when markets feel choppy.
- Hunt for mispriced quality and scan a 33 high quality undervalued stocks that filters for strong fundamentals at prices that may leave room for upside.
- Spot under-the-radar potential and scan a 21 high quality undiscovered gems that surfaces lesser known businesses with solid financial traits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com