


1st Source (SRCE) heads into Thursday’s after hours earnings release with fresh attention on the stock, as analysts recently lifted EPS forecasts and pointed to the bank’s track record of topping quarterly projections.
At around $85.81 per share, 1st Source has delivered a 37.38% year-to-date share price return and a 46.09% total shareholder return over the past 12 months. This performance signals building momentum that reflects improving sentiment ahead of this earnings update.
Scan for other regional banks that show similar earnings momentum and sentiment shifts using the curated 21 high quality undiscovered gems alongside 1st Source ahead of this report.
The market has pushed 1st Source sharply higher, yet the shares still trade below both intrinsic value estimates and analyst targets. Is that discount a sign of lingering caution that makes sense, or mispricing that does not?
Preferred P/E of 12.2x for 1st Source: Is it justified?
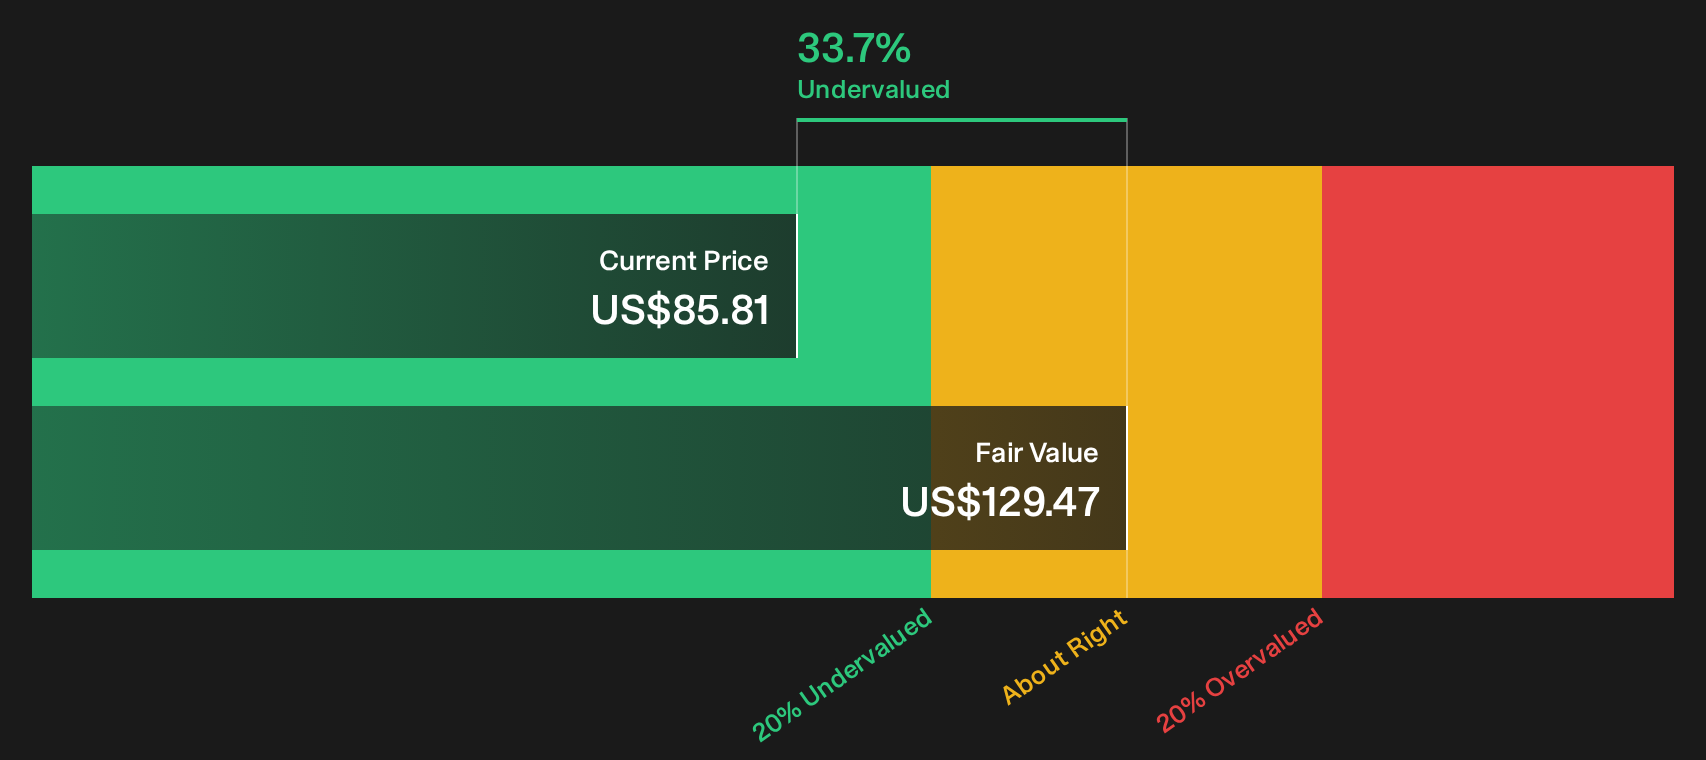
At $85.81 per share, 1st Source trades on a P/E of 12.2x, which is higher than both the wider US Banks industry at 11.5x and the closer peer group at 10.9x. That premium sits alongside an internal estimate that the stock trades 33.7% below fair value based on future cash flows.
The P/E ratio compares the current share price with earnings per share and is a common way to gauge how much investors are paying for each dollar of profit. For a regional lender like 1st Source, which reported earnings growth of 7.5% per year over the past 5 years and 20.9% over the last year, this metric helps you judge how the market is pricing that profit record relative to other banks.
Forecasts suggest 1st Source earnings are expected to grow at 2.9% per year, slower than the broader US market at 16.9% per year, and revenue is projected to increase 4.6% annually, also behind the US market at 13.4% per year. In that context, the P/E of 12.2x is meaningfully higher than the estimated fair P/E of 10.6x. This points to a level the multiple could move toward if sentiment cools or growth expectations are reassessed.
Explore the SWS fair ratio for 1st Source.
Result: Price-to-Earnings of 12.2x (OVERVALUED)
Still, 1st Source depends heavily on the US commercial cycle and credit quality, so a weaker lending backdrop or rising impairments could quickly challenge today’s upbeat narrative.
Find out about the key risks to this 1st Source narrative.
Another view on 1st Source valuation
The P/E workup presents 1st Source as expensive, yet the SWS DCF model points in the opposite direction. With the share price at $85.81 and the model suggesting a future cash flow value of $129.47, the framework labels the stock as undervalued. Which lens do you trust more for the long term?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out 1st Source for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment running this warm around 1st Source, do you want to simply watch or test the numbers yourself and move fast before views settle? To see why some investors remain optimistic, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond 1st Source?
If you only stop at 1st Source, you risk missing other setups that fit your style, time horizon, and risk limits across the market.
- Target potential mispricing across quality companies by scanning the 32 high quality undervalued stocks that pair solid fundamentals with below-estimate pricing.
- Prioritize resilience and sleep-better-at-night positions by focusing on the 31 resilient stocks with low risk scores that screen for sturdier financial profiles.
- Strengthen your watchlist with businesses that carry healthier balance sheets using the list of solid balance sheet and fundamentals (25 results) to spot sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com