


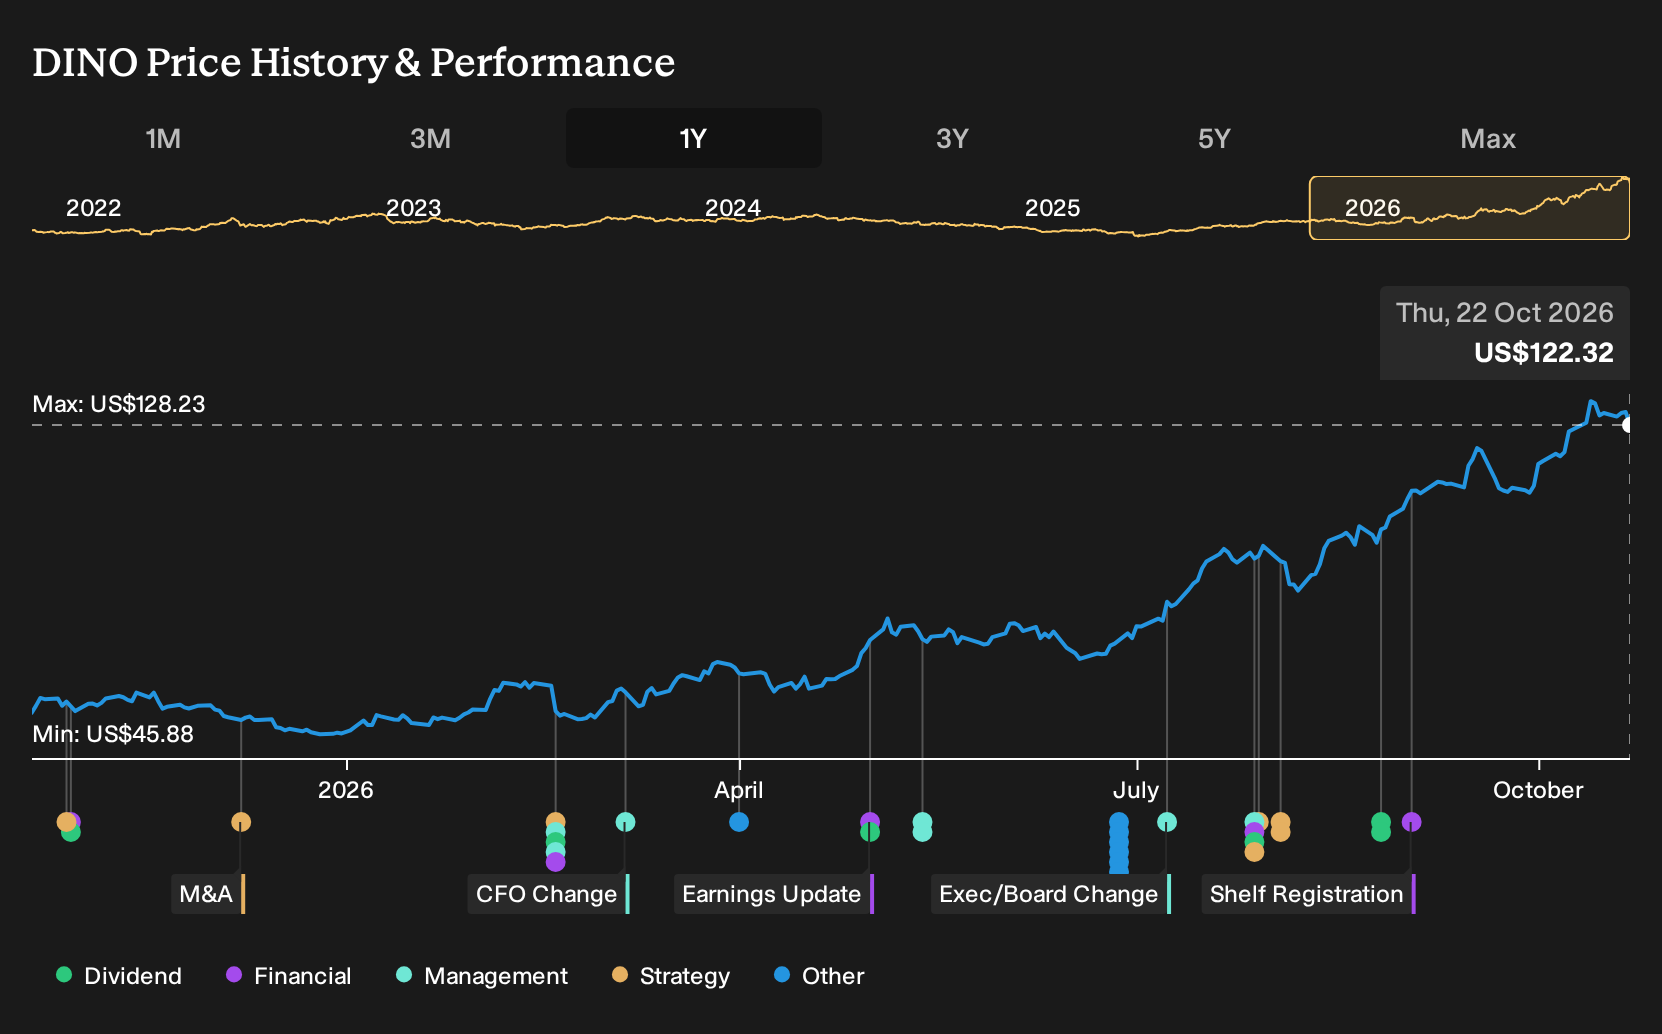
- HF Sinclair is preparing to report quarterly results for the period ended September 2026, with analysts expecting higher earnings and revenue than a year earlier.
- The plan to spin off the Lubricants & Specialties segment into a separate public company by the second half of 2027 could reshape HF Sinclair's capital needs and business mix.
- This article examines how HF Sinclair's investment narrative is influenced by the planned Lubricants & Specialties separation and the upcoming earnings report.
Compare HF Sinclair's setup ahead of earnings and the Lubricants & Specialties spin with other potential breakouts in refining and energy by scanning the 32 high quality undervalued stocks that share similar fundamentals.
HF Sinclair Investment Narrative Recap
Owning HF Sinclair means backing a refiner that is trying to turn a strong cycle into steadier cash flows across refining, renewables, midstream, and Lubricants & Specialties. The near term story revolves around how well current refining margins and renewable diesel utilization hold up while the business leans on its existing asset base.
The upcoming September quarter report is the key short term catalyst because it shows whether earnings still justify the recent share price strength. The biggest risk remains execution and policy pressure, from Renewable Fuel Standard costs to leadership turnover, and the latest earnings print is unlikely to materially change those issues on its own.
The planned separation of the Lubricants & Specialties unit into a standalone listed entity is the announcement that most directly intersects with this earnings setup. That segment generated US$2,896m of revenue and is targeted to deliver roughly US$300m to US$350m of annual EBITDA, so how it is carved out matters for HF Sinclair’s mix.
Investors now have to think about earnings quality as well as earnings level. The breakup plan, combined with Go West and Western Gateway projects, ties the medium term outlook to execution on lower capital intensity, fee based cash flows while still managing long term demand risks from electric vehicles and regulatory costs around RINs.
HF Sinclair's analyst narrative points to revenues of US$30.4b and earnings of US$1.3b by 2029. Earnings today are US$1.9b, and analysts expect an earnings decrease of US$0.6b from that level, while broadly assuming revenue remains fairly flat over the period.
Uncover why HF Sinclair's fair value indicates a 7% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate take on HF Sinclair leans heavily on timing risk around the Go West build out. The most bearish analysts were pencilling in 3 year revenue falling toward US$26.8b by 2029 with earnings near US$1.2b, far below consensus. Those pre news forecasts show how sharply views can differ, so it is worth exploring several angles before reacting.
Explore 4 other HF Sinclair fair value estimates, including one that suggests as much as 31% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own perspective.
- A great starting point for your HF Sinclair research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for HF Sinclair. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HF Sinclair's overall financial health at a glance.
Looking For More HF Sinclair Investment Ideas?
If HF Sinclair has sharpened your focus on where capital and cash flows might head next, it can be useful to line it up against a broader watchlist of opportunities that share similar qualities or offer something very different for your portfolio.
- For investors hunting for strong balance sheets and resilient fundamentals, start with a curated list of solid balance sheet and fundamentals (25 results) that can complement or contrast what you see in HF Sinclair.
- If you want potential income alongside capital appreciation, scan a focused group of 7 dividend fortresses that aim to combine yield with durability.
- For those searching for mispriced quality, compare HF Sinclair with a curated pool of 21 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com