


As Asian markets navigate the complexities of global economic shifts, including inflation pressures and geopolitical tensions, investors are increasingly focusing on companies with strong growth potential and substantial insider ownership. In this context, identifying growth companies in Asia that combine robust revenue expectations with high insider stakes can offer a compelling investment narrative amidst ongoing market uncertainties.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Meitu (SEHK:1357) | 23.1% | 26.7% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Fulin Precision (SZSE:300432) | 11.7% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
Let's review some notable picks from our screened stocks.
Doosan (KOSE:A000150)
Simply Wall St Growth Rating: ★★★★☆☆
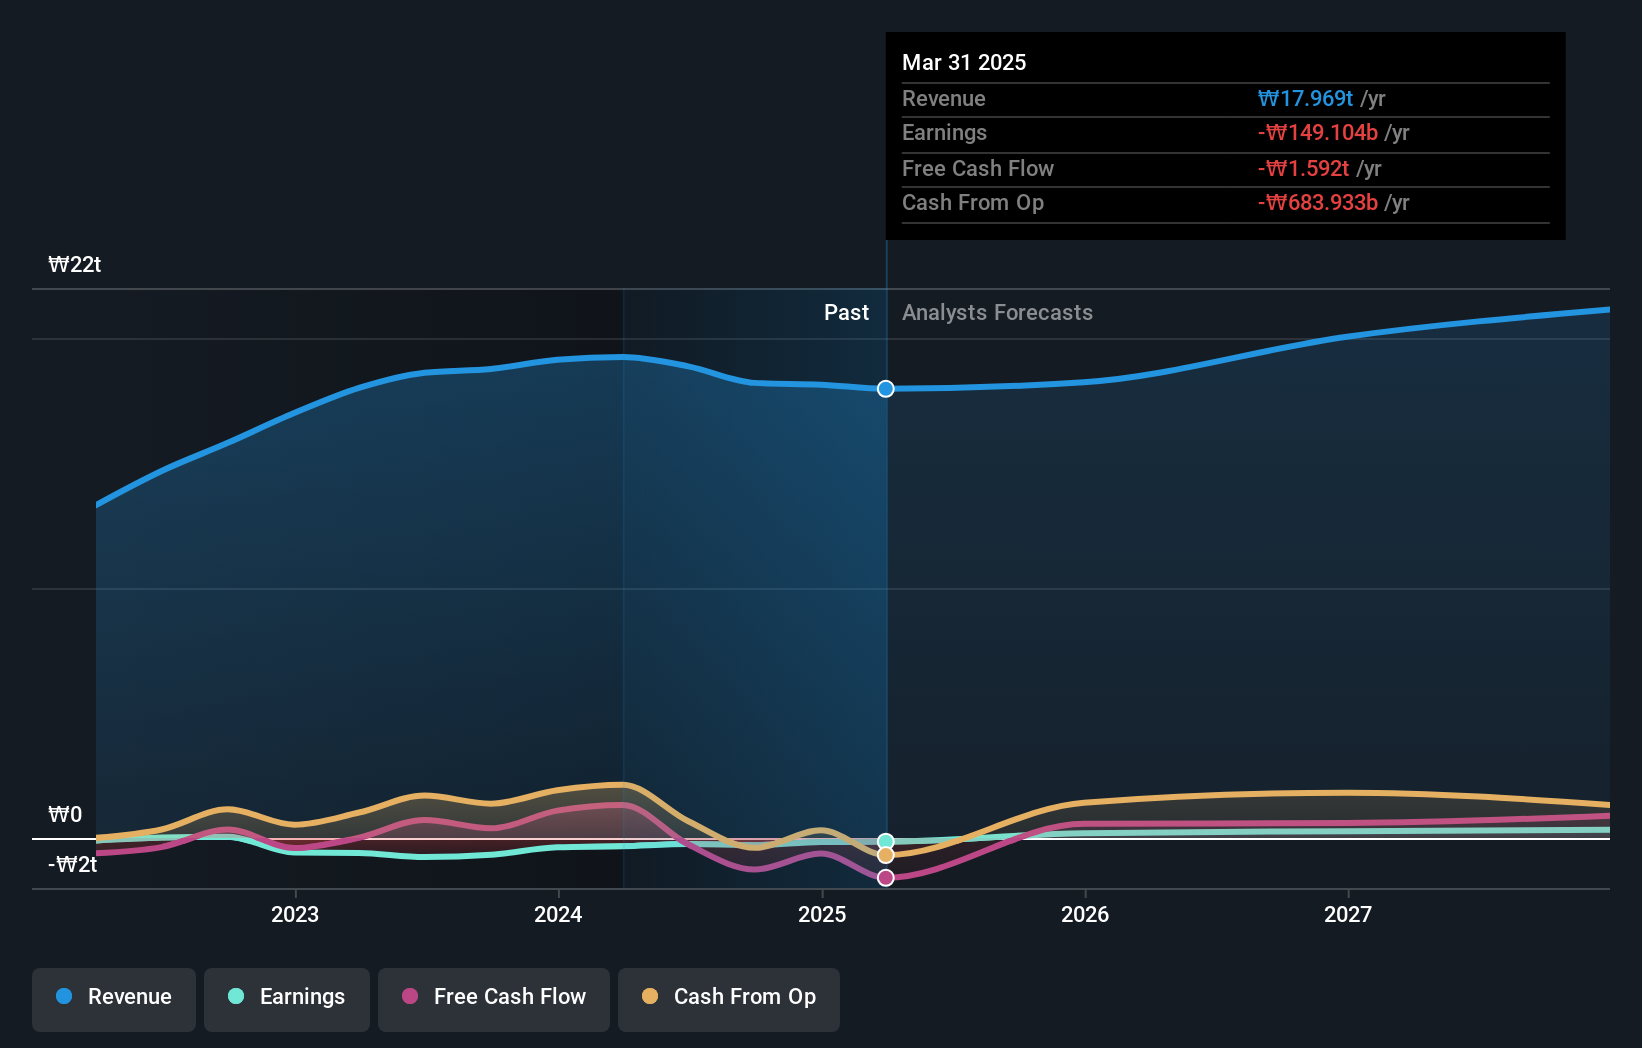
Overview: Doosan Corporation, along with its subsidiaries, operates in power generation facilities, industrial facilities, construction machinery, engines, and construction sectors across Korea and internationally, with a market cap of approximately ₩15.19 trillion.
Operations: The company's revenue segments include Doosan Bobcat at ₩9.19 billion, Doosan Energy at ₩8.28 billion, Electronic BG at ₩2.29 billion, Doosan Fuel Cell at ₩415.69 million, and Digital Innovation BU at ₩317.10 million.
Insider Ownership: 37.1%
Revenue Growth Forecast: 13.1% p.a.
Doosan Corporation's recent inclusion in the S&P Global BMI Index underscores its growing prominence. Despite a decline in sales to KRW 194.56 billion for Q2, net income surged to KRW 355.15 billion, reflecting strong profitability growth. Earnings are expected to grow significantly at 40.35% annually, outpacing the Korean market's average of 28.3%. However, revenue growth is forecasted slower than the market at 13.1%. The stock trades well below fair value estimates and has high return on equity projections of 26.4%.
- Take a closer look at Doosan's potential here in our earnings growth report.
- According our valuation report, there's an indication that Doosan's share price might be on the cheaper side.
Shenzhen Sunway Communication (SZSE:300136)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Shenzhen Sunway Communication Co., Ltd. focuses on the research, development, manufacture, and sale of antennas and modules, wireless charging modules, EMI/EMC devices, precision connectors, and acoustic devices both in China and internationally with a market cap of CN¥42.85 billion.
Operations: The company generates revenue primarily from its electronic component segment, totaling CN¥9.24 billion.
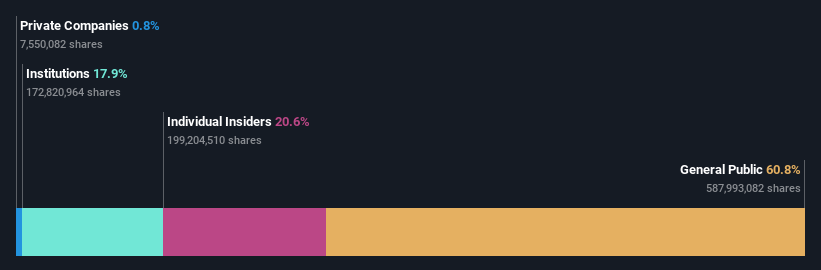
Insider Ownership: 19.7%
Revenue Growth Forecast: 23.5% p.a.
Shenzhen Sunway Communication's earnings are forecasted to grow significantly at 37.4% annually, surpassing the Chinese market average of 26.6%. Revenue is expected to increase by 23.5% per year, outpacing the market's 16.3%. Despite recent volatility in share price and a slight decline in net income to CNY 150.52 million for H1 2026, substantial insider ownership remains a key feature supporting its growth narrative in Asia.
- Get an in-depth perspective on Shenzhen Sunway Communication's performance by reading our analyst estimates report here.
- Our valuation report here indicates Shenzhen Sunway Communication may be overvalued.
POCO Holding (SZSE:300811)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: POCO Holding Co., Ltd. focuses on the research and development of soft magnetic powder, soft magnetic powder cores, and chip inductors across Hong Kong, Macao, Taiwan, and international markets with a market cap of CN¥27.52 billion.
Operations: The company generates revenue primarily from its Electronic Components segment, which accounts for CN¥2.12 billion.
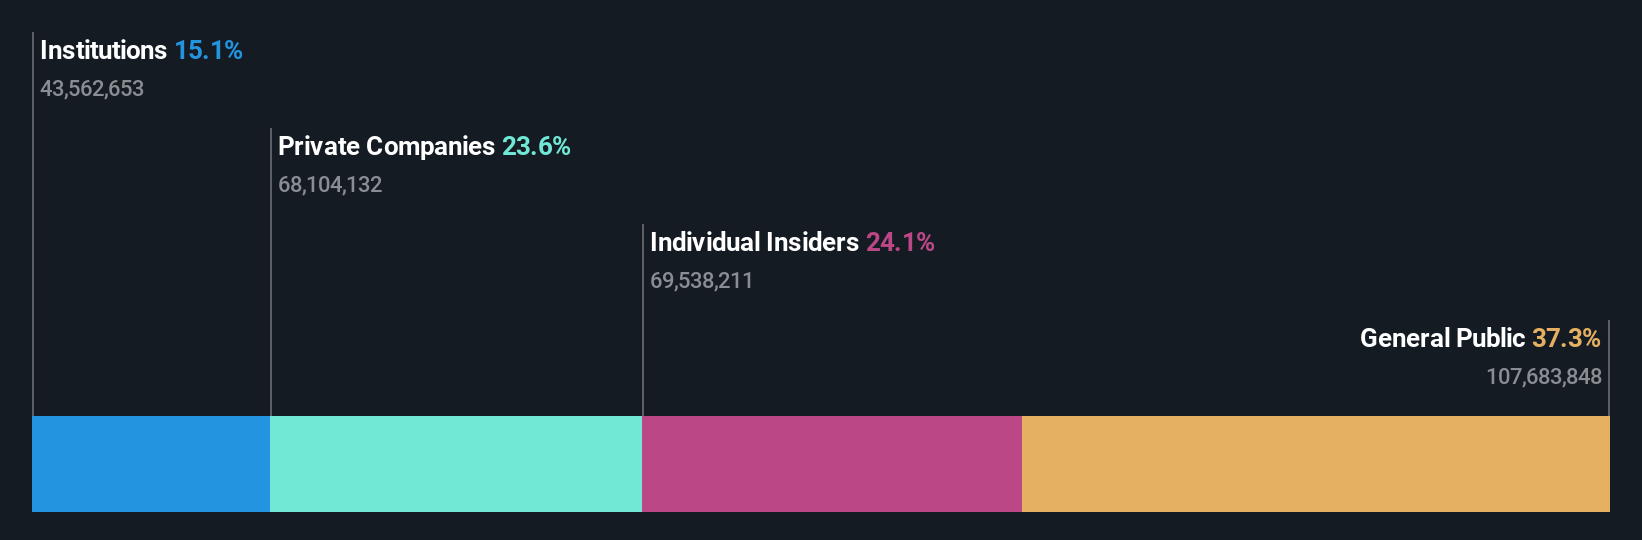
Insider Ownership: 24%
Revenue Growth Forecast: 21.6% p.a.
POCO Holding's revenue is forecast to grow at 21.6% annually, surpassing the Chinese market average of 16.3%, while earnings are expected to increase by 21.95% per year, albeit slower than the market's 26.6%. Recent financials show a rise in net income to CNY 225.64 million for H1 2026 from CNY 191.3 million a year ago, alongside a completed share buyback of CNY 95.81 million, indicating strategic financial maneuvers amidst high insider ownership.
- Dive into the specifics of POCO Holding here with our thorough growth forecast report.
- According our valuation report, there's an indication that POCO Holding's share price might be on the expensive side.
Taking Advantage
- Embark on your investment journey to our 510 Fast Growing Asian Companies With High Insider Ownership selection here.
- Looking For Alternative Opportunities? These 24 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com