


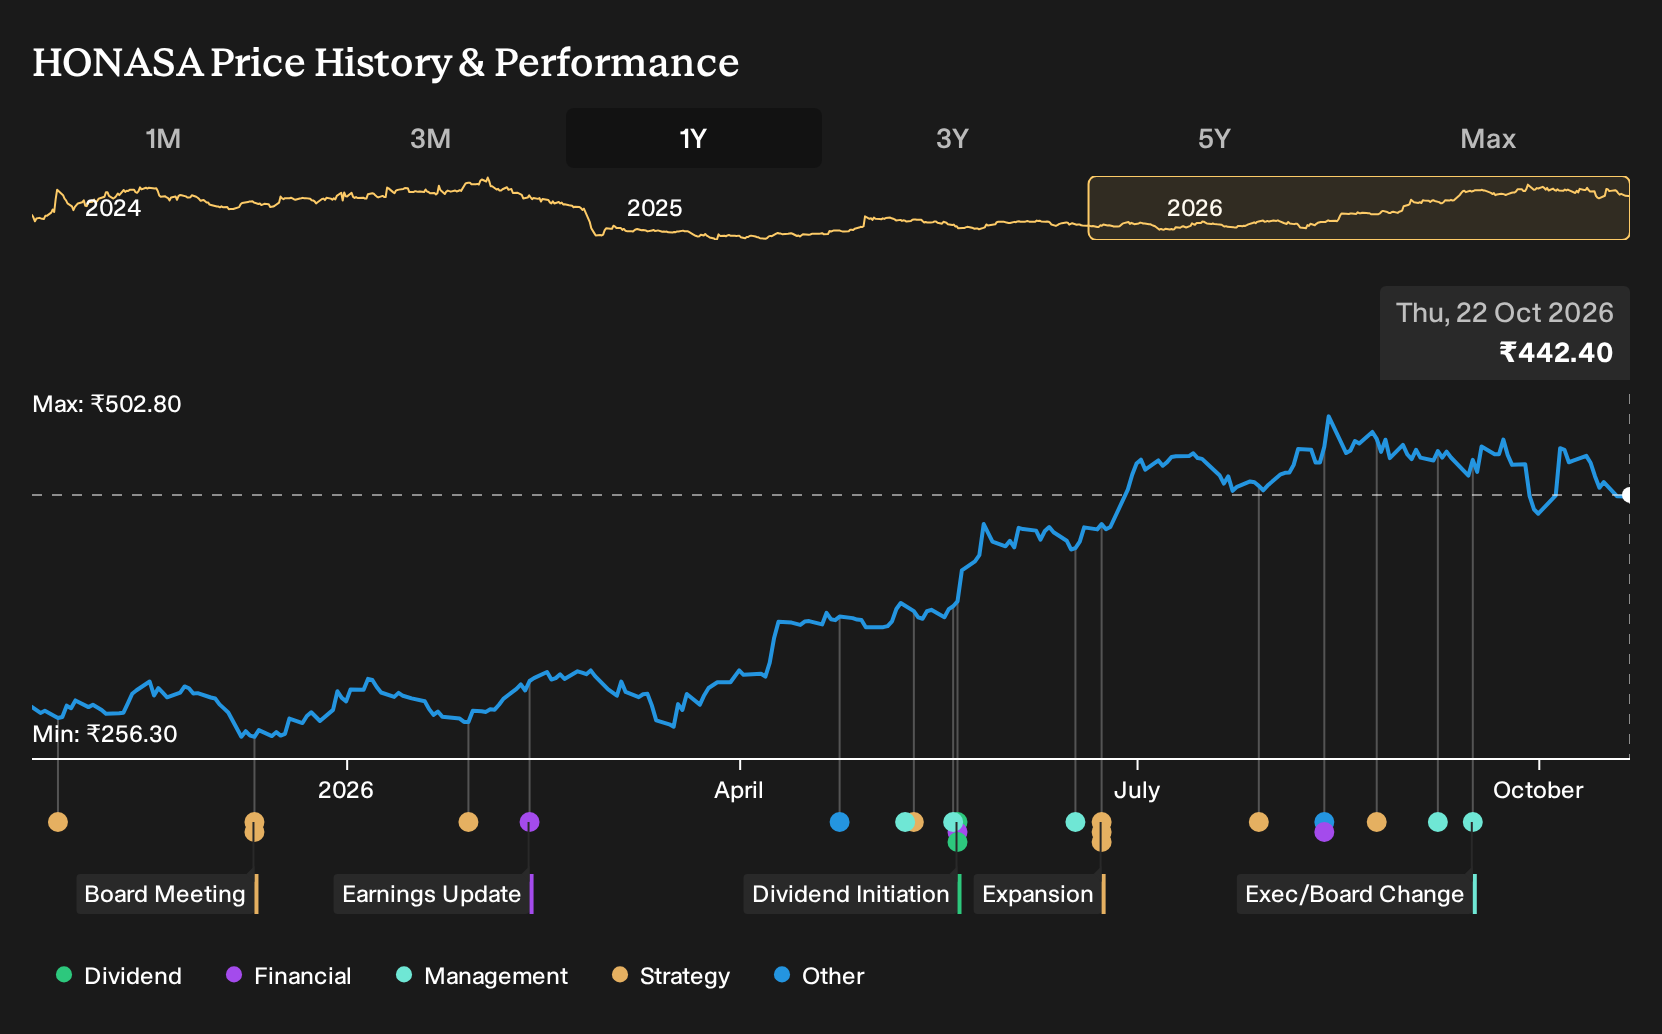
If you had been weighing Honasa Consumer in October 2025, the split between a bullish ₹400 view and a bearish ₹197 stance framed a very real fork in the road. Holding Honasa Consumer over the past year would have returned 62.1%, including dividends. That outcome now sits beside fresher numbers, with revenue of ₹7,559.46m and net income of ₹902.49m in Q1 2027. This leaves one core question: If you faced the same disagreement again, what would matter most in that decision?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Honasa Consumer. Zero in on 191 high quality undervalued stocks for companies trading below our estimates.
What Honasa Consumer Investors Were Really Arguing About
The shares cost ₹279 at the start, which put you between two clean stories about what Honasa Consumer might become.
The bullish narrative pinned Fair Value at ₹400 and leaned on rapid expansion in digital and offline reach, as well as a push into high-margin categories like acne care and peptide-based hair care to support stronger profitability.
The bearish case set Fair Value at ₹197 and focused on rising regulatory scrutiny on product formulations and heavier reliance on platforms such as Google and Meta as key threats to margins and earnings quality.
What The Results Changed For Honasa Consumer
The clearest new fact was Honasa Consumer posting revenue of ₹7,559.46m and net income of ₹902.49m in Q1 2027, compared with ₹5,952.54m and ₹413.25m in Q1 2026. Net margin moved from 6.9% to 11.9%. That pattern gave more weight to the optimistic view on profitability, although it did not fully settle the long term regulatory and platform risk worries.
The fight between the July 2025 bull and bear cases turned on whether higher marketing and compliance costs would crush earnings. For any other stock, you would want to track reported net margin next to acquisition spending and ad intensity to see if the profit story is actually showing up in the income statement.
What Today's Honasa Consumer Price Already Assumes
Honasa Consumer now trades at ₹442 after a 62.1% gain over the past year. The selected Narrative’s Fair Value sits below this level, reflecting a view that the recent share price already bakes in ambitious progress.
The focus has shifted from regulation to whether newer wellness, fragrance and offline bets can scale cleanly. Anyone paying ₹442 is effectively assuming that margin goals can be met without portfolio sprawl or offline drag undermining that path.
"Key Takeaways: Bearish analysts expect Honasa Consumer to see rising regulatory, competitive, and digital channel pressures that eventually cap the benefits from current revenue, margin, and cash generation levels. The main thing that has to go right is that Honasa Consumer converts its expansion into wellness, fragrances, and offline distribution into durable category leadership, without allowing acquisitions and a broader brand portfolio to dilute focus on core profitability."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 35% below our estimate - turns shorter brownfield tieback projects into higher margin subsea orders and services.
- Company 2 - 30% below our estimate - uses one high grade mine to fund drilling that extends nearby production prospects.
- Company 3 - 44% below our estimate - shifts oncology clients from one off licenses to recurring software and AI planning fees.
That is three of the list. See every one of the 203 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com