


Inflation is biting again, energy prices are doing a lot of the heavy lifting, and that mix is quietly reshaping where money flows in the U.S. market. When gasoline and broader energy costs feed into CPI like this, some businesses come under pressure while others suddenly look more interesting. This article walks through three U.S. energy sector stocks exposed to that inflation story and explains how each one could matter for a portfolio now.
The three stocks covered next are just a sample, and the full screen on U.S. energy sector stocks surfaced 10 more companies with equally compelling narratives that are not broken out in this article.
To move straight from ideas to hard numbers, analyze and filter the full universe using the U.S. Energy Sector Stocks screener.
Natural Gas Services Group (NGS)
Natural Gas Services Group plugs directly into the U.S. Energy Sector Stocks theme through the plumbing of the gas system, renting and servicing compression gear that keeps production and processing volumes moving when demand and prices make infrastructure work harder.
Natural Gas Services Group focuses on renting, designing and servicing natural gas and electric compression equipment for U.S. oil and gas sites, with about US$182 million from rentals, US$2.8 million from sales and US$4.2 million from aftermarket services, and a market cap near US$408 million.
"The accelerating growth in global LNG exports and increasing demand from sectors like AI data centers and power generation are driving higher natural gas production, which directly benefits Natural Gas Services Group through strong contracted rental growth and high utilization of compression assets and can support future revenues and EBITDA."
What happens if a single cost pressure quietly eats into that rental economics story investors are counting on?
That single cost pressure is exactly what sits under the full narrative for Natural Gas Services Group, which shows how rental economics could shift if compression demand keeps accelerating beyond today’s contracts.

WhiteHawk Minerals (WHK)
WhiteHawk Minerals gives direct royalty exposure to U.S. natural gas in the Marcellus and Haynesville shales, earning about US$76.7 million from natural gas and oil minerals across the United States, and carries a market cap near US$687 million.
For investors focused on how the U.S. Energy Sector Stocks theme intersects with inflation and higher gas prices, WhiteHawk Minerals offers a cleaner way to tap into that story through royalties rather than drilling risk, which is exactly what the market has been watching.
"Growing natural gas demand from new power plants tied to data centers and AI, including 21 planned facilities around WhiteHawk Minerals' Appalachian position, is expected to support activity on its acreage and can influence long term royalty revenue and cash flow visibility."
The real swing factor is what happens to that royalty cash flow profile if one key assumption about future gas pricing and volumes does not hold.
If that core assumption matters to you, read the full narrative for WhiteHawk Minerals to see how inflation, volumes and data center demand could reshape the royalty story ahead.

RPC (RES)
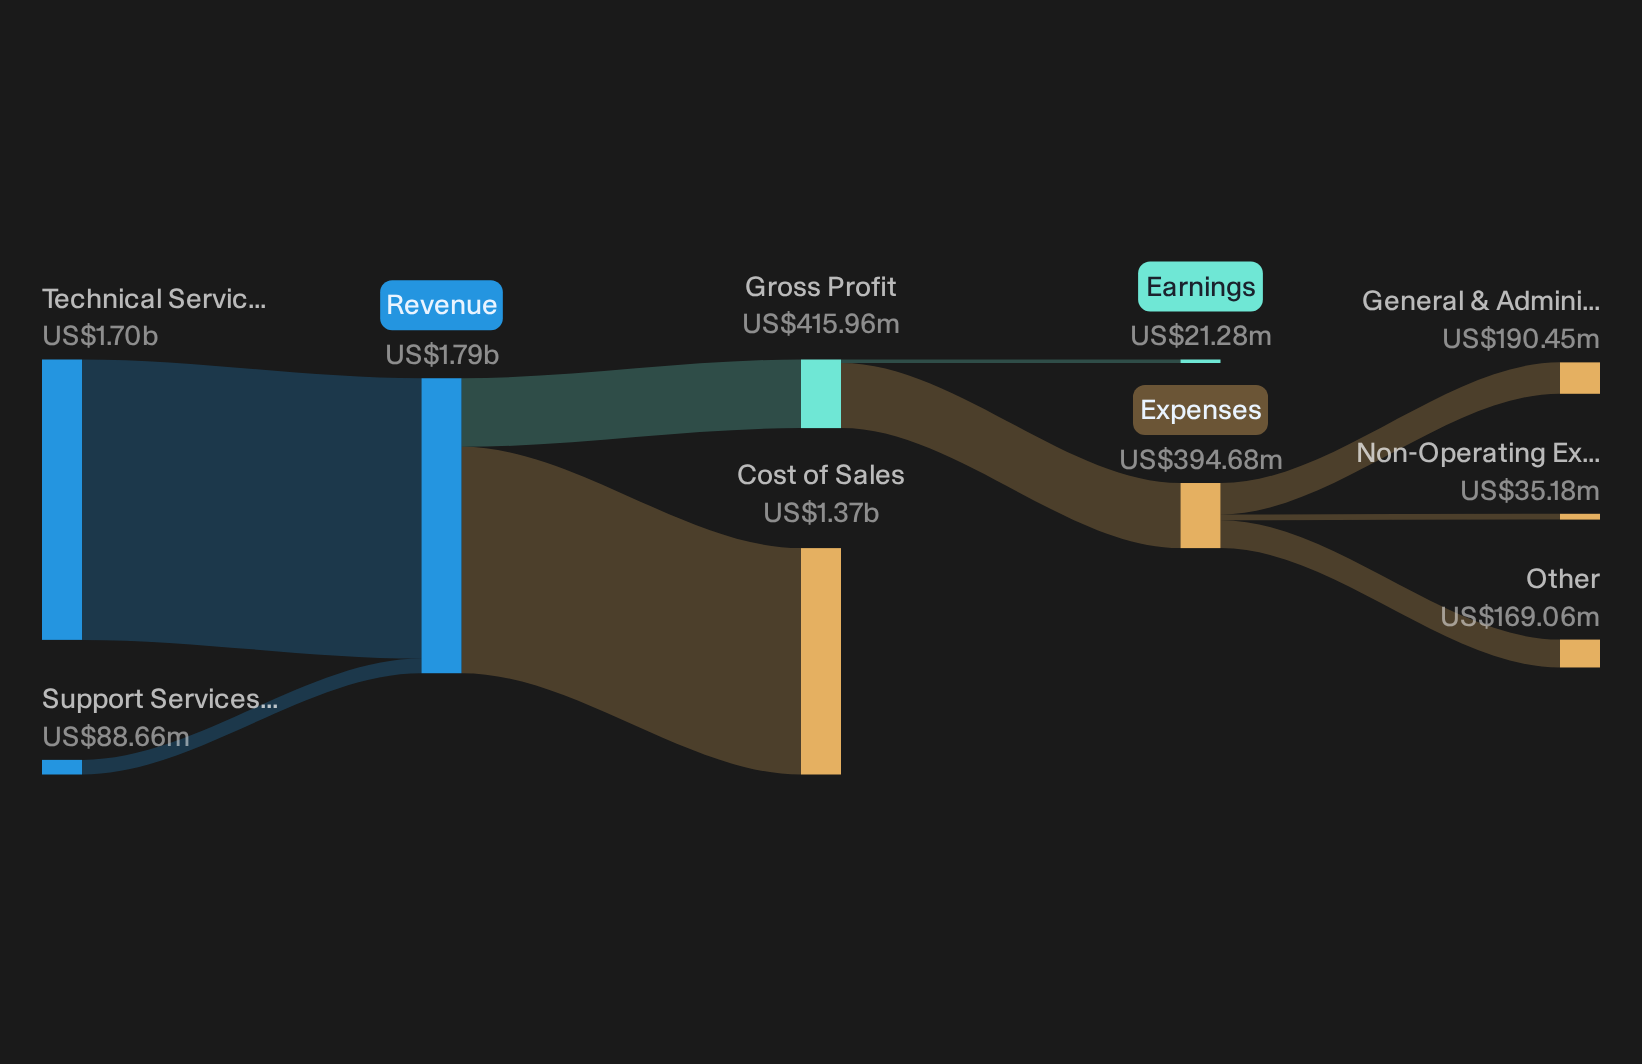
RPC plugs into the U.S. Energy Sector Stocks theme as a pure play on drilling and well activity, providing pressure pumping, downhole tools and rental drill pipe, with about US$1.7b from Technical Services, US$89 million from Support Services and a market value near US$1.4b.
For investors looking at how higher energy prices and stronger producer cash flows can spill over into service providers, RPC offers geared exposure to well completions, workovers and maintenance work rather than direct commodity pricing. This is why its operating mix and cost base now matter so much.
"Although Thru Tubbing Solutions is gaining share with tools like the Metal Max power section and A 10 motor, the Q1 2026 pattern where revenue rose to US$455 million while adjusted EBITDA margins compressed to 11.8% points to higher materials, supplies, fuel costs and lower other income consuming much of that growth."
What happens to RPC’s appeal in this inflation driven energy upswing depends on how one stubborn cost pressure reshapes that operating leverage story.
That inflection point is exactly where the full narrative for RPC pulls the story together and shows whether rising activity can overpower those stubborn costs or if pricing power stalls.
Seeking Alternatives Before The Crowd?
Fresh themes can break out fast while early momentum is still under the radar for now. Have a plan in place so you are prepared rather than reacting after prices move.
- Spot potential turnaround stories before they get front-page attention by scanning the 30 high quality undervalued stocks and see which fundamentals may still be overlooked while it matters.
- Focus on long term income trends instead of short bursts of yield by using the 7 dividend fortresses, which screens for staying power rather than short-lived payout spikes.
- Review the 42 power grid technology and infrastructure stocks to identify companies involved in grid upgrades and modernization so you can evaluate opportunities related to the next infrastructure buildout.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com