


If Williams Companies was on your watchlist instead of in your portfolio, the return may sting. Holding Williams Companies over the past year would have returned 23.5%, including dividends. That outcome may look surprising given the fierce split between bulls pointing to US LNG expansion and data center gas demand, and bears warning that heavy pipeline spending could be undercut by decarbonization policies. If you rewind to October 2025, could confidence in long-term US LNG export growth have been the key assumption to focus on?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
This theme extends beyond Williams Companies. See which of 42 power grid technology and infrastructure stocks may still merit a closer look.
The Two Williams Companies Narratives Investors Had To Weigh
The shares cost US$62.16 at the start of the period, and Williams Companies came with two very different stories attached.
The bullish Narrative set Fair Value at US$74, hinging on US LNG export expansion and data center gas demand feeding Williams’ Transco and Haynesville corridors, as well as contracted projects like Socrates and Power Express that were expected to support earnings and cash flow.
The bearish Narrative put Fair Value at US$43, stressing decarbonization policies and faster renewable adoption as a threat that could leave expensive new pipelines underused and raise the risk of stranded assets and weaker long term returns.
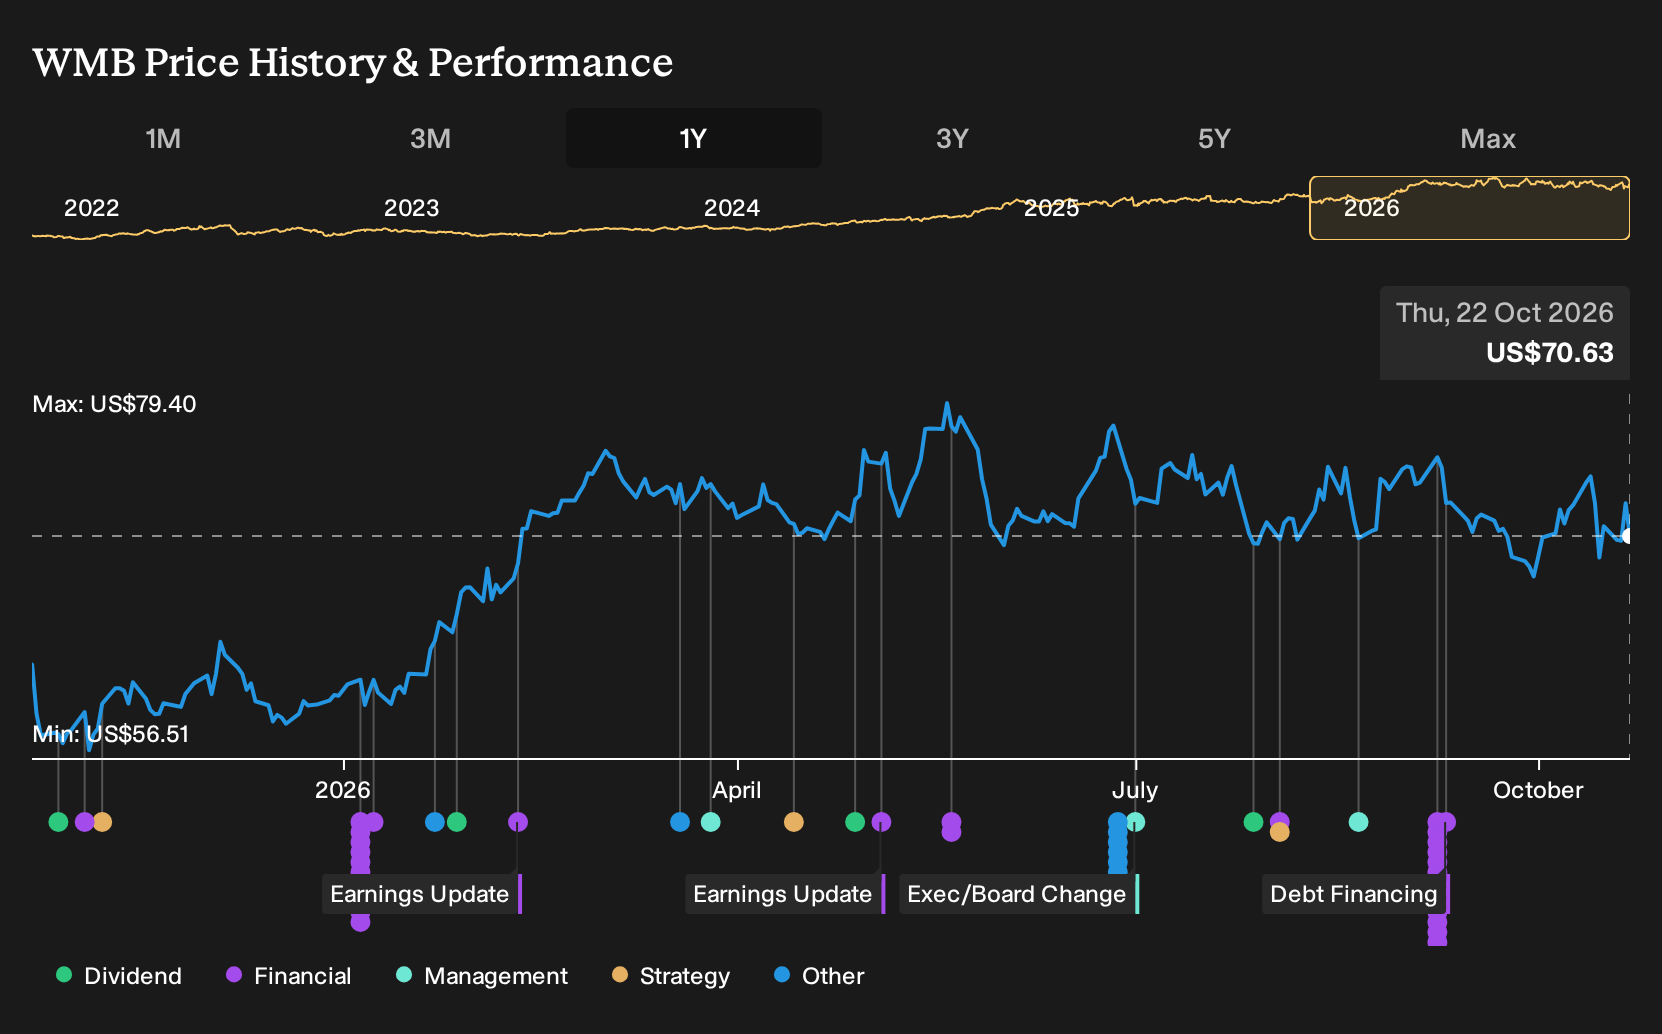
What The Williams Companies Evidence Put To The Test
Williams Companies moved ahead with big-ticket projects tied to the bullish story. Q2 2026 results showed revenue at US$2,959m and net income at US$827m, with net margin rising to 27.9%, which supported the LNG and data center demand case. Higher capital spending plans and a US$5.5b Momentum Midstream deal kept the cautious view on leverage and project risk alive, so the evidence cut both ways.
The key assumption was that heavy midstream spending would be backed by contracted gas and power demand. For any other pipeline operator, you would track whether project backlogs, reported margins and actual acquisition terms support the earnings profile that underpins the optimistic story.
What Williams Companies' Price Now Bakes In
Today Williams Companies trades at US$70.63, with the selected bullish Narrative arguing that its Fair Value sits above that level. The argument leans on contracted gas and power demand across its Gulf Coast and Haynesville systems, as well as the Power Innovation projects.
On that view, buyers now must judge whether current pricing fully reflects long-duration, contract-backed cash flows from projects like Neo, Socrates and the expanded Haynesville footprint.
"The Power Innovation platform, backed by a US$5.34b equity funding commitment from partners, is supporting a series of behind-the-meter projects such as Socrates and Neo that carry multi-year contracts, which can add incremental contracted earnings and improve overall returns on invested capital."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 39% below our estimate - turns lidar pilots into scaled production programs shipping hundreds of thousands of units.
- Company 2 - 35% below our estimate - converts an AI infrastructure contract backlog into recurring cloud and database usage revenues.
- Company 3 - 44% below our estimate - sells large LED display projects that bundle software, services and transportation system upgrades.
Three companies from the same screener. Open the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com