


- Canadian Utilities has broken ground on the Yellowhead Pipeline in Alberta, a 235-kilometre, CA$2.9b natural gas project expected to deliver 1.1 billion cubic feet per day and support about 2,000 direct construction jobs.
- The Yellowhead Pipeline capacity was fully subscribed before regulatory approval, which points to firm contracted demand that could influence Canadian Utilities' long-term infrastructure earnings profile.
- We will now look at how Canadian Utilities' investment narrative could shift as this fully contracted CA$2.9b Yellowhead Pipeline moves forward.
Scan fully contracted infrastructure plays like Canadian Utilities and compare them with other grid and pipeline operators inside our hand-picked 42 power grid technology and infrastructure stocks to see how this project fits into a wider theme.
Canadian Utilities Investment Narrative Recap
To own Canadian Utilities, you need to believe in a long runway of regulated energy infrastructure spending in Alberta and select international markets, supported by steady demand for electricity and natural gas. The Yellowhead Pipeline fits that thesis, as contracted capacity can underpin more predictable cash flows. In the near term, the key swing factor is execution on this capex program without eroding returns.
The biggest operational risk still sits with regulation and funding. Disputes with the Alberta Utilities Commission, thin net profit margins at 1.2%, and interest costs that are not well covered give limited room for error as Canadian Utilities layers on projects such as Yellowhead and Central East Transfer Out.
The Yellowhead groundbreaking ties directly into earlier commentary about substantial grid and gas system investment at Canadian Utilities. Analysts have already flagged this 90% contracted pipeline, along with Central East Transfer Out, as core drivers of future rate base and revenue. Full subscription of capacity before regulatory sign off now reduces volume uncertainty and puts the focus squarely on project delivery and cost control.
For investors, the operational question is whether management can translate this contracted backlog into higher quality earnings, given recent one off losses of CA$538.0m and profit margins that moved from 12% to 1.2%. If execution is disciplined and regulatory outcomes remain manageable, these projects may help address those weak margins and align with the forecast 42.1% annual earnings growth profile already embedded in expectations.
What The Yellowhead Pipeline Means For Canadian Utilities' Forecasts
Canadian Utilities' narrative projects CA$4.3 billion revenue and CA$1.1 billion earnings by 2029. That rests on 4.6% yearly revenue growth and an earnings increase of roughly 23x from CA$47.0 million today.
Uncover why Canadian Utilities' fair value indicates a 14% potential upside to its current price before the discount narrows.
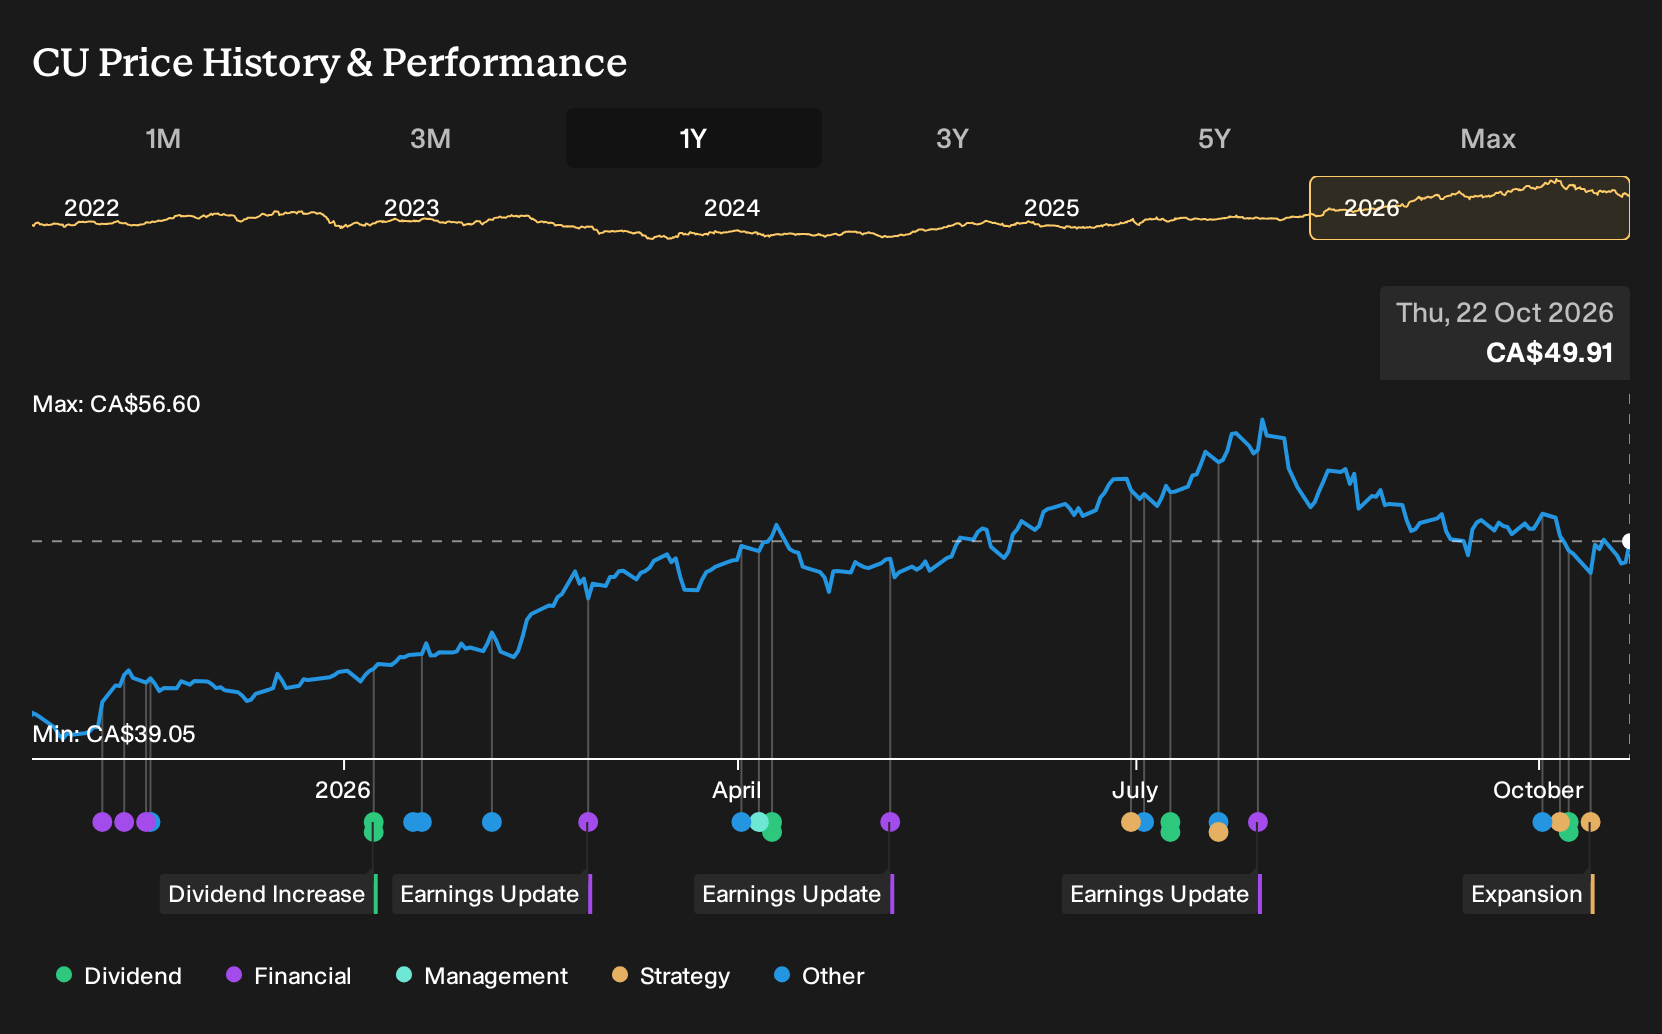
Exploring Other Perspectives
The Simply Wall St Community only shows two fair value views for Canadian Utilities, yet they span a wide band from CA$57 to about CA$139, which signals how far apart retail opinions can be. Those estimates were set before the Yellowhead Pipeline groundbreaking, so you may want to weigh them against regulatory risk in Alberta and the scale of the new capex cycle.
Explore another Canadian Utilities fair value estimate, including one that suggests it could be worth just CA$57.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Canadian Utilities research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Canadian Utilities. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canadian Utilities' overall financial health at a glance.
Looking For More Investment Ideas Beyond Canadian Utilities?
If the Yellowhead Pipeline has you thinking more broadly about infrastructure, income and balance sheet strength, it can help to line Canadian Utilities up against a wider watchlist built around clear themes.
- If income is your priority, start with a shortlist of high-yield payers that also focus on resilience by checking out 3 dividend fortresses.
- If you want potential value on your side, compare Canadian Utilities with other stocks that combine quality fundamentals with a meaningful discount through the 3 high quality undervalued stocks.
- If capital preservation comes first for you, focus on businesses that screen well on financial strength and risk by using the 8 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com