


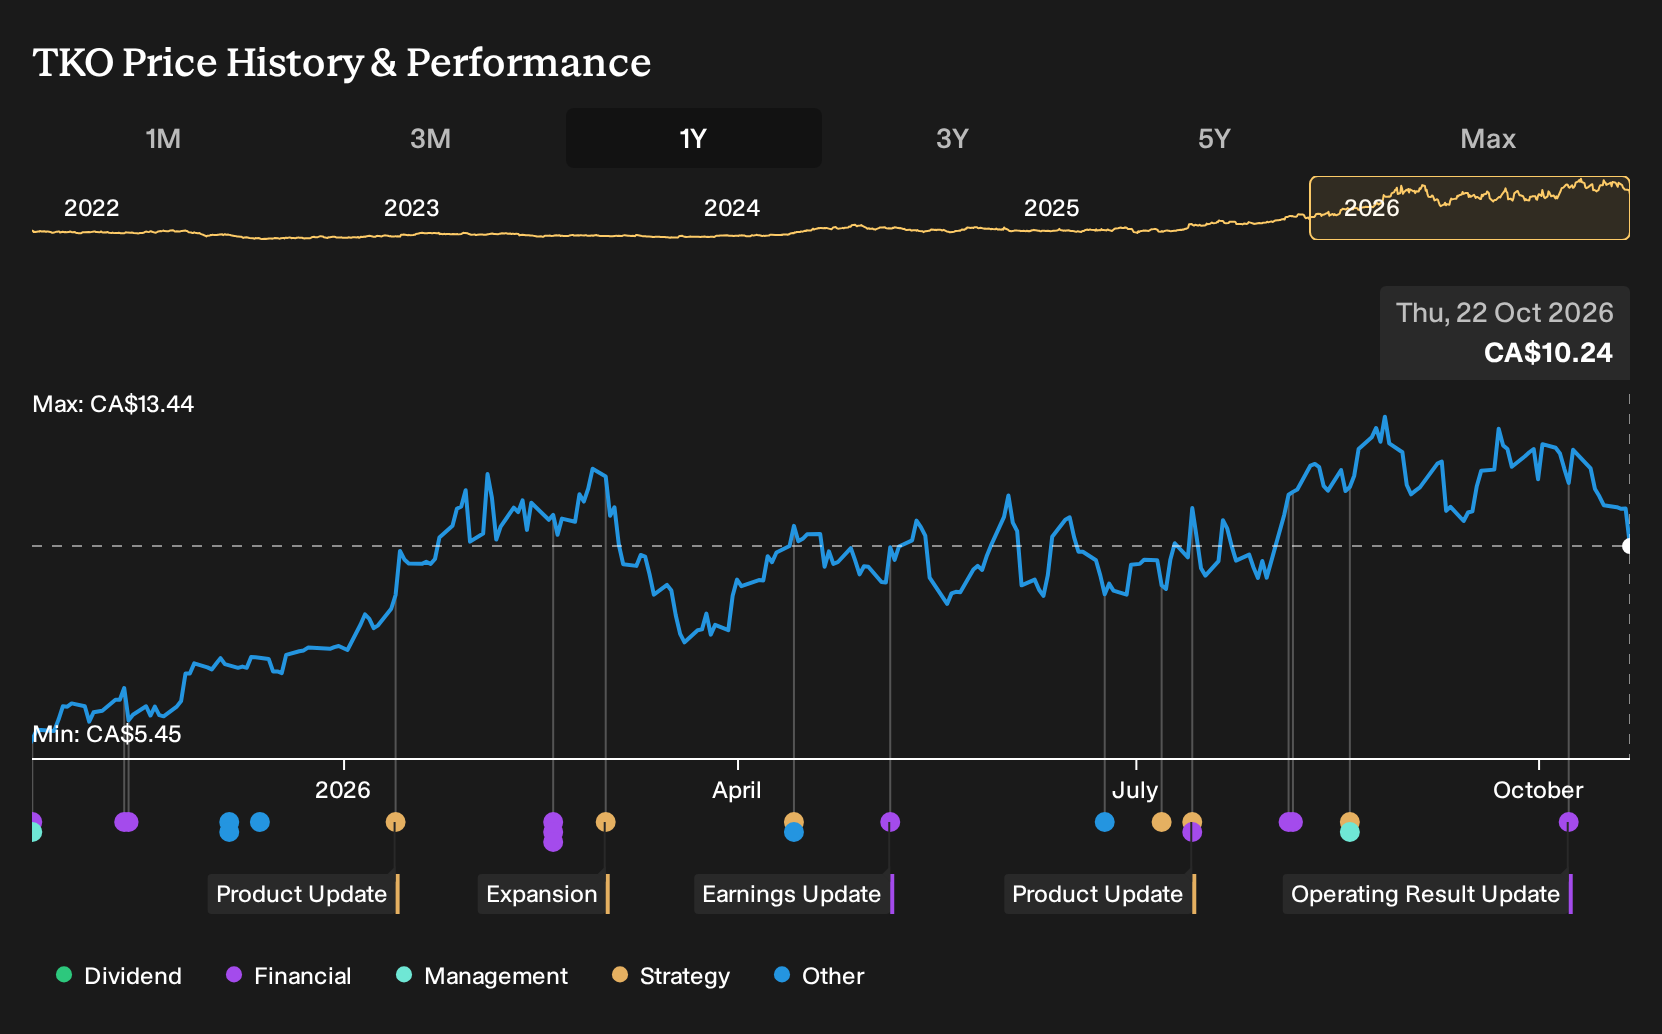
If Trekor Metals sat on your watchlist instead of in your account, the result may feel like a missed shot rather than a close call. For Trekor Metals shareholders, the return over the past year was 80.0%, including dividends. That outcome invites a tougher question. Back on 22 October 2025, when Florence Copper was pitched as a domestic electrification play and Gibraltar remained central, what specific belief about long term copper demand and North American supply would have justified owning it before that story was proven?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
This theme extends beyond Trekor Metals. See which of 16 top copper producer stocks may still merit a closer look.
The Two Trekor Metals Stories Investors Had To Weigh
The shares cost CA$5.45 at the start of the period, so anyone considering Trekor Metals had to decide which future for copper and Florence to believe.
On the bullish side, one Simply Wall St Narrative put Fair Value at CA$6.3, which is 16% above the start price. That story leaned on Florence Copper and Gibraltar together supporting revenue growth assumptions of 33.5% a year, with profit margins rising from a loss of 10.1% to 22.5%.
The bearish Narrative pointed to a Fair Value of CA$3.68, which is 8% below the start price. It treated regulatory and social pushback around Florence and Gibraltar as real threats, even while still assuming 25.6% annual revenue growth and margins climbing to 27.1%.
What The Evidence Around Trekor Metals Actually Tested
Florence Copper and Gibraltar both stepped up output, with Trekor Metals reporting Q2 2026 revenue of CA$330.553m versus CA$116.082m a year earlier, which backed the growth-focused narrative more than the cautious one. Net income was similar at CA$22.22m versus CA$21.868m, and net margin fell from 18.8% to 6.7%, so the profitability part of the optimistic case stayed unproven. The evidence therefore cut both ways.
The lesson to take elsewhere is simple. When a story leans on operating leverage, check whether rising sales translate into a stable or improving net margin rather than just watching the top line.
What Trekor Metals' 80% Run Already Prices In
Trekor Metals now trades at CA$10.24, after returning 80.0% over the past year, and the selected Narrative still places its Fair Value above that level. The argument leans less on copper output alone and more on cash margins from Florence Copper, Gibraltar and future projects like Yellowhead and Aley.
For anyone studying that view, the key question is whether Florence Copper can actually ramp to its planned production and cost profile so group cash generation supports the higher figure the Narrative sets out.
"The main thing that has to go right is that Florence Copper achieves its targeted ramp up and cost structure, while Gibraltar manages inflation exposed inputs and sustaining capital so group cash generation remains robust. The current valuation implies the market is heavily discounting Trekor Metals' ability to turn record quarterly EBITDA, growing production guidance and a large permitted growth pipeline into a higher and more resilient share price."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 34% below our estimate - uses recent acquisitions to reach new regions and deepen recurring advisory work.
- Company 2 - 47% below our estimate - targets higher income shoppers through premium sites and disciplined markdown management.
- Company 3 - 50% below our estimate - shifts mine plans to higher grade ore and longer life development projects.
Those are three of them. See the full list of 3 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com