


Why Ventas is on investors’ radar today
Ventas (VTR) has drawn fresh attention after recent share price moves, with the real estate investment trust changing hands at $86.99 at the most recent close in late October 2026.
The healthcare focused landlord reports annual revenue of $6.42b and net income of $262.73m, supported by roughly 1,450 properties across senior housing, outpatient medical buildings, research centers and other healthcare facilities.
Recent trading has been mixed for Ventas, with a 1-day share price return of 1.89% and 7-day gain of 2.51% offset by a 90-day share price decline of 13.47%. At the same time, the 1-year total shareholder return of 27.41% and 3-year total shareholder return of roughly 2.3x original capital suggest momentum has built over a longer stretch.
Compare Ventas with a hand picked list of solid balance sheet and fundamentals (26 results) to see which other businesses that pair real assets with healthcare demand are also catching renewed interest.
Recent gains and that 90 day pullback leave Ventas in an awkward middle ground. Is this a reasonable entry now, or does waiting for a cheaper valuation make more sense?
Most Popular Narrative: 15% Undervalued
Ventas is framed by the most followed thesis as worth about $101.86 per share, which sits above the recent close of $86.99 and underpins a view that the healthcare landlord is not fully priced in yet.
Ventas is positioned to benefit from a rapidly growing aging population that is driving sustained demand for senior housing and healthcare facilities. This is combined with historically low new construction, which supports the possibility of multi-year occupancy gains and net operating income growth as occupancy rates move toward the 90% level. This can add operating leverage and support higher margins and earnings.
See why 15 investors see Ventas as 15% undervalued.
Result: Fair Value of $101.86 (UNDERVALUED)
Still, the Ventas story depends heavily on senior housing staying near 90% occupancy and on acquisitions remaining attractive enough to offset ongoing equity issuance.
Find out about the key risks to this Ventas narrative.
Another view on Ventas valuation
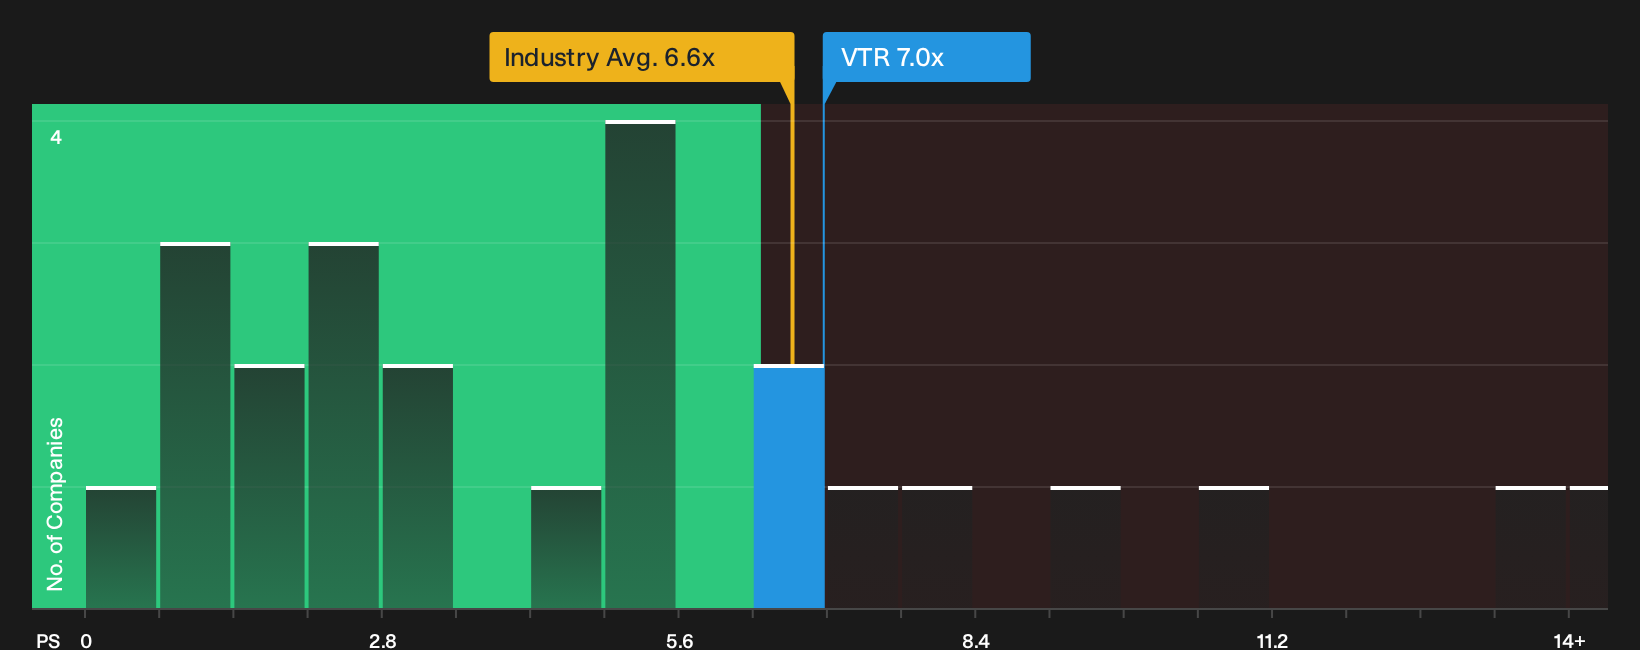
On price to sales, Ventas trades at about 7x, which is richer than its fair ratio of 5.6x and above the global health care REITs average of 6.6x, yet below peers at 8.5x. That mix points to meaningful valuation risk if sentiment cools, but also some relative support.
To see how those numbers translate into practical trade offs for investors, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value often create the most interesting setups, so act while the data is fresh in your mind and weigh the trade offs yourself using 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Ventas?
Do not stop at Ventas. Broaden your watchlist with fresh ideas that match your risk appetite, income goals and balance sheet preferences using the Simply Wall St Screener.
- Target lower volatility by focusing on businesses with healthier finances through a 30 resilient stocks with low risk scores that can help you sidestep balance sheet strain.
- Chase reliable income streams by scanning for mature enterprises that feature a 6 dividend fortresses and may suit a cash flow focused approach.
- Get ahead of the crowd by tracking a 20 high quality undiscovered gems before the wider market pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com