


Pearson’s latest guidance and leadership shift
Pearson (LSE:PSON) is back in focus after its latest quarterly update reaffirmed full year 2026 guidance, alongside acquisitions in assessment and AI skills platforms, and a restructure into four customer focused divisions.
Recent price action suggests investors are rewarding Pearson’s execution. The share price is up 14.44% over the past month and 34.48% year to date, while the 5 year total shareholder return of 155.64% points to momentum that has been building over a longer stretch.
Scan for other education and skills stocks that are trying to capture the same AI and assessment tailwinds as Pearson with the hand picked 5 high quality undiscovered gems list.
Pearson’s rerating could be read as confidence in its assessment, AI skills and restructuring push, or as sentiment running ahead of itself. The next step is to see what the current valuation actually implies.
Most Popular Narrative: 10% Overvalued
Pearson last closed at £13.71, while the most followed narrative pegs fair value closer to £12.52. This frames the recent rally as leaving less obvious valuation headroom unless the new AI and assessment initiatives deliver strongly.
The rapid acceleration of AI and digital transformation in education is enabling Pearson to launch advanced AI-driven study and assessment tools, cut content localization time-to-market, and streamline customer service, directly supporting higher digital revenue growth and net margin expansion.
The rising global demand for upskilling, workforce certifications, and lifelong learning is increasing Pearson's addressable market in both B2B and direct-to-consumer segments, particularly through its Enterprise Learning & Skills and Early Careers initiatives, which should drive top-line growth and earnings diversification.
See why 18 investors see Pearson as 10% overvalued.
Result: Fair Value of £12.52 (OVERVALUED)
Still, the narrative breaks if FX swings continue to squeeze reported earnings or if Pearson’s contract driven units face pauses that unsettle cash flow visibility.
Find out about the key risks to this Pearson narrative.
Another View: Pearson’s valuation through earnings multiples
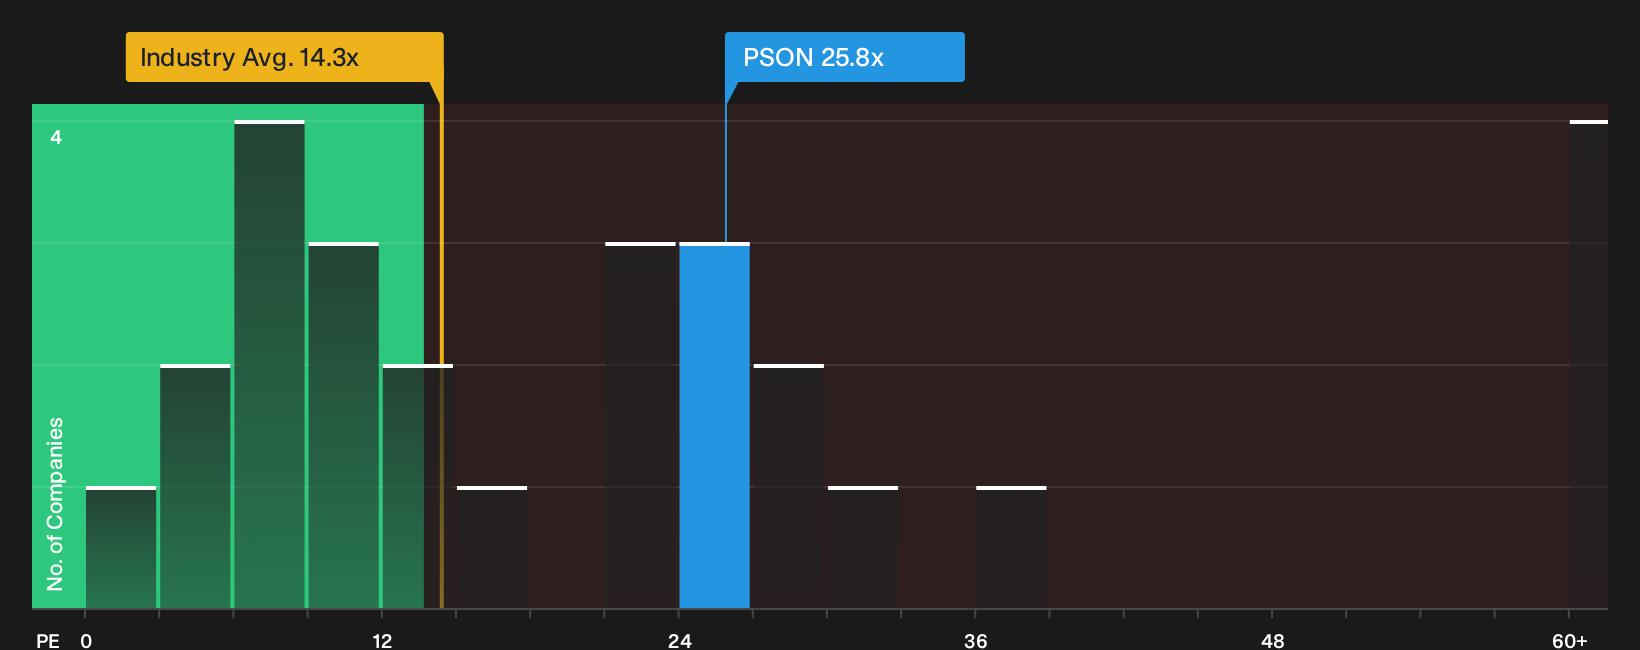
On the first cut, Pearson looks 10% above the £12.52 fair value implied by the most followed narrative. Yet its current P/E of 25.8x is far below peer averages of 41x, and only modestly above a fair ratio of 19.9x that the market could move towards over time.
If the Global Consumer Services industry trades on 14.3x and Pearson changes hands at 25.8x, investors are paying a premium to the sector but a discount to closer peers. That mix can mean less room for error if growth wobbles, or room to re rate if execution stays on track.
To pressure test which side of that trade off you lean toward, it helps to see what the numbers say in one place. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Pearson leave you undecided, that is the point where doing your own homework matters most. The optimism around its potential rewards is a good place to start, so round out your view by checking the 2 key rewards
Looking for more ideas beyond Pearson?
If Pearson has sharpened your interest, do not stop here. The market is full of other opportunities that could fit your goals just as well.
- Target stability first by checking out companies with stronger finances and balance sheets through the list of solid balance sheet and fundamentals (9 results).
- Hunt for value by reviewing the 7 high quality undervalued stocks that combine quality fundamentals with pricing that may offer more room for upside.
- Prioritize resilience by scanning the 4 resilient stocks with low risk scores that score well on risk metrics and can help steady a broader portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com