


- Illumina introduced three early access tools on its BioInsight Platform, including DRAGEN Ultra, Workflow Orchestrator, and Learning Cohorts, aimed at helping researchers manage large genomic datasets, automate lab workflows, and move faster from sequencing output to biological insights.
- The additions position Illumina to deepen its role in software, AI models, and curated data, which could influence future demand mix, recurring usage of its platforms, and how research customers standardize their genomic pipelines around the BioInsight environment.
- We will examine how Illumina's investment narrative is affected by this AI driven BioInsight expansion, particularly the launch of DRAGEN Ultra.
Scan how Illumina's push into AI driven genomics compares with other potential breakout plays by reviewing the hand picked 36 healthcare AI stocks that are shaping this shift in healthcare data and discovery.
Illumina Investment Narrative Recap
To own Illumina, you need to believe that clinical sequencing, NovaSeq X consumables, and higher margin software and data can justify a premium P/E despite slower forecast revenue growth of 6.8% a year. The BioInsight push fits that thesis by aiming to deepen usage of existing instruments rather than relying only on new hardware cycles.
The near term catalyst still sits in execution on NovaSeq X pull through and clinical consumables, which grew in the mid teens to around 20% ex China earlier in 2026. The biggest risk remains that earnings and margin expansion fall short of expectations in a business already viewed as expensive on several valuation metrics.
The most relevant update here is DRAGEN Ultra, now in early access on the BioInsight Platform and also deployable on premises and in private clouds. It takes Illumina further into tertiary analysis by combining genomic AI models and knowledge resources to help researchers prioritize which variants matter in large rare disease and population genomics projects.
Operationally, the interest is that DRAGEN Ultra and dnaAI can increase the value of each sequenced sample. This supports the broader narrative around recurring software and data usage layered on top of NovaSeq X volume. The key execution risk is whether Illumina converts early scientific enthusiasm at ASHG into consistent, paid usage that is material next to its US$4.5b revenue base.
What The Consensus Illumina Numbers Assume
Analysts are effectively asking you to underwrite a very specific Illumina path. The models point to revenue growing at about 7.0% a year over the next few years, profit margins stepping up from 18.3% today to 20.6%, and earnings moving from US$824.0m now to a consensus US$1.1b by 2029, with the most optimistic forecasts reaching US$1.3b. That earnings profile would mean an increase of roughly US$276m from current profit levels by the 2029 estimate year, alongside a gradual decline in the share count of about 1.18% a year.
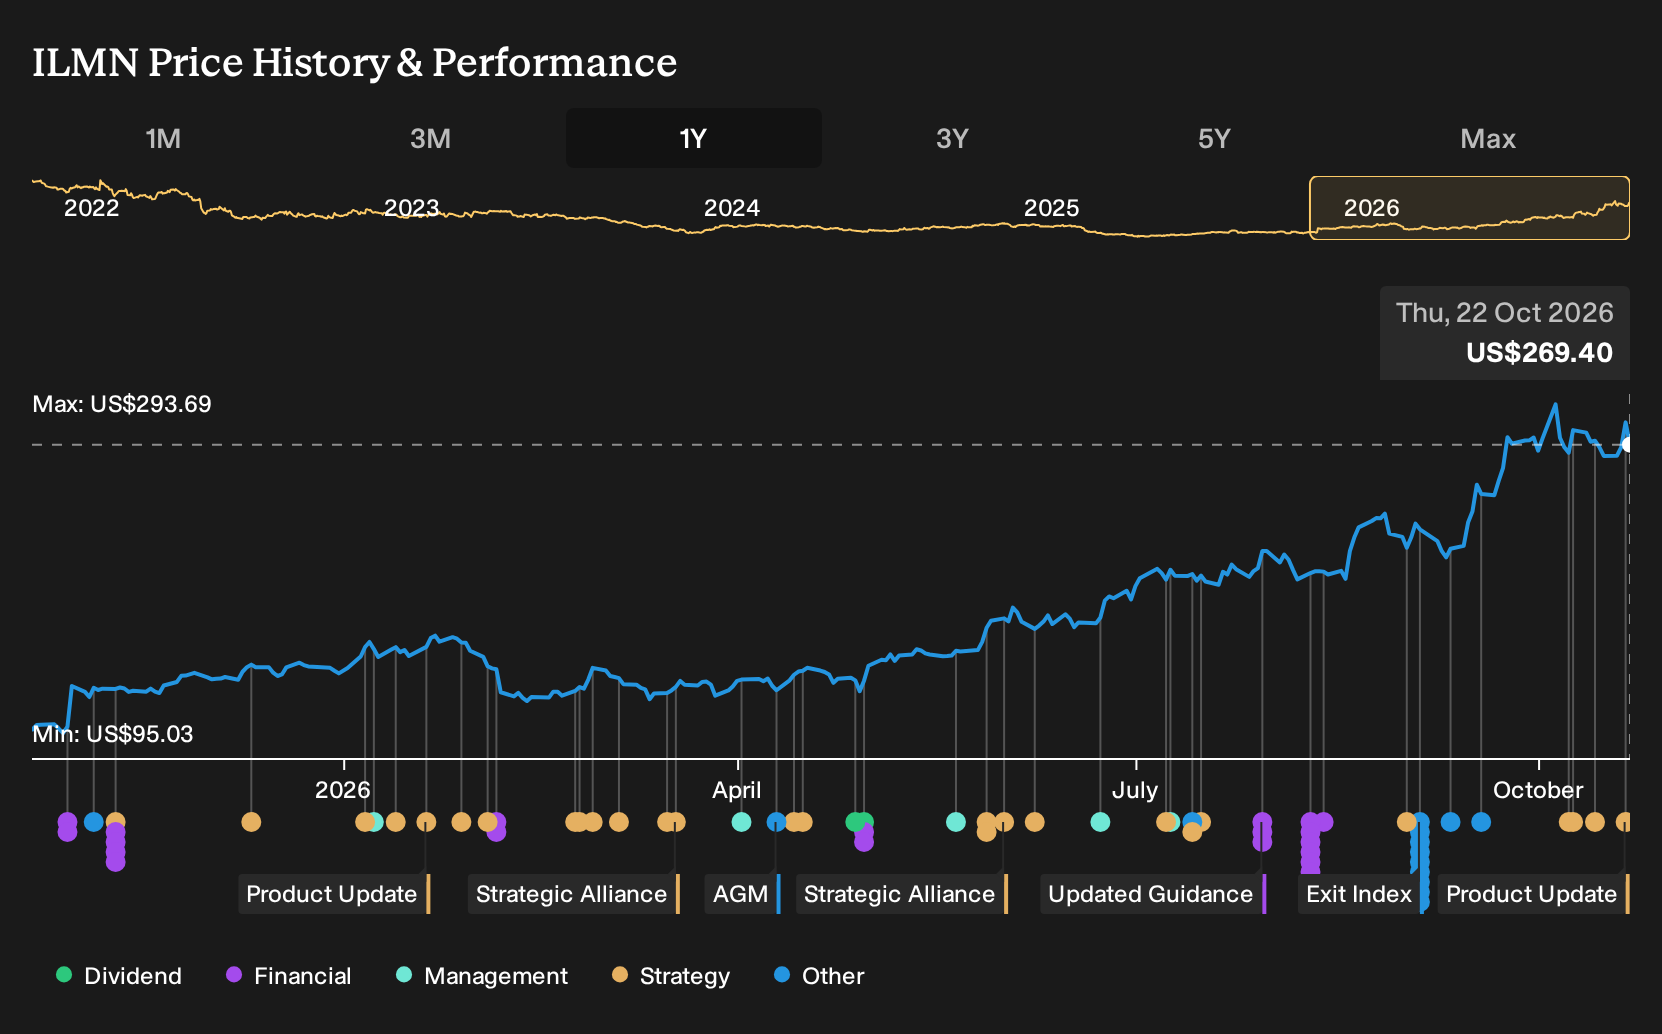
On those assumptions, the valuation work ties back to Illumina generating about US$5.5b of revenue and US$1.1b of earnings in 2029. The shares would then be trading on a P/E of 38.4x at that point, compared with 49.7x today and an industry multiple of 41.5x. The current analyst target of US$236.55 sits 14.6% below the US$271.18 share price. This suggests that even though the consensus expects the underlying business to improve, many on the Street see the present market price as already baking in a richer scenario than their base case.
Illumina's narrative projects about US$5.5b of revenue and US$1.1b of earnings by 2029. This requires 7.0% yearly revenue growth and an earnings increase of roughly US$276m from current earnings of US$824.0m.
Uncover why Illumina's fair value indicates a 12% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For Illumina, the sharpest alternate risk centers on competition and pricing rather than execution on BioInsight. The most bearish analysts were working off only 5.5% yearly revenue growth to about US$5.3b and the same US$1.1b earnings by 2029, yet pairing that with a far lower 19.4x P/E. Those pre news assumptions show how wide opinions run; use this ASHG update as a prompt to compare several views before deciding what feels reasonable to you.
Explore 3 other Illumina fair value estimates, including one that suggests as much as 14% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Illumina research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Illumina. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Illumina's overall financial health at a glance.
Looking for more investment ideas beyond Illumina?
Once you have a view on Illumina, it can help to widen the lens and compare it with other opportunities that match your preferred balance of quality, risk, and income using the Simply Wall St Screener.
- If you want financially stronger businesses that can potentially ride out tougher periods, start by reviewing a curated 30 resilient stocks with low risk scores that score well on resilience and risk controls.
- For readers who care most about balance sheet strength and fundamentals, scan a focused list of solid balance sheet and fundamentals (26 results) to see which companies pair robust finances with cleaner capital structures.
- If you prefer hunting for opportunities that are less widely followed, compare Illumina with a hand picked 20 high quality undiscovered gems that combine solid business quality with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com