


General Motors stock has climbed sharply over the past few years, and with fresh headlines around buybacks, electric vehicles and new technology, the live question for investors is whether the current US$77.21 share price is justified by the cash it can generate.
- Over the past 3 years the share price has delivered a very large 178.7% gain, which puts a lot of weight on whether the underlying cash flows can keep supporting that kind of re-rating.
- Recent updates on profitability, free cash flow and heavy spending on areas like batteries, driver assistance and hybrids can shape how durable General Motors' cash generation looks and how much surplus capital may be available for dividends and buybacks.
- Prefer to judge General Motors on earnings? See what General Motors's 16.8x P/E says about the price.
The issue now is whether those cash flows, assessed through a Discounted Cash Flow (DCF) view, line up with where General Motors trades today.
If you want a quick sense check on how General Motors compares on this cash flow story, it can help to line it up against 30 high quality undervalued stocks.
Does General Motors Look Undervalued on Cash Flow?
The Discounted Cash Flow model here takes General Motors' projected cash generation and discounts it back into today's dollars. On this view, the valuation work leans heavily on steady free cash generation rather than a big acceleration story.
Over the last twelve months General Motors produced a little over $13.5b in free cash flow, and the projections used in the model assume that annual cash flows stay in a roughly similar $11b to $13b band over the coming decade. That pattern points to a mature business that is expected to keep throwing off substantial cash rather than one built on aggressive expansion, which matters when you set that against a current share price of $77.21. Because the new $20b buyback authorization absorbs a meaningful slice of that cash, the reaction to it helps explain why the market price can still sit below what the cash flow model implies. Find out what General Motors could be worth using our Discounted Cash Flow (DCF) estimate.
The General Motors Narrative: What Would Justify Today's Price?
General Motors' valuation puzzle only really comes into focus once you spell out the future paths that would need to play out for the stock to look materially cheaper or richer than today. Simply Wall St Narratives on the Community page do exactly that by tying each scenario's number to a concrete view on where General Motors' growth, profitability and risk profile might head next, giving you something you can revisit as fresh information becomes available.
Community views on General Motors are split between a cash flow story that still looks appealing and a transition that some see as already fully priced.
Bull case: 24% undervalued
"The growing base of subscription and software enabled services, including roughly US$3b of expected high margin digital revenue in 2026 and a deferred revenue balance approaching US$7.5b, can increase recurring revenue and raise overall net margins as this mix expands..."
Discover why this Narrative puts General Motors at 24% undervalued.
Bear case: 15% overvalued
"EVs are still margin-dilutive for GM. Battery costs, manufacturing inefficiencies, and supply chain constraints continue to pressure profitability..."
Explore why this Narrative puts General Motors at 15% overvalued.
One more piece to weigh before acting on General Motors
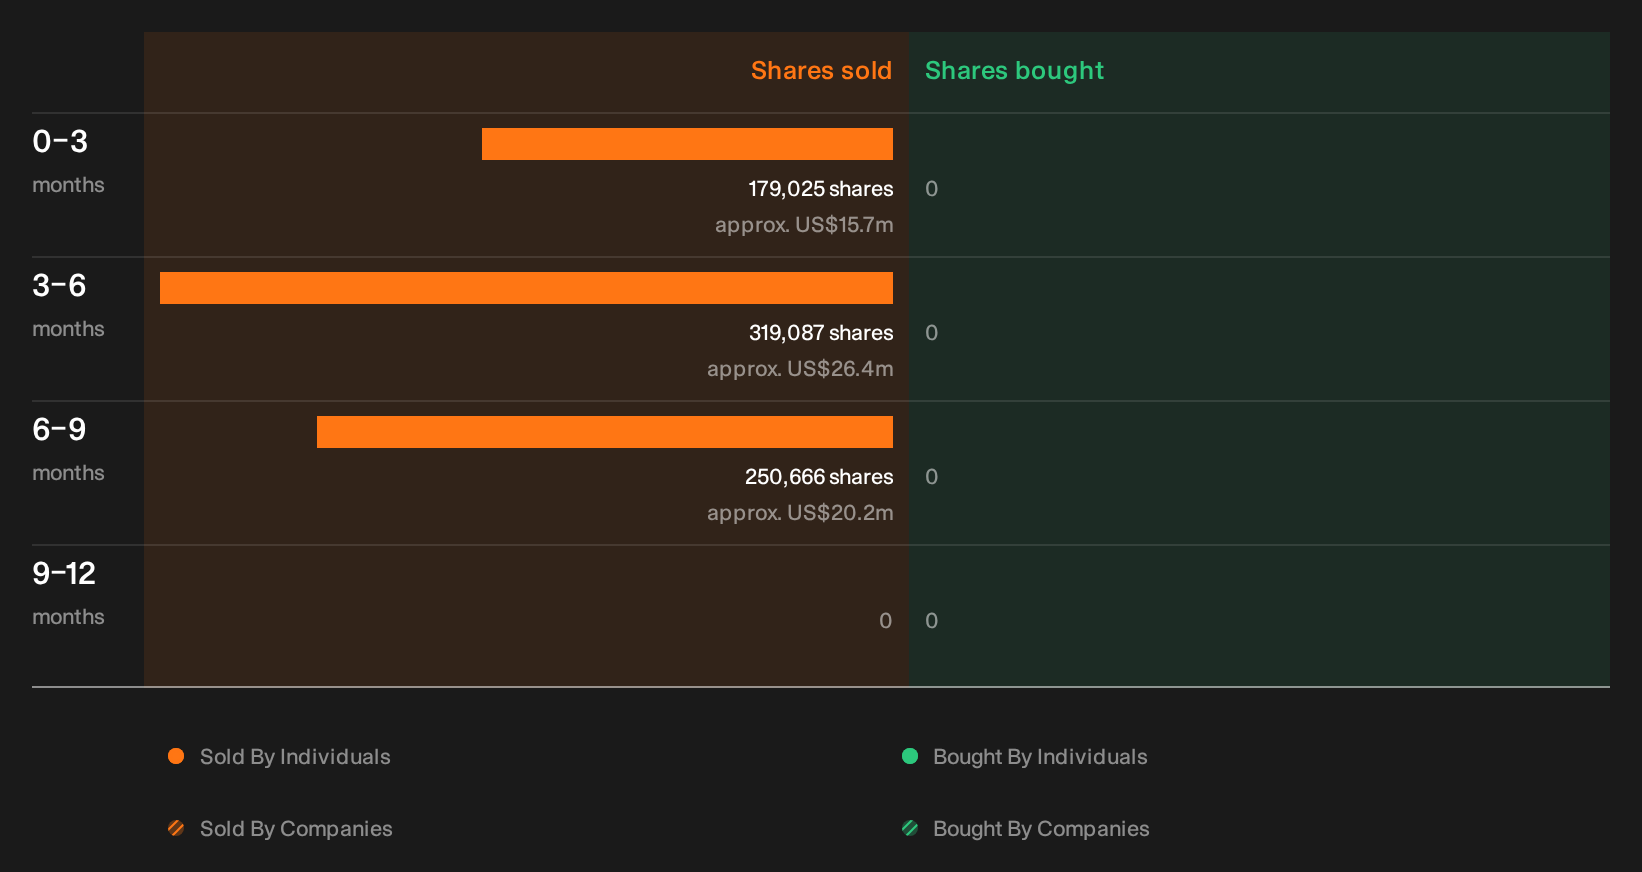
Before you lean too hard on the cash flow story or community scenarios, it is worth checking who inside General Motors has been selling stock recently, how much they sold and what that might signal for you. See the recent insider selling flagged for General Motors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com