


NDAQ jumped 7.5% to about $103 in the first full session after its Q3 2026 report, a sharp move for an exchange operator that usually trades on steady expectations, not drama. Traders reacted to the headline beat as Nasdaq posted roughly $1.5b in quarterly revenue and a P/E of 27.7x that now sits above a discounted cash flow value near $88. These are eye catching numbers in a capital markets stock built on long contracts and recurring fees, so the key consideration is whether this move reflects lasting earnings power or only a strong single report.
Like the earnings pop and recurring-fee model at Nasdaq but worried about paying 27.7x P/E for that stability? Consider using the curated list of solid balance sheet and fundamentals stocks (26 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$1,481m vs. US$1,315m (up about 12.6%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$540m vs. US$423m (up about 27.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.97 vs. US$0.74 (up about 30.9%)
- Trailing Twelve Month Total Revenue (Q3 2026 vs. Q3 2025): US$5.78b vs. US$5.08b (up about 13.7%)
Earnings tell one story, but investors who care about valuation usually study the cash that actually comes in and out of the business. Accounting profit is important, yet long term value often rests on those cash movements.
When you focus on Nasdaq's cash flows rather than headline EPS, the current share price starts to look different and the stock could be a clear 17% overvalued.
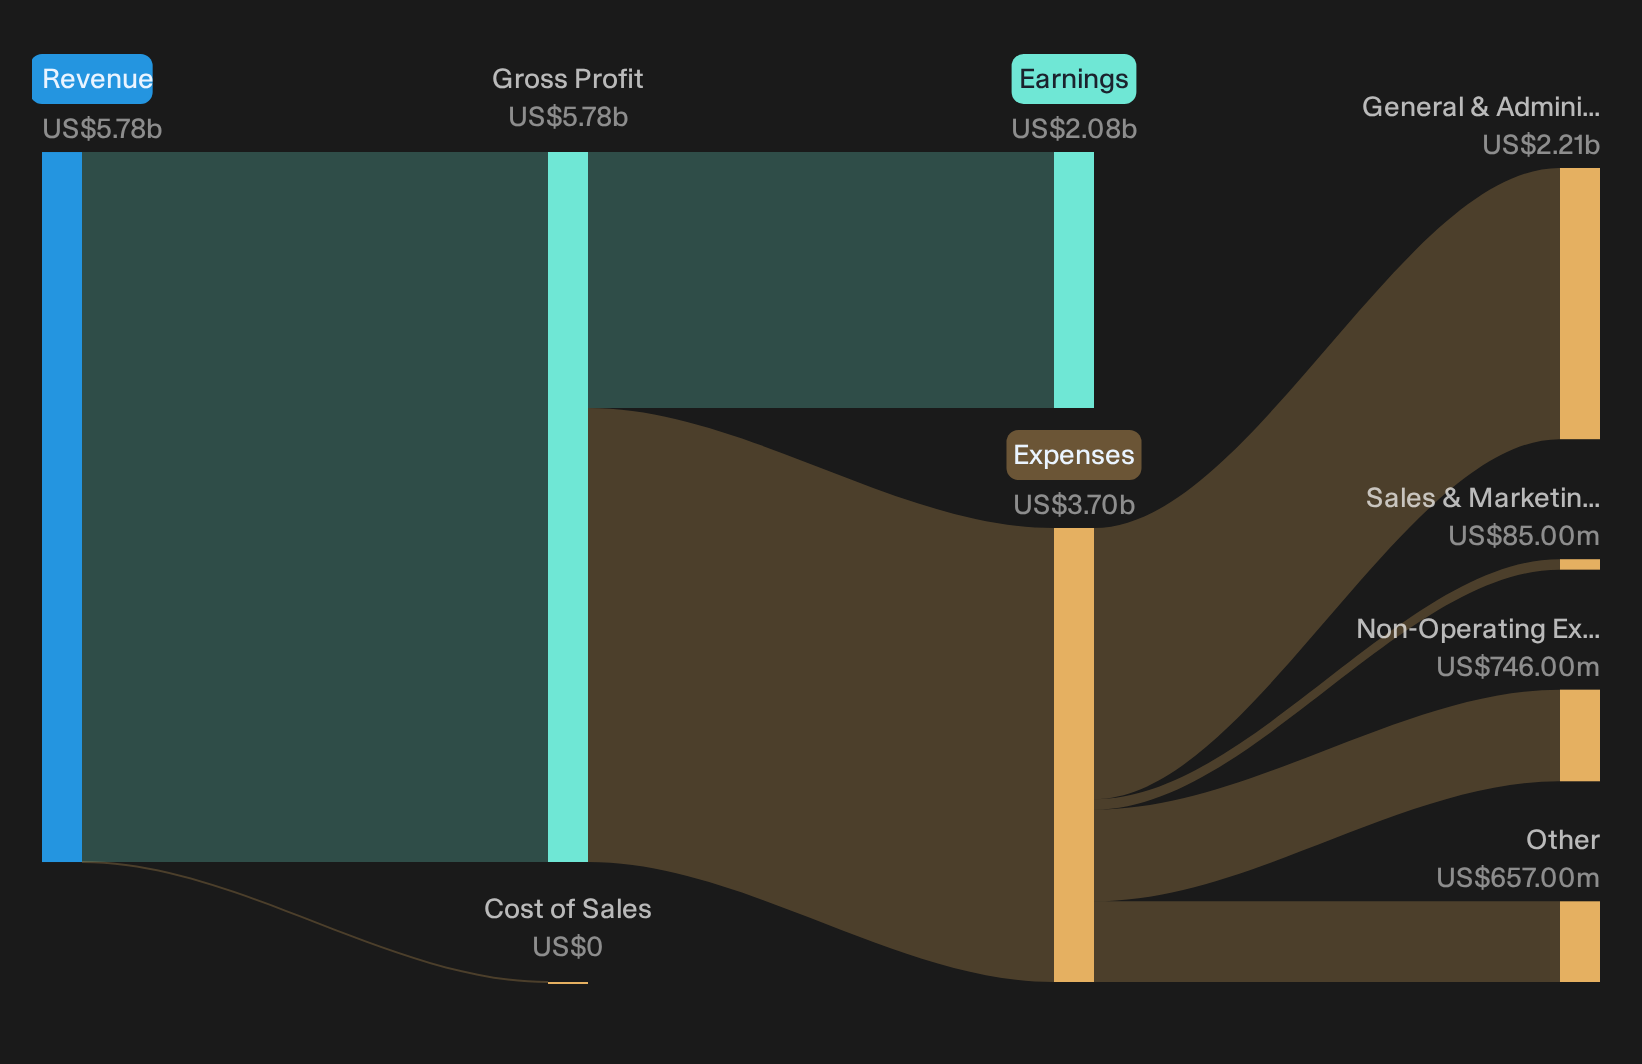
Nasdaq bull case: fintech engine hits key markers
The upbeat Nasdaq story rests heavily on AI and financial‑crime tools turning into a true second engine next to markets and index.
"A key factor is that Nasdaq successfully scales its AI and financial crime platforms, tokenization modules, and 23/5 trading data services so that client adoption and pricing support the current growth initiatives."
Q3 FinTech revenue rose 16% with ARR up 18%, which lines up with that aim. Verafin still looks central, posting 23% revenue growth, 19% ARR growth and more than 850 customers using Agentic AI workers, with more than 70 paying. Cloud bookings at 85% of FinTech deals and 1.5x ACV uplift on migrations show clients paying for the upgraded stack.
Nasdaq bear case: cost creep and execution strain
The main worry is that heavy spend on always‑on trading, tokenization and AI chases too many projects at once and eats into returns.
"Nasdaq is investing heavily in initiatives such as 23/5 trading, tokenized collateral modules and expanded AI enabled platforms. If client adoption, pricing or technical execution do not support the required returns on this higher spend, the result could be slower net revenue growth and weaker EBITDA margin than investors currently expect."
Non‑GAAP expenses climbed 12% in Q3 and full year guidance nudged higher to US$2.550b to US$2.580b. Yet revenue grew 14%, EBITDA margin held at 60% and free cash flow reached US$2.3b over 12 months with gross leverage at 2.5x, so higher outlays are still covered by current traction.
The price and this Narrative do not agree. → Uncover what this Narrative says Nasdaq is actually worth.
Hunt For Mispriced Cash Engines
Nasdaq just reported earnings and its rapid move shows how sentiment can change when results arrive. The real opportunity may lie in finding stocks that appear undervalued before the market adjusts their prices.
- Company 1 - 39% below our estimate - ships lidar units at production scale as automakers secure long term sensor suppliers.
- Company 2 - 36% below our estimate - uses a high frequency super app to cross sell credit and commerce to a large user base.
- Company 3 - 49% below our estimate - wins multi year mega projects as government clients adopt bundled design build contracts for complex work.
Those are three of them. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com