


Danaher (DHR) just reported third quarter 2026 sales of US$6.55b and net income of US$1.24b, providing investors with updated figures to reassess the stock.
While the earnings beat initially pushed Danaher’s share price higher, the stock has since cooled a little. It has a 1-day share price return of a 1.76% decline and a 7-day share price return of a 0.76% decline, yet a 90-day share price return of 19.97% and a 1-year total shareholder return of 3.91% show momentum has been building over the past quarter, even as longer term performance over five years, with a 12.70% total shareholder return decline, remains more subdued.
Scan how Danaher’s earnings momentum compares with peers by reviewing our hand picked list of 36 healthcare AI stocks that are also tying laboratory tools to AI advances.
Danaher now trades only slightly below some fair value models, yet sits at roughly a 10% discount to analyst targets. Is that a cautious market mispricing or a reasonable buffer after the post earnings surge?
Most Popular Narrative: 5.9% Undervalued
On the most followed view of Danaher, a fair value of $244.14 sits modestly above the last close at $229.75. This places recent gains in the context of a stock that screens only slightly below that narrative estimate and close to some DCF models.
Accelerating demand for biologics and single use bioprocessing equipment, reflected in more than 30% year over year growth in bioprocessing equipment orders in early 2026 and mid teens order growth for consumables and equipment in Q2 2026, supports expectations for a multiyear capacity investment and onshoring cycle that can lift Biotechnology segment revenue and operating leverage.
See why 79 investors see Danaher as 6% undervalued.
Result: Fair Value of $244.14 (UNDERVALUED)
Still, the Danaher narrative could be knocked off course if bioprocessing orders lag again or if China pricing and reimbursement pressure deepen from here.
Find out about the key risks to this Danaher narrative.
Another View: What Danaher’s P/E Is Telling You
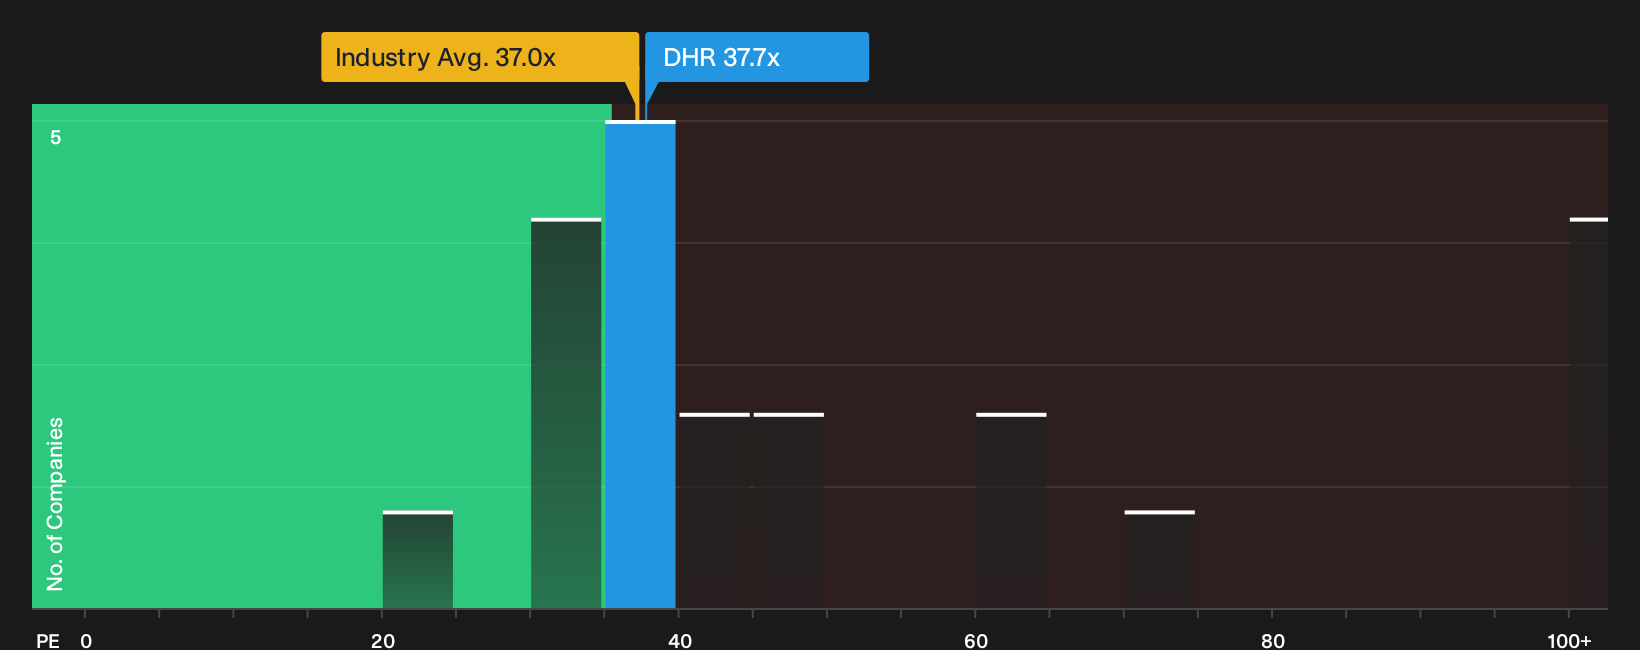
There is a different read on Danaher when the focus shifts from fair value models to what investors are actually paying today. The stock trades on a P/E of 37.7x, slightly above the Global Life Sciences industry at 37x and clearly above its own fair ratio of 33.3x. That gap points to a richer price tag and leaves less room for disappointment if growth or margins soften.
It raises a simple question for you: Is this premium something you are comfortable paying for Danaher, or does it tip the balance toward waiting for a better entry point?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Danaher is mixed enough that you should not just take any single narrative at face value, especially with both concerns and bright spots emerging in the latest data. If you want a clearer picture before reacting to the next headline move, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Danaher?
Do not stop your research with Danaher. Fresh opportunities show up when you compare it with other businesses that share strong balance sheets, cash flows and income streams.
- Target greater resilience by scanning a list of solid balance sheet and fundamentals (26 results) that can help you stress test ideas before you commit capital.
- Hunt for value by lining up companies in the 30 high quality undervalued stocks and seeing which ones match your risk and return expectations.
- Build a steadier income stream by reviewing our 6 dividend fortresses so you are not relying on capital gains alone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com