


Karman Holdings (KRMN) moved back into focus after subsidiary Karman Space & Defense signed a seven year, US$218 million agreement with Lockheed Martin related to shroud production for the THAAD interceptor program.
Despite this contract, Karman Holdings’ recent trading tells a tougher story, with the share price down 27.11% over 90 days and the year-to-date share price return falling 55%, contributing to a 57.82% decline in one-year total shareholder return from a last close of US$34.58.
Contrast the recent share price pressure at Karman Holdings with other defense contractors by scanning a curated group of 42 power grid technology and infrastructure stocks that may also benefit from long-term government and infrastructure programs.
Karman Holdings now trades well below both its recent levels and the analyst price target range. Where does a fair value anchor really sit before getting into the valuation work?
Most Popular Narrative: 67% Undervalued
The leading narrative on Karman Holdings places fair value near $105.60, which is materially above the recent close at $34.58. That gap is built on detailed assumptions about growth, backlog and cash flow rather than a simple chart move.
This is not a story of a company in distress that the market is correctly marking down. It is a hypergrowth defense compounder that ran too far, too fast, got punished for modest EPS misses, and is now pricing in a much more pessimistic scenario than the fundamentals support.
See why 48 investors see Karman Holdings as 67% undervalued.
Result: Fair Value of $105.60 (UNDERVALUED)
Still, the Karman Holdings story can break if leverage stays heavy or key defense customers slow orders. That would quickly challenge that 67% undervalued narrative.
Find out about the key risks to this Karman Holdings narrative.
Another View On Karman Holdings: Expensive On Earnings
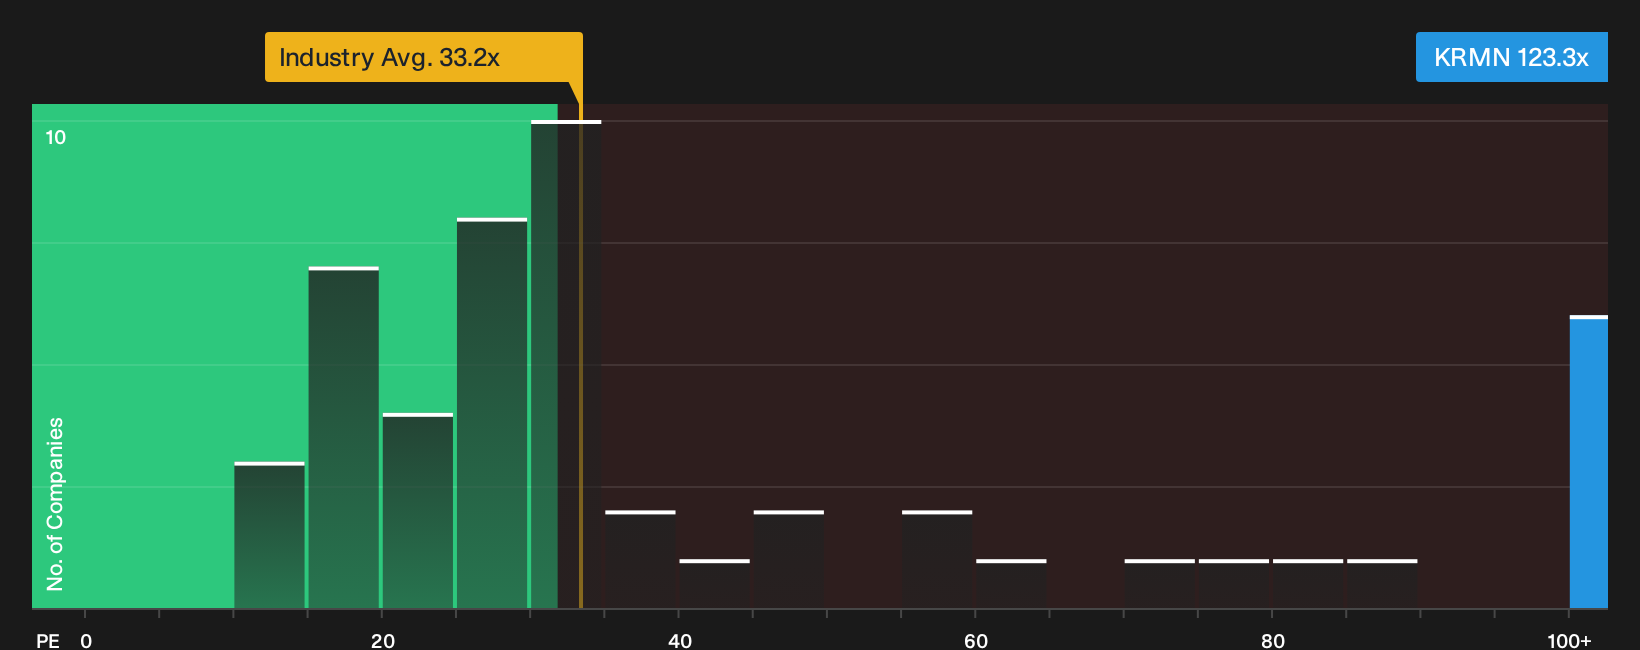
The 67% undervalued fair value story meets a very different message when you look at Karman Holdings through its P/E. The stock trades on a P/E of 123.3x, compared with 33.2x for the US Aerospace & Defense group and a fair ratio of 76.9x that our model suggests the market could move toward.
That gap implies investors are already paying a heavy premium for future profit expansion, even after the share price slide. If sentiment cools or forecasts change, does this compression risk outweigh the upside in the bullish fair value narrative, or is the premium simply the price of access to high forecast growth?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages or clear setup? With Karman Holdings caught between concerns about risk and optimism about potential rewards, move quickly and evaluate both perspectives through 2 key rewards and 1 important warning sign.
Looking for more Karman Holdings sized opportunities?
If Karman Holdings has sharpened your focus on pricing power and risk, use the Simply Wall St screener to uncover other ideas before the crowd catches on.
- Target resilient payers that prioritise income strength by scanning a curated set of 6 dividend fortresses built to support dependable cash distributions.
- Hunt for quality at a discount by reviewing a focused group of 30 high quality undervalued stocks where fundamentals and price appear out of sync.
- Prioritise capital protection first by checking a tailored pool of 30 resilient stocks with low risk scores designed to keep volatility and risk scores in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com