


- InterDigital highlighted that Joseph Levy was elected to the IEEE Standards Association Board of Governors for the 2027 to 2028 term, reflecting his long running role in Wi Fi standards work.
- This recognition reinforces InterDigital’s focus on shaping global wireless and video standards, which underpin its licensing model across devices, streaming, and connected platforms.
- We will now see how InterDigital’s investment narrative could be influenced by Joseph Levy’s new IEEE governance role in wireless standards.
Scan how other standards heavy wireless and connectivity specialists are priced and positioned right now by reviewing our hand picked 30 high quality undervalued stocks alongside InterDigital.
InterDigital Investment Narrative Recap
To own InterDigital, you need to be comfortable with a patent licensing model that leans on recurring agreements across devices, streaming, and connected hardware. The big near term swing factor remains how the Amazon arbitration and broader streaming and cloud revenue shape the recurring base. Joseph Levy’s IEEE role looks more reputational than financially material in the short run.
The key risk still sits in enforcement costs and the arbitration outcome. Elevated legal spending and any weaker than expected award could pressure earnings and slow capital returns funded from roughly US$1.1b of cash. InterDigital’s standards leadership, including this IEEE appointment, mainly feeds the longer term patent pipeline, not immediate cash flow.
The most relevant recent item here is the discussion of InterDigital’s leadership roles in wireless standards bodies, particularly 3GPP work tied to future 6G specifications. Levy’s election to the IEEE Standards Association Board reinforces that standards footprint, which is central to how the company builds patent portfolios that later support licensing across phones, IoT, automotive, and streaming platforms.
For catalysts, the standards work is one leg of a broader thesis that also leans on streaming and cloud contracts, injunction backed HEVC licenses, and newer IoT and automotive deals. Execution risk sits in converting that standards and patent work into long term fixed fee agreements while keeping enforcement spending contained enough for InterDigital to sustain margins and capital returns.
InterDigital Analyst Assumptions And Valuation Setup
InterDigital's long term story in the standards world now meets some fairly specific analyst math. Current consensus wraps Joseph Levy’s added IEEE influence into a wider model that still leans on modest top line expansion, fatter margins, and an earnings profile built around licensing breadth rather than volume hardware sales.
Analysts are working off a revenue trajectory that compounds at 3.9% a year over the next three years, with profit margins modeled to move from 38.3% today to 42.1% by around 2029. Earnings are pegged at US$302.2 million today and are forecast to reach US$371.6 million by the 2029 estimate year, with earnings per share of US$12.17, implying that the profit base would need to be roughly US$69 million higher than it is now. That lift in profitability is assumed to support a P/E multiple of 41.6x on those 2029 earnings, compared with 28.6x today and a current US Software sector P/E reference point of 29.8x, while the share count is expected to creep up by 0.24% per year for the next three years.
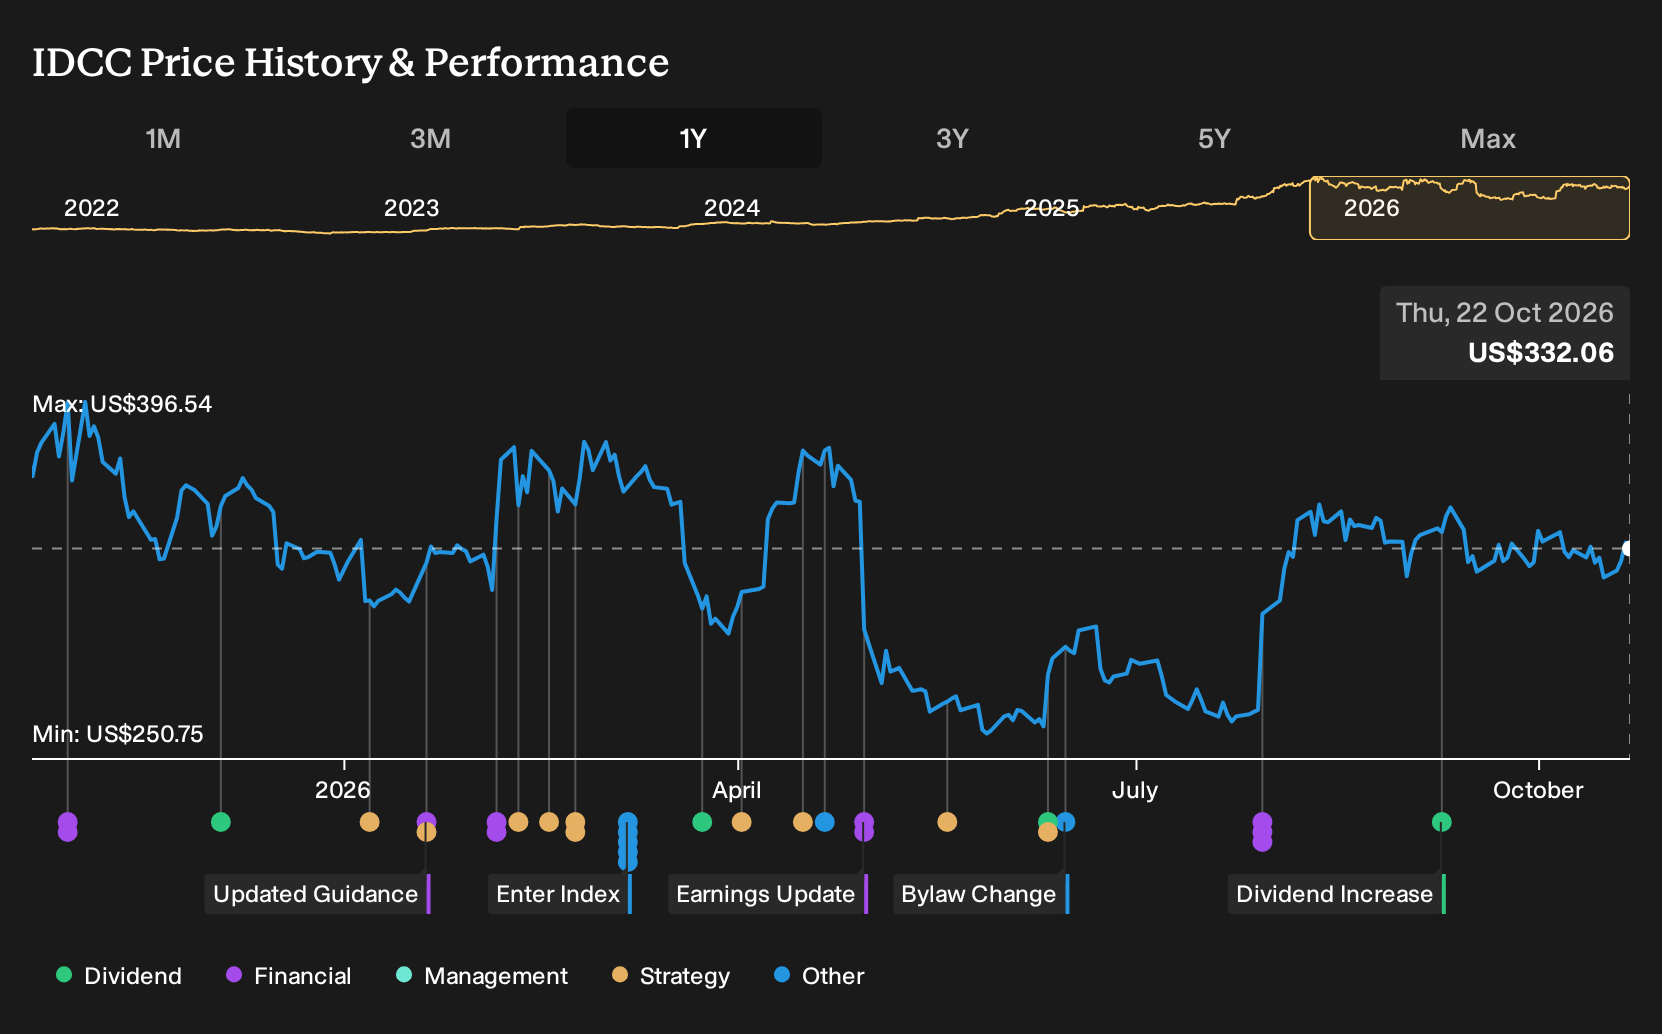
All of this is pulled back to today using a discount rate of 8.71%, which frames the consensus price target of US$462.67 per share against a current price of US$335.13. That gap of 27.6% reflects the degree to which the analyst group believes the projected revenue of US$883.6 million and earnings of US$371.6 million in 2029 would justify a higher market value if InterDigital’s licensing, enforcement and cash deployment plans stay broadly aligned with these inputs.
InterDigital's narrative projects US$883.6 million revenue and US$371.6 million earnings by 2029. This setup assumes 3.9% yearly revenue growth and an earnings increase of about US$69 million from current earnings of US$302.2 million.
Uncover why InterDigital's fair value indicates a 39% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate storyline around InterDigital focuses less on Joseph Levy’s IEEE role and more on enforcement costs staying high. The most cautious analysts were already baking in earnings of about US$422.4 million on roughly US$984.2 million revenue by 2029. Those projections came before this news, so their views could shift.
Explore 3 other InterDigital fair value estimates, including one that suggests there could be as much as 37% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your InterDigital research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for InterDigital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate InterDigital's overall financial health at a glance.
Looking For More Investment Ideas Beyond InterDigital?
If you want to stress test your view on InterDigital against what else is out there, broadening your watchlist with a few focused screens can help you see where risk and quality line up more cleanly.
- For investors who care most about financial strength and resilience, start with a list of solid balance sheet and fundamentals (26 results) that can help you focus on sturdier businesses when conditions get choppy.
- If you would rather keep potential drawdowns contained, scan a 30 resilient stocks with low risk scores to see which companies pair lower risk scores with more measured return profiles.
- When you want to cast a wider net for fresh ideas with strong fundamentals, run a 20 high quality undiscovered gems that surfaces less crowded opportunities for deeper research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com