


Enterprise Products Partners has delivered a strong run over the past several years, and the stock now trades at a level where investors are increasingly focused on what its earnings actually justify. The question is whether the current price reflects a sensible multiple of the partnership’s profit power or leans too heavily on sentiment.
- Over the past 5 years the unit price has gained 120.7%, which puts real pressure on the earnings profile to support that kind of wealth creation for unitholders.
- The partnership’s midstream model, built around fee-based pipelines and storage infrastructure, can anchor relatively steady earnings, so investors naturally look at what multiple of those profits they are now being asked to pay.
- The analysts covering Enterprise Products Partners have run their own numbers. See what analysts think Enterprise Products Partners's shares could be worth.
The issue now is whether Enterprise Products Partners’ current earnings justify the price you see on the screen today.
If you are weighing whether Enterprise Products Partners’ 120.7% five year return matches its earnings profile, it can help to compare that question with a wider group of 30 high quality undervalued stocks.
Is Enterprise Products Partners Still Cheap on Earnings?
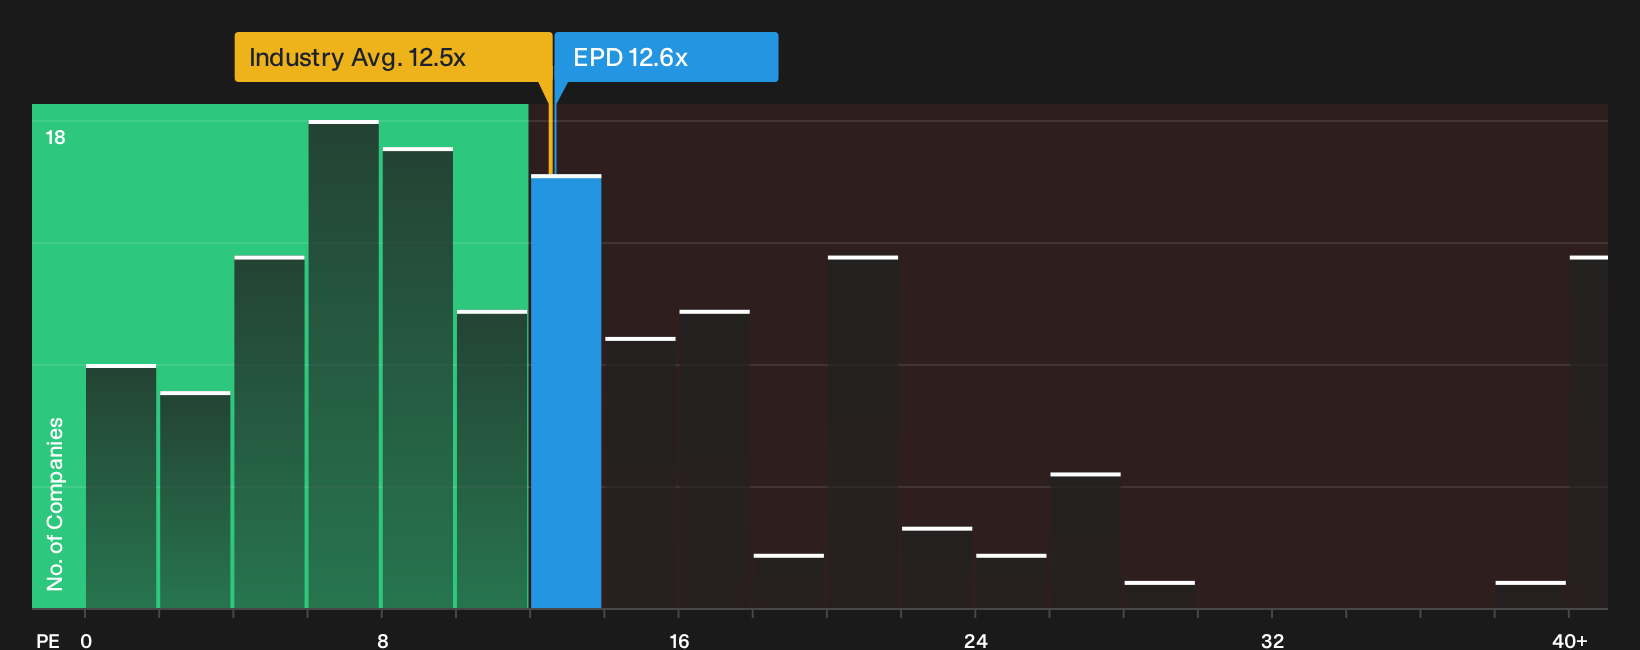
The P/E ratio suits Enterprise Products Partners because the partnership’s fee-based model tends to generate a clearer earnings stream than many commodity-driven players. On this metric, Enterprise Products Partners trades on a P/E of about 12.6x, very close to the Oil and Gas industry average of roughly 12.5x. Against its wider peer group, where the typical P/E comes in nearer 22.7x, the units change hands at a clear discount.
The more tailored fair P/E that blends the partnership’s growth profile, margins, scale and risk points to a higher figure than the current 12.6x. That gap suggests the market is pricing Enterprise Products Partners below what this framework would indicate for a business with similar fundamentals. Any investor weighing the recent unit price run against earnings power needs to decide whether that discount reflects genuine risk or an opportunity. Explore the numbers behind Enterprise Products Partners's P/E valuation.
The Enterprise Products Partners Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E work for Enterprise Products Partners leaves off by spelling out what path for future earnings, margins and growth would need to play out for the current unit price to look either conservative or stretched. Where a single ratio or model gives one headline figure, these scenarios unpack the future that number relies on so you can watch how reality lines up with it on the Community page.
One of the top community narratives on Enterprise Products Partners: 12% undervalued
"Management’s focus on leveraging growth capital for high-demand projects in 2025 and 2026, aligned with the use of discretionary free cash flow…"
Discover why this Narrative puts Enterprise Products Partners at 12% undervalued.
One more question for Enterprise Products Partners that the valuation does not answer
Price and earnings only tell part of the story for Enterprise Products Partners, because separate checks have highlighted potential pressure points that could matter a lot to future unitholders. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com