


- Brookfield Corporation recently completed a CAD 150 million fixed income offering, issuing 6,000,000 non convertible Class A preferred shares at CAD 25 each. Trading in the new issue briefly paused and then resumed under CIRO oversight.
- The fresh preferred equity adds another funding lever for Brookfield, which may influence its cost of capital and how it finances real asset driven opportunities and balance sheet needs.
- Now the focus shifts to how Brookfield’s investment narrative absorbs a new preferred share layer that could reshape funding flexibility and income appeal.
Compare Brookfield’s fresh preferred issuance with other balance sheet focused opportunities by scanning our hand picked list of solid balance sheet and fundamentals (7 results) that could complement this kind of income oriented exposure.
What Is Brookfield's Investment Narrative?
To own Brookfield, you have to be comfortable with a global real asset and asset management platform that is capital hungry and complex, but built to collect fees and investment income from infrastructure, real estate, renewables, private equity and credit across cycles. The big belief is that management can keep sourcing deals, recycling capital and lifting fee bearing capital faster than funding costs and structure complexity eat into economics.
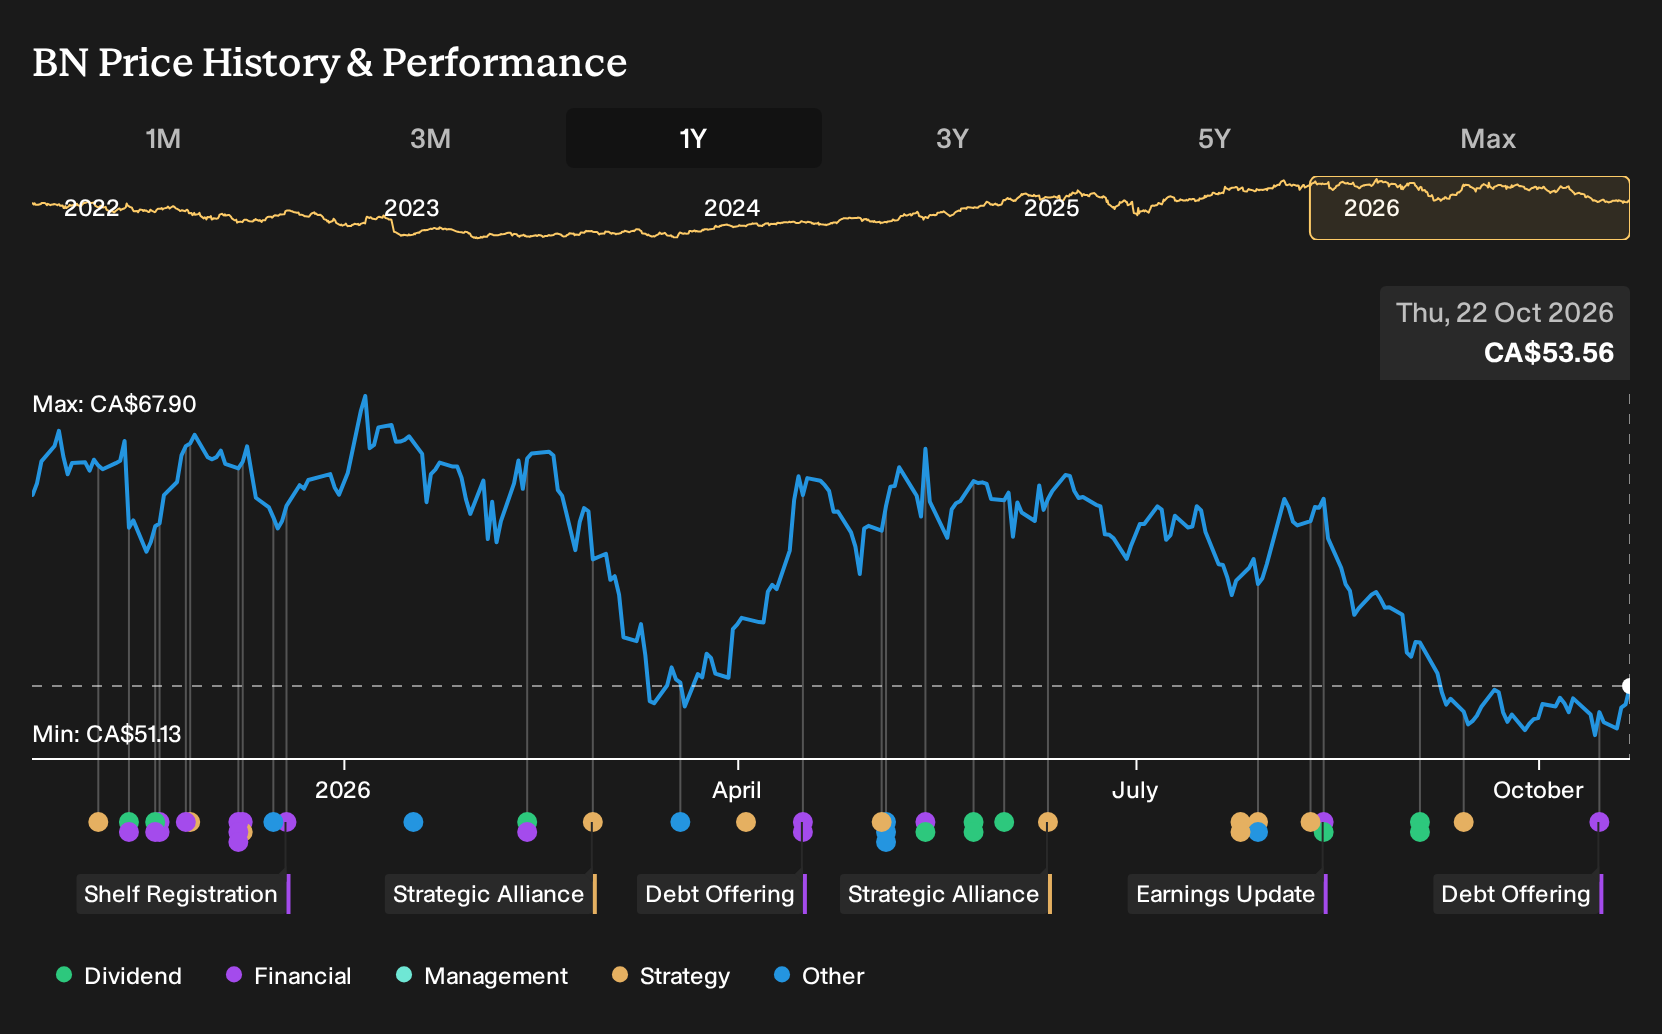
The fresh CAD 150 million preferred share issue fits directly into that story as another layer of funding rather than a business turning point. It modestly widens Brookfield's toolkit for backing large, capital intensive assets, but does not change the near term swing factors around earnings volatility, a P/E of 67.9x and interest costs that are not well covered by current profits. With the stock down 16.4% year to date and trading below the average analyst target, the tension between recent 86.2% earnings growth and a five year earnings decline of 37.1% a year remains a central debate.
Even so, there is a specific balance sheet pressure that could matter far more than this preferred issue if...
There's only one way to know the right time to buy, sell or hold Brookfield. Head to Simply Wall St's company report for the latest analysis of Brookfield's Fair Value.
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community range from almost $0 per share up to $82, so you are looking at widely differing convictions on Brookfield. Those views were formed before the new CAD 150 million preferred issue. Revisiting them now can help you weigh how fresh funding choices might influence future resilience and income appeal.
Explore 5 other Brookfield fair value estimates, including one that suggests as much as 100% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Brookfield research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Brookfield. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brookfield's overall financial health at a glance.
Looking For More Brookfield Style Investment Ideas?
If Brookfield has you thinking about how funding structures, income potential and balance sheet strength fit together, it can help to widen your watchlist using the Simply Wall St Screener. That way you can put this preferred share move in context alongside other businesses with different risk and return profiles.
- For investors who want potential mispricing combined with quality fundamentals, consider scanning a curated set of 3 high quality undervalued stocks that might sit on your radar for a closer look.
- If capital preservation sits higher on your priority list, you can focus on a 8 resilient stocks with low risk scores that aims to keep volatility and financial fragility in check.
- For those hunting for income strength backed by solid finances, filter for companies through a 3 dividend fortresses that pairs yield with balance sheet support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com