


- Castellum reported plans for share buybacks of up to SEK 8b, funded mainly from property sales, alongside a 15% reduction in administration costs and a streamlined regional structure.
- The decision to commit 60% of property sale proceeds to repurchases, with the rest targeting debt repayment, shows management actively reworking both capital allocation and the operating model at the same time as leasing remains weak and property values have fallen.
- We will examine how Castellum's investment narrative is affected as management prioritises the SEK 8b buyback together with efficiency measures.
Compare Castellum's capital return playbook with other property-focused businesses by scanning our hand-picked list of solid balance sheet and fundamentals (203 results) that might better align with your risk and income profile.
Castellum Investment Narrative Recap
To own Castellum, you need to be comfortable with a commercial property group that is still working through weaker office demand, pressure on like for like rental income and a current occupancy rate of 87.5%. The short term swing factor is whether vacancies and rent renegotiations stabilise, because income and net operating income are already under pressure from lower rents and higher costs.
The largest operational risk right now is that negative net leasing and lower renegotiated rents continue to drag on revenue while property values already reflect softer cash flow assumptions. The new SEK 8b buyback and cost cuts do not change that core exposure; they mostly determine how existing cash flows are split between debt costs and equity holders.
The most relevant decision alongside the new programme is Castellum’s ongoing sale of SEK 24b of properties at prices on average 2% above prior fair values, with 60% of fresh disposals earmarked for buybacks and the rest for debt repayment. Asset rotation at modest premia to book helps the group reweight away from lower yielding properties while still freeing liquidity.
This recycling and capital return mix sits alongside the main catalysts around cost savings and interest expense. Administrative expenses have already fallen by about SEK 99m year on year, with annual savings of roughly SEK 70m to SEK 80m targeted, while management aims to bring interest bearing liabilities down to SEK 49b to SEK 51b to keep the balance sheet supporting those efforts.
Castellum's analyst narrative points to SEK 7.8b in revenue and SEK 4.3b in earnings by 2029, based on a 7.9% yearly decline in revenue and an earnings increase of about SEK 1.6b from SEK 2.7b today.
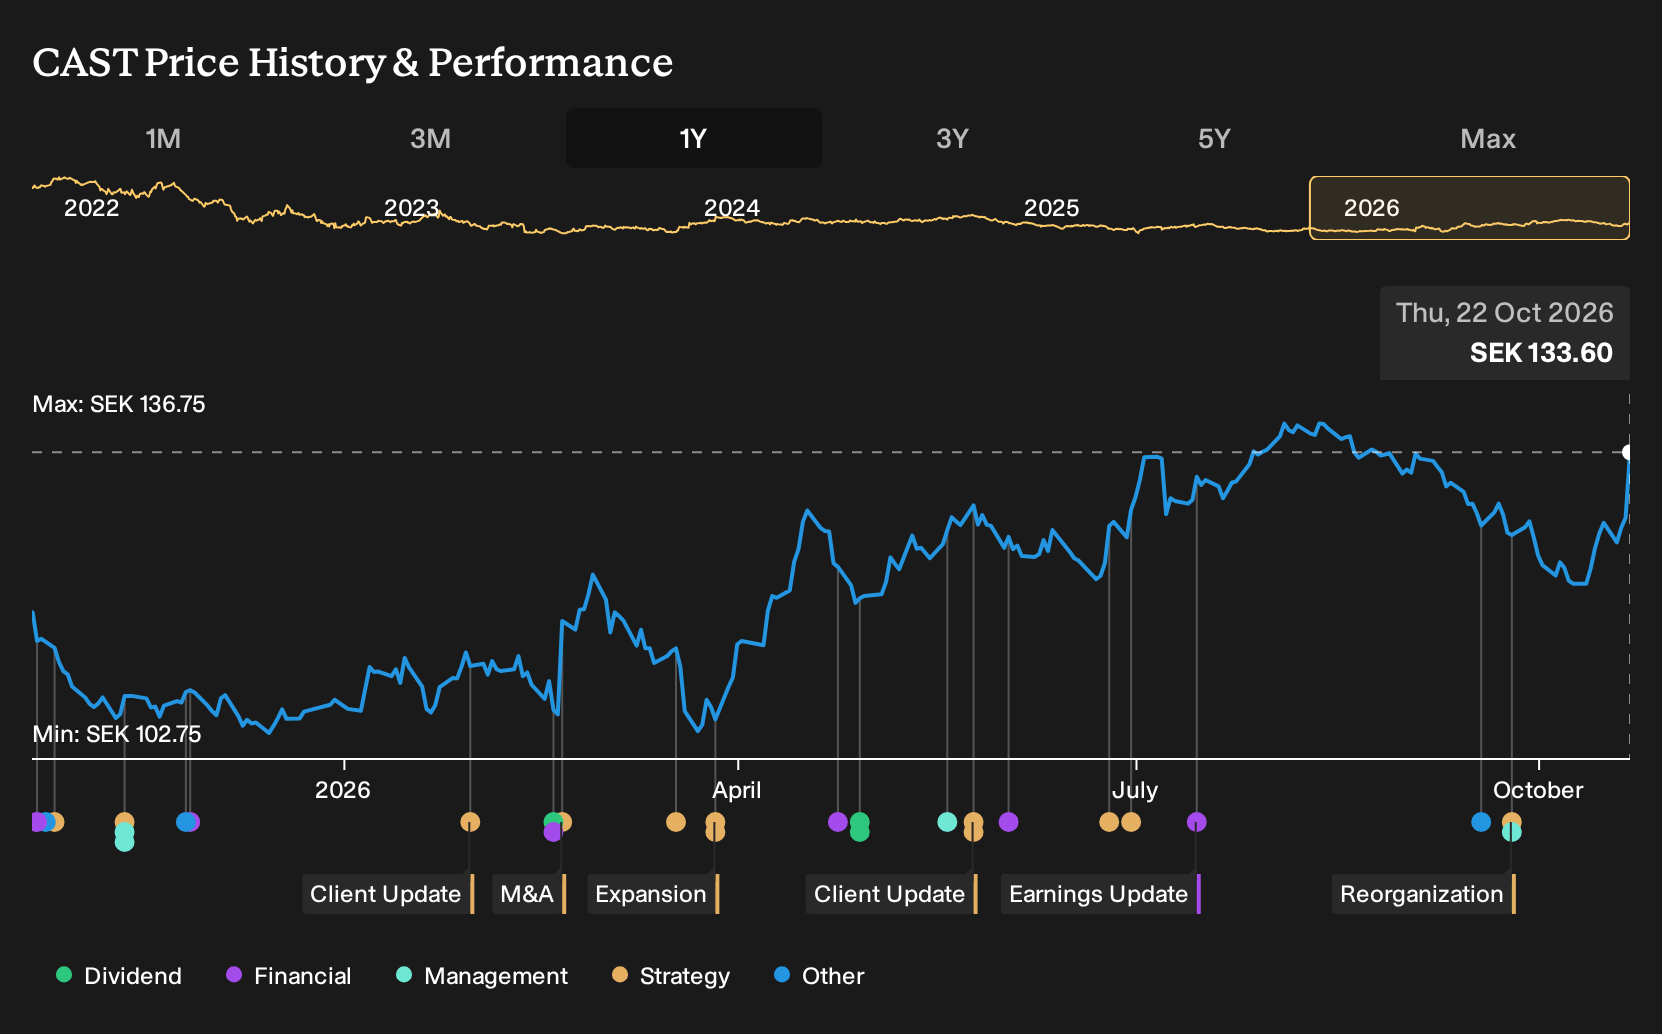
Uncover why Castellum's fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Castellum’s property sales and buybacks as the key catalyst. Before this new SEK 8b programme, the bullish camp was already modelling SEK 9.0b of revenue and SEK 5.3b in earnings by 2029. Their view could shift again, so treat these forecasts as one of several perspectives to explore.
Explore 3 other Castellum fair value estimates, including one that suggests a potential 12% increase from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Castellum research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Castellum. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Castellum's overall financial health at a glance.
Looking for more investment ideas beyond Castellum?
If Castellum has sharpened your thinking about risk, balance sheets and income resilience, it can be useful to compare it with other companies with different profiles using the Simply Wall St Screener.
- For investors who want potential upside with stronger fundamentals, start by scanning a curated set of 619 high quality undiscovered gems that pair quality metrics with room for the story to develop.
- If capital preservation matters most to you, narrow the field to companies with steadier profiles by filtering through a 223 resilient stocks with low risk scores that focuses on resilience scores and financial strength.
- For those who care about balance sheet support behind any capital return plan, compare Castellum with a list of solid balance sheet and fundamentals (203 results) and see which businesses better match your comfort zone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com