


Amidst global market fluctuations driven by concerns over AI spending and inflation pressures, the Asian markets have been navigating a complex landscape marked by geopolitical tensions and shifting investor sentiment. In this environment, growth companies with high insider ownership can offer a unique appeal, as strong insider stakes often signal confidence in the company's future prospects and alignment with shareholder interests.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Meitu (SEHK:1357) | 23.1% | 26.7% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Fulin Precision (SZSE:300432) | 11.7% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
Here's a peek at a few of the choices from the screener.
ROBOTIS (KOSDAQ:A108490)
Simply Wall St Growth Rating: ★★★★★☆
Overview: ROBOTIS Co., Ltd. offers robotic solutions in South Korea and has a market capitalization of ₩3.40 trillion.
Operations: The company generates revenue of ₩48.06 billion from developing, manufacturing, and selling personal robots.
Insider Ownership: 21.3%
Earnings Growth Forecast: 108.2% p.a.
ROBOTIS demonstrates strong growth potential with forecasted annual revenue growth of 63.7%, significantly outpacing the Korean market's average. Despite a low projected return on equity of 10.6% in three years, the company is expected to achieve profitability within this period, suggesting robust earnings expansion at 108.17% per year. Recent financials show substantial improvement in quarterly net income, but high share price volatility remains a concern for investors focusing on stability.
- Click to explore a detailed breakdown of our findings in ROBOTIS' earnings growth report.
- According our valuation report, there's an indication that ROBOTIS' share price might be on the expensive side.
Shanghai Aiko Solar EnergyLtd (SHSE:600732)
Simply Wall St Growth Rating: ★★★★★★
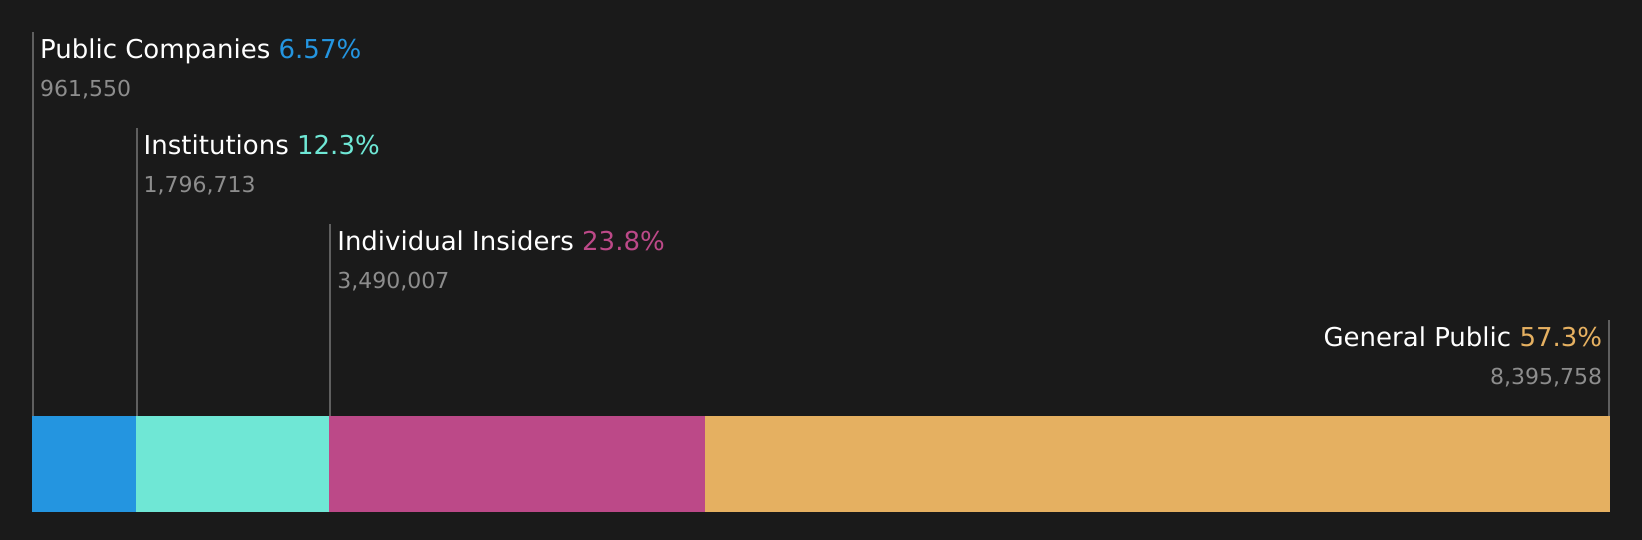
Overview: Shanghai Aiko Solar Energy Co., Ltd. is involved in the research, development, manufacture, and sale of photovoltaic products in China and has a market capitalization of CN¥23.83 billion.
Operations: The company generates revenue primarily from the sale of photovoltaic products within China.
Insider Ownership: 15.8%
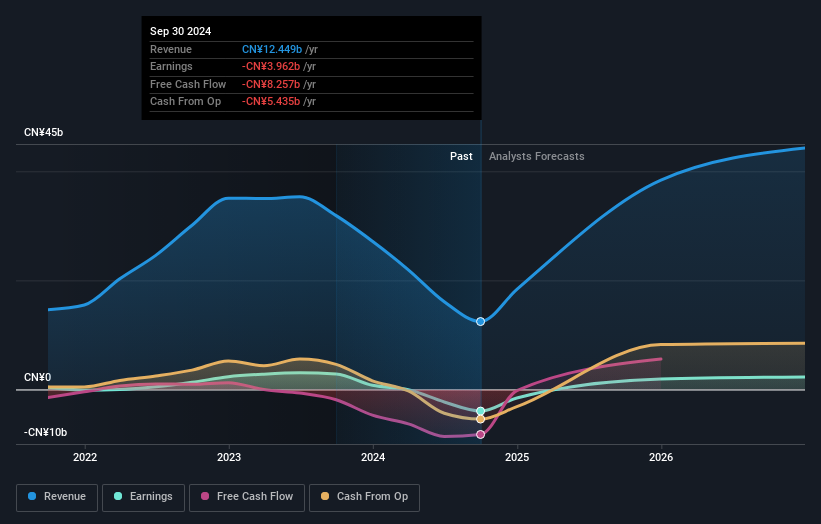
Earnings Growth Forecast: 124.3% p.a.
Shanghai Aiko Solar Energy is trading at a significant discount to its estimated fair value and is expected to achieve profitability in the next three years, with earnings projected to grow 124.35% annually. Despite recent financials showing increased net losses, the company forecasts robust revenue growth of 21.7% per year, surpassing both industry and market averages in China. The absence of substantial insider trading activity over the past three months suggests stability in insider sentiment.
- Take a closer look at Shanghai Aiko Solar EnergyLtd's potential here in our earnings growth report.
- According our valuation report, there's an indication that Shanghai Aiko Solar EnergyLtd's share price might be on the cheaper side.
Kaori Heat Treatment (TWSE:8996)
Simply Wall St Growth Rating: ★★★★★★
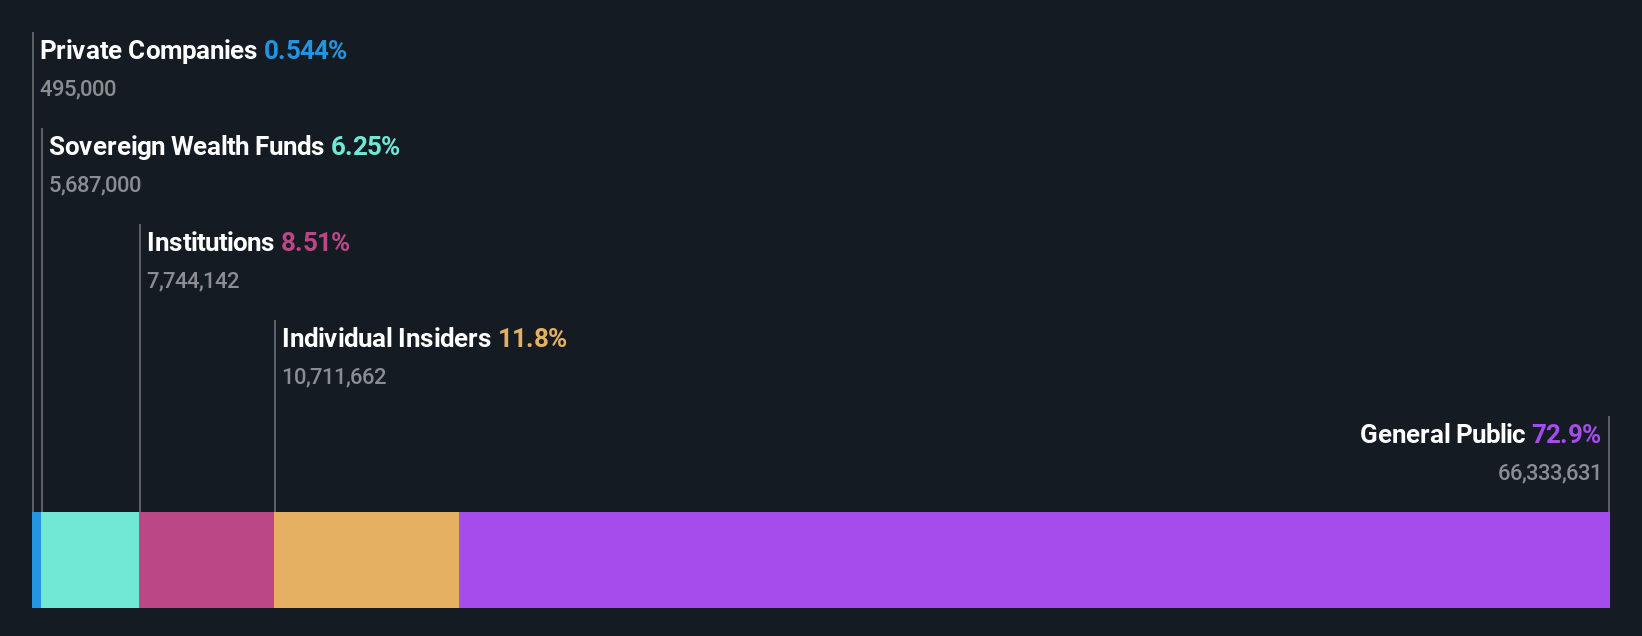
Overview: Kaori Heat Treatment Co., Ltd. specializes in the research, development, manufacture, and sale of heat exchangers and thermal energy products globally, with a market capitalization of NT$145.08 billion.
Operations: The company's revenue is primarily derived from its Plate Heat Exchanger segment, generating NT$1.88 billion, and its Fuel, Electricity, and Thermal Energy segment, contributing NT$7.93 billion.
Insider Ownership: 10.2%
Earnings Growth Forecast: 60.6% p.a.
Kaori Heat Treatment's insider ownership aligns with its robust growth trajectory, evidenced by a significant increase in earnings and sales for the first half of 2026. The company's revenue is projected to grow at 54.1% per year, outpacing the Taiwan market average. Earnings are expected to rise by 60.6% annually, highlighting strong growth potential despite recent share price volatility. No substantial insider trading was reported over the past three months, indicating stable insider sentiment.
- Get an in-depth perspective on Kaori Heat Treatment's performance by reading our analyst estimates report here.
- Insights from our recent valuation report point to the potential overvaluation of Kaori Heat Treatment shares in the market.
Next Steps
- Click this link to deep-dive into the 510 companies within our Fast Growing Asian Companies With High Insider Ownership screener.
- Want To Explore Some Alternatives? These 23 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com