


Man Group has delivered a 5 year return that many investors will notice, yet the recent pullback in the share price raises a simple question for anyone looking at the stock today. Are buyers now paying a level that still lines up with the earnings power of this asset manager, or has sentiment moved ahead of the underlying numbers?
- Over the past 5 years the share price has gained 79.0%. This puts pressure on today’s P/E and related earnings multiples to justify a much richer entry point than in the past.
- Assets under management reached $270.9b as of 30 September 2026, a scale that can support fee income and profit potential if investment performance and inflows hold up over time.
- Your read on Man Group is one view; the desks covering it have another. See what analysts think Man Group's shares could be worth.
The issue now is whether the current valuation of Man Group is adequately supported by its earnings profile when measured against the Fair Ratio benchmark.
If you want a wider watchlist of asset managers and financial groups to research alongside Man Group, start with a focused screen built around 4 resilient stocks with low risk scores.
Is Man Group Still Cheap on Earnings?
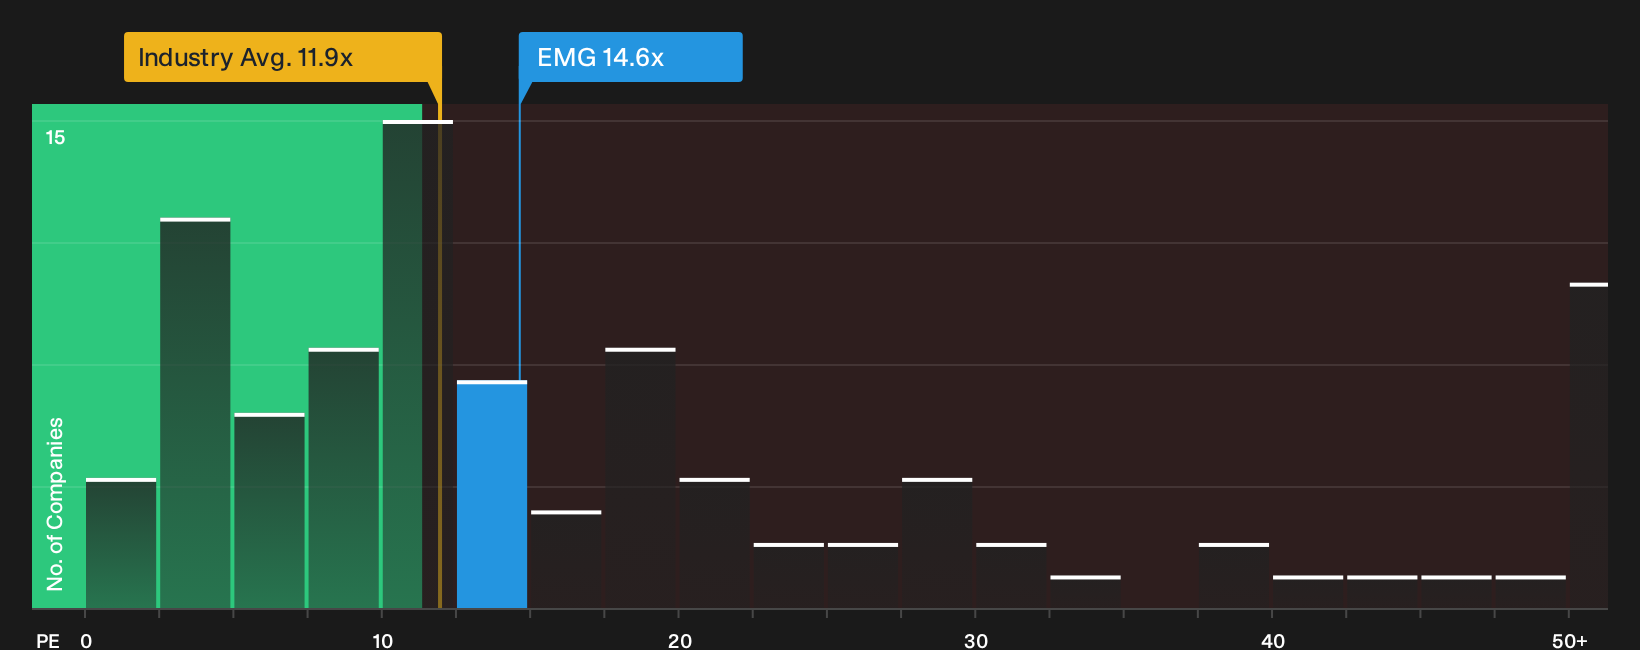
The P/E ratio suits Man Group because earnings still sit at the centre of how investors judge fee based asset managers. On this metric the stock trades at 14.6x earnings, which is above the capital markets sector average of 11.9x but well below the peer group on roughly 37.7x. That gap to peers suggests the market ascribes less of a premium to the quality or durability of Man Group’s profit stream than to some competitors, despite comparable business models on the surface.
Because the current P/E sits below the Fair Ratio benchmark that adjusts for Man Group’s size, risk profile and return on equity, the shares screen as undervalued on this yardstick. Recent headlines around assets under management reaching $270.9b and the share price reaction have lifted interest in the stock, yet the multiple still prices Man Group at a discount to what its earnings profile implies on this framework. For anyone weighing whether that discount is justified, the next step is to probe fee margins, performance fee cyclicality and how sensitive earnings might be to future shifts in flows and markets. Explore the numbers behind Man Group's P/E valuation.
The Man Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Man Group and turn it into concrete paths that spell out what kind of growth, margins and earnings profile would need to unfold for the stock to be worth meaningfully more or materially less than today’s price. Each narrative links its implied number to a clear view on where Man Group's profitability, expansion prospects and key risks could trend, giving you a reference point you can come back to as new information arrives.
One of the top community narratives on Man Group: 14% undervalued
"Strong institutional demand and product diversification are driving sustainable asset growth, recurring fee income, and resilience against market cyclicality..."
Discover why this Narrative puts Man Group at 14% undervalued.
Before acting on Man Group's valuation, there is one more influence to consider
The figures only tell part of the story, because the people directing Man Group and the way their pay is structured can shape risk appetite, capital allocation, and long term discipline. See who runs Man Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com