


HubSpot shares have bounced recently, yet the longer track record is weak, which puts a spotlight on whether the current valuation is properly supported by the company’s earnings. With the stock trying to regain lost ground, the key issue for you is how much of HubSpot’s profit story is already embedded in today’s price.
- Over the past 5 years the stock has fallen 67.2%, which raises the question of whether the market has already reset expectations for HubSpot’s earnings power or is still grappling with what those profits are worth.
- Recent selling linked to concerns around funding artificial intelligence projects and higher interest rates points to investor focus on how HubSpot may balance future growth investment with the cost of capital and the timing of any earnings it can generate from those efforts.
- There is a second opinion on HubSpot worth weighing. See what analysts think HubSpot's shares could be worth.
The issue now is whether HubSpot’s current share price can be justified by the earnings investors expect the business to produce.
If you want a benchmark while you weigh HubSpot against other AI focused stories, compare it with companies in 38 profitable AI stocks that aren't just burning cash.
Is HubSpot Getting Expensive on Earnings?
P/E fits HubSpot because investors are centering the debate on what level of earnings can ultimately back the current share price.
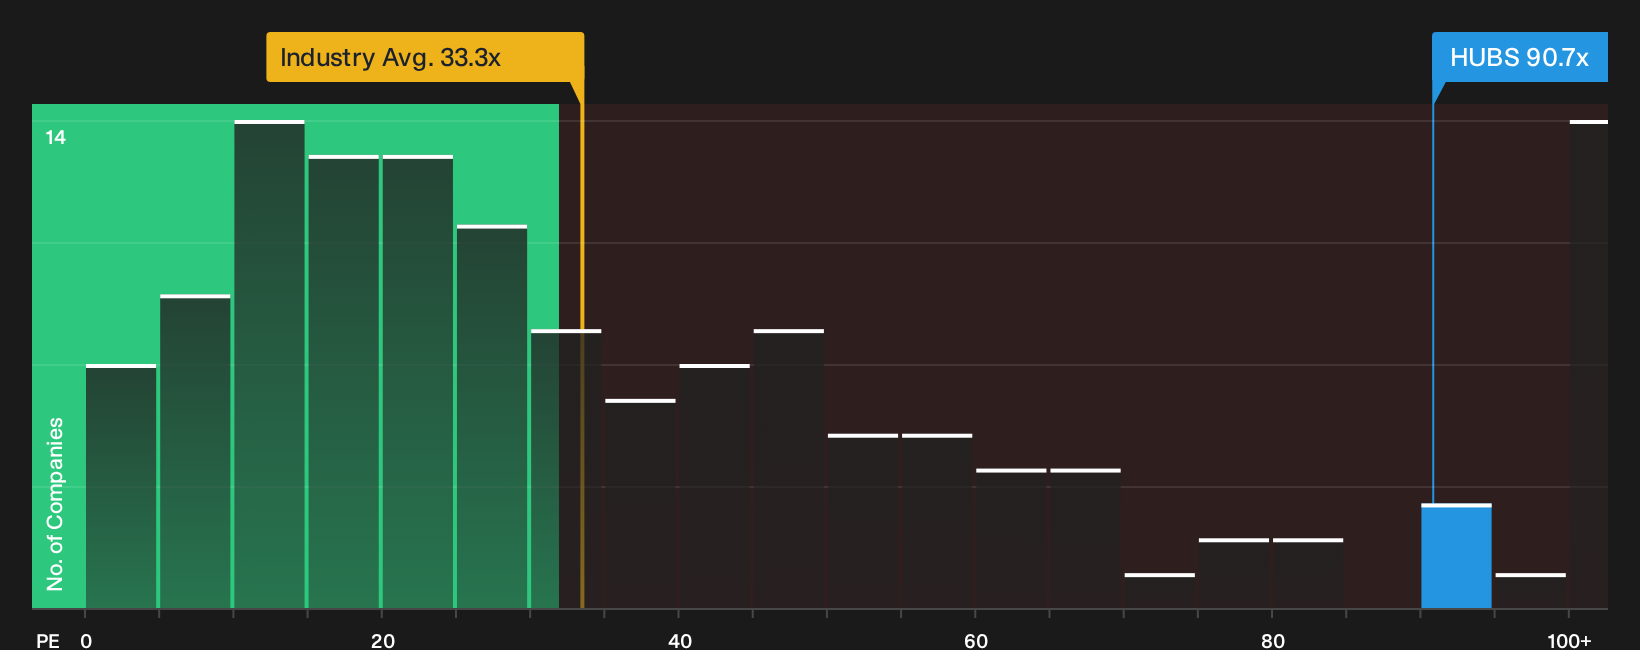
The stock trades on a P/E of about 90.7x, which is well above the broader software sector on 33.3x and also higher than direct peers around 62.1x. On this framework, the tailored fair multiple that blends HubSpot’s growth profile, profitability, scale and risk indicates that the current valuation appears overvalued rather than neutral.
Because the recent AI funding worries and higher rate concerns have already hit HubSpot’s share price, this richer P/E suggests investors are still paying a premium for the earnings path they expect the company to deliver. For you as a shareholder or prospective buyer, the key question is whether that earnings trajectory and risk level seem strong enough to justify paying so far above sector and peer benchmarks on this metric. Explore the numbers behind HubSpot's P/E valuation.
The HubSpot Narrative: What Would Justify Today's Price?
Simply Wall St Narratives picks up where HubSpot's valuation puzzle leaves off. It spells out which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than it is today on the Community page. Each scenario ties a fair value to a particular mix of potential catalysts and risks for HubSpot's business so you can track over time which version of events is gaining traction.
Community views on HubSpot are split between those who see the current P/E as an opportunity and those who think expectations already look full.
Bull case: 19% undervalued
"HubSpot is a leading, product-led CRM platform for SMBs and mid-market companies that bundles marketing, sales, service, operations and commerce capabilities in an easy-to-adopt cloud suite..."
Discover why this Narrative puts HubSpot at 19% undervalued.
Bear case: 7% overvalued
"Rising competition from larger, consolidated SaaS providers and emerging Agentic/AI-powered platforms could lead to downward pricing pressure, higher customer acquisition costs, and increased difficulty in sustaining market share growth..."
Explore why this Narrative puts HubSpot at 7% overvalued.
One more HubSpot check that sits beside the share price
Price tags tell only part of the story, because the people setting priorities, allocating capital and rewarding themselves can tilt your risk far more than any P/E line ever will. See who runs HubSpot and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com